Sam Walton Gave His Kids 80% of Walmart in 1953, When It Was Worth Almost Nothing. That Single Early Move Is Why the Waltons Have Never Faced a Major Estate-Tax Bill on $250 Billion
Sam Walton made one early financial move with his family business that the IRS still allows today, and it quietly kept hundreds of billions of dollars out of reach of federal estate taxes for generations. Most families with appreciating assets…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
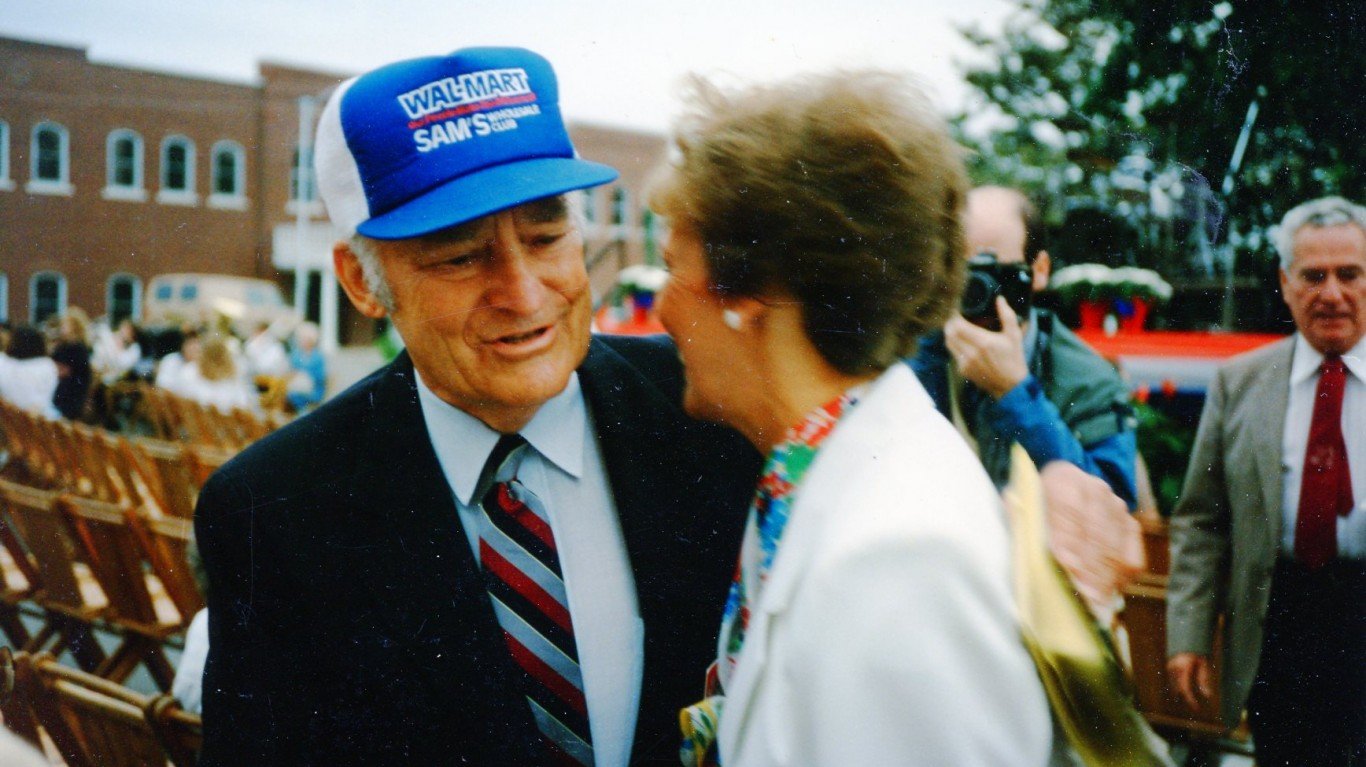
If you own a small business, a rental property, or a chunk of stock you expect to multiply, the Walton family already ran the playbook. In 1953, Sam Walton and his wife Helen took advice from her father, Leland Robson, and organized their retail holdings as a family partnership. They handed roughly 80% of that business to their four children, Rob, John, Jim, and Alice, each receiving a 20% stake, years before the first Walmart (NYSE:WMT | WMT Price Prediction) store opened its doors. That single decision, gifting an asset while it was worth almost nothing, is why the heirs have avoided a catastrophic federal estate tax bill despite a combined family fortune that Bloomberg’s Billionaires Index pegged at roughly $430 to $475 billion in 2026. It is a strategy the IRS still allows today, and you do not need a retail empire to use it.
The Buried Rule: Gifts Are Frozen at Today’s Value
The key quirk in the estate and gift tax code is straightforward once you see it. When you give an asset away during your lifetime, the IRS values that gift on the day you make it. Every dollar of appreciation after that date happens inside someone else’s hands, entirely outside your taxable estate. Sam Walton did not gift hundreds of billions of dollars in stock. He gifted a modest family partnership interest in the early 1950s, when it was worth almost nothing. All the growth that followed, the stores, the split-adjusted shares, the decades of dividends, compounded in his children’s names rather than his own. In his autobiography “Sam Walton: Made in America,” Walton spelled out the logic plainly: “The transfer of ownership was made so long ago that we didn’t have to pay substantial gift or inheritance taxes on it.” He added that “the best way to reduce paying estate taxes is to give your assets away before they appreciate.” That is the principle ordinary families miss: the earlier you transfer an appreciating asset, the more future gain escapes the estate tax permanently.
The Proof in the Code
This approach is built directly into how the IRS structures gift and estate taxes under Internal Revenue Code Chapter 12 (gift tax) and Chapter 11 (estate tax). The numbers for 2026 are the most favorable in decades. For 2026, the annual exclusion for gifts is $19,000 per recipient. On the lifetime side, the One Big Beautiful Bill Act, signed into law on July 4, 2025, permanently raised the estate, gift, and generation-skipping transfer exemption to $15 million per individual, up from $13,990,000 in 2025. Married couples can shelter $30 million combined. The law also indexed that figure for inflation starting in 2027, so the exemption will grow rather than erode over time. That $15 million figure is both the basic estate exclusion and the lifetime gift exemption you draw down for transfers above the $19,000 annual threshold.
Who Can Actually Use This
Any U.S. taxpayer who holds an asset likely to appreciate can apply this strategy. It works best for owners of closely held businesses, founders with pre-IPO equity, landlords with rental property in an early-stage market, and parents holding concentrated stock positions. Married couples get a significant advantage: each spouse carries a separate $19,000 annual exclusion and a separate $15 million lifetime exemption, for a combined $30 million in shelter. The strategy is less compelling for families whose total estate will land comfortably below $15 million and who plan to leave low-basis assets at death, because the step-up in basis at death often delivers a better outcome in those situations.
How To Run the Walton Play at a Smaller Scale
- Identify the asset you believe will appreciate the most: private company shares, LLC units in a rental property, or a founder stake.
- Obtain a defensible appraisal at today’s low valuation. Valuation discounts for lack of marketability and minority interest often apply to interests in family entities, reducing the taxable value further.
- Gift up to $19,000 per recipient per year to stay inside the annual exclusion, or make a larger gift and file Form 709 to draw down your $15,000,000 lifetime exemption.
- Consider a family limited partnership or trust so you retain management control while transferring equity to the next generation.
- Let time do the work. Every dollar of future growth belongs to the recipients, not to your taxable estate.
The Catch Nobody Advertises
There is one tradeoff you need to understand before replicating the Walton move. Lifetime gifts carry over your original cost basis to the recipient. If you paid $10,000 for stock now worth $1 million and transfer it as a gift, your child inherits your $10,000 basis and owes capital gains tax on the full appreciation when they sell. By contrast, assets held until death generally receive a step-up in basis to fair market value at the time of death, effectively wiping out that embedded gain for heirs who sell promptly. The decision comes down to estate tax exposure versus capital gains tax exposure. The Walton approach wins decisively when the asset is set to appreciate massively and the family intends to hold it for the long term, as the Waltons did with their Walmart shares across generations. It makes less sense when the estate would have fit comfortably under the $15 million exclusion anyway, or when heirs plan to sell shortly after inheriting. Run that math carefully, preferably with a tax planner, before signing any gift paperwork.
Editor’s note: This article has been updated to reflect the Walton family’s current combined net worth of approximately $430 to $475 billion per the Bloomberg Billionaires Index, replacing the earlier “$350 billion” figure, and to add context from Sam Walton’s autobiography and the role of his father-in-law Leland Robson in structuring the 1953 family partnership. The One Big Beautiful Bill Act’s permanent $15 million estate and gift tax exemption, effective January 1, 2026 and indexed for inflation thereafter, is also noted.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)