The Nursing Home Gets Almost Her Entire $2,400 Social Security Benefit. Medicaid Lets Her Keep $30 to $200, Depending on Her State.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Picture a widow whose only income is a $2,400 monthly Social Security benefit. She has just qualified for nursing home Medicaid. Her daughter assumes that check will keep flowing into mom’s account for clothing, phone service, and the small pleasures of daily life.
It won’t. The check may still land in her account, but she will not be free to spend it. After deductions, nearly all of it flows to the nursing home. The state calculates a required monthly contribution to the facility, and after those deductions, the widow keeps only her state’s personal needs allowance (PNA). In Alabama that’s $30. In Alaska it’s $200. Her Social Security earnings record and the quality of the nursing home have nothing to do with the difference.
Medicaid Pays After the Resident Contributes
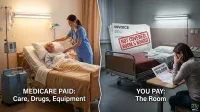
Nursing home Medicaid does not work like private health insurance, which pays the provider while leaving the patient’s income untouched. Once eligible, the resident must contribute nearly all countable income toward care. Caseworkers and facilities call this amount “patient pay,” “patient liability,” “share of cost,” or “applied income.” Medicaid then pays whatever remains on the state-approved daily rate.
Medicare, the federal health program for people 65 and older, does not fund long-term custodial care. It covers up to 100 days of skilled nursing after a qualifying hospital stay, with a $217 daily coinsurance kicking in on day 21 in 2026. After that, families pay privately or turn to Medicaid, the joint federal-state program that becomes the primary payer of custodial nursing home care. The national median cost of a semi-private nursing home room now runs about $9,581 a month, and a private room runs about $10,798, according to CareScout’s 2025 Cost of Care Survey. Those figures underscore why private savings rarely last long and why Medicaid eligibility becomes essential for so many families.
How Patient Liability Gets Calculated
The state Medicaid agency, not the nursing home, sets the number. The simplified sequence:
- Start with Social Security, pension, retirement distributions, and other countable monthly income.
- Subtract the state’s personal needs allowance.
- Subtract allowable health insurance premiums, including the 2026 Medicare Part B standard premium of $202.90, plus uncovered medical expenses.
- If applicable, subtract a Monthly Maintenance Needs Allowance for a spouse still living at home.
- Add a temporary home-maintenance allowance when a return home is medically expected.
Whatever’s left is what the resident owes the facility every month. For a single widow with $2,400 in Social Security, no Medicare Advantage premium, and Part B paid through a Medicare Savings Program, nearly all of that check goes straight to the nursing home.
Federal law requires a personal needs allowance but sets the floor at just $30 per month, unchanged since 1988. States can supplement it and update it whenever they choose. Some haven’t touched theirs in decades. As of July 2026, the national average PNA sits at $75.89 per month, according to the Consumer Voice’s annual state-by-state survey. A resident with identical income and identical care needs can keep more than six times as much in one state as in another.
What $30 a Month Actually Buys
The allowance covers what Medicaid and the facility don’t: clothing, haircuts, phone service, magazines, preferred toiletries, snacks, and the occasional vending-machine treat. At $30 a month, that works out to roughly $1 per day. A single beauty shop visit consumes the entire budget. New shoes mean skipping everything else for the month.
Basic services and required supplies are the facility’s responsibility. It cannot bill the personal needs account for laundry, over-the-counter medications ordered by the facility physician, or anything already covered by the Medicaid daily rate.
Marriage, Veterans, and the Trap of Unspent Money
Married residents get more room to breathe. A community spouse living at home can receive part of the institutionalized spouse’s income through the Monthly Maintenance Needs Allowance, which shifts money out of the patient pay calculation. Certain veterans in Medicaid-funded facilities are also limited to a $90 pension payment that’s protected from patient pay entirely.
One subtle risk deserves attention: the allowance itself. Residents don’t have to spend it, and unspent balances accumulate in the resident trust account the nursing home manages. Push above the state Medicaid asset limit and continued eligibility can wobble. Families who ignore the trust statement can accidentally disqualify a parent by letting a few dollars a month pile up over years.
Families should request the state’s written patient liability calculation, verify that insurance premiums were deducted, ask whether a spousal or veteran allowance applies, and review the trust statement quarterly. When a facility improperly charges the account, the state long-term care ombudsman is a free complaint channel. Medicaid covers a nursing home bill that can run from roughly $9,581 to $10,798 or more per month nationally, but a resident’s ZIP code alone decides whether the slice left for personal independence looks like $30 or $200.
Editor’s note: This article was updated to reflect the Consumer Voice’s July 2026 national average personal needs allowance of $75.89 per month (previously stated as “around $70”), and to include current CareScout 2025 Cost of Care Survey figures showing the national median nursing home cost at $9,581 per month for a semi-private room and $10,798 for a private room.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.