He Left His $300,000 IRA to His 12-Year-Old Grandson to Give Him a Head Start. The Clock Started Immediately, and Every Withdrawal Until 19 Was Taxed at His Parents’ Rate
A grandfather's generous plan to give his grandson a $300,000 head start ran into two federal rules that began working against the boy the moment the death certificate was filed, and most families setting up the same arrangement have no…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A grandfather names his 12-year-old grandson as the sole beneficiary of a $300,000 traditional IRA, intending to seed the child’s future with decades of tax-deferred growth. Two federal rules, however, landed on the grandson the day the death certificate was filed.
Why the Ten-Year Clock Started Immediately
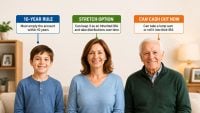
The SECURE Act eliminated the old stretch IRA for most beneficiaries who inherit from an owner who died in 2020 or later. In its place is a ten-year rule: the account must be fully distributed by the end of the tenth calendar year after the original owner’s death. The statute has a narrow carve-out for what it calls an eligible designated beneficiary, and one category is a minor. The detail that trips families up is that the minor exception applies only to a minor child of the account owner, not to a grandchild, niece, nephew, or any other minor relative.
Even a qualifying minor child does not get an indefinite stretch. Under Treasury regulations, favorable treatment ends when the child reaches age 21, and the ten-year clock begins running at that point. The grandson in this scenario never had that runway. Because a grandchild is not a minor child of the decedent, the ten-year rule applied from day one, regardless of his age when he inherited. IRS final regulations issued in July 2024 added another layer: beneficiaries subject to the ten-year rule who inherit from an owner who had already begun taking required minimum distributions must also take annual RMDs during the ten-year window, rather than simply waiting to empty the account in year ten.
How the Kiddie Tax Piles On
Sitting on top of the payout rule is the tax treatment of a child’s investment income. Under the kiddie tax, unearned income above a small annual threshold is taxed at the parents’ marginal rate rather than the child’s own lower rate. For 2025, the first $1,350 of unearned income is offset by the child’s standard deduction, the next $1,350 is taxed at the child’s rate, and everything above $2,700 is taxed at the parents’ rate. The rules apply to children under 18, extend through age 18 when earned income does not exceed half of the child’s support, and reach through age 23 for a full-time student under the same support test.
Why the Combination Is Particularly Harsh
The two rules interlock in a punishing way. The ten-year window forces the account to be emptied while the beneficiary is roughly 13 to 22. The kiddie tax applies for most of that span, so distributions in the early and middle years fall into the least favorable rate available. Waiting until the kiddie tax no longer applies does not solve the problem, because the remaining balance must still come out by year ten in fewer and larger chunks, pushing the beneficiary into higher brackets as a young adult. With the 10-year Treasury yielding around 5.2%, even a conservative allocation continues generating taxable income inside the account during every drawdown year.
An inherited IRA left outright to a minor also requires a custodian or guardian under state law until the age of majority, which is 18 or 21 depending on the state. Whatever remains on that birthday belongs to the beneficiary with no strings attached. A grandparent picturing a down payment at 30 may be handing an 18-year-old a six-figure check with no conditions.
Changes That Actually Preserve the Intent
The cleanest fix is to leave a Roth IRA rather than a traditional one. Qualified distributions from an inherited Roth are generally income-tax-free, so the ten-year drawdown still applies, but the kiddie tax has nothing to reach. If the grandfather is still living, converting the traditional IRA to a Roth during his lifetime pays the tax at his bracket, which is often lower than the parents’ bracket, and removes the problem entirely.
A properly drafted see-through or accumulation trust can control timing and protect the beneficiary from receiving a lump sum at 18 or 21. The tradeoff is that retained trust income hits the top federal rate at only a few thousand dollars of income. Leaving the IRA to adult children and directing other assets to the grandchild often produces the best overall result. Most of these estate complications trace back to a stale beneficiary form or the wrong account going to the wrong person. A 529 plan or a UTMA funded with non-retirement dollars serves the head-start goal more efficiently (and you can find the full beneficiary-form cleanup checklist in a free guide here).
Specific Change to Make on the Beneficiary Form
The action to consider is narrow: replace the grandchild’s name on the traditional IRA beneficiary designation with the adult child or a properly drafted trust, and direct the equivalent value to the grandchild through a Roth account, a 529, or a UTMA. The generosity survives; the two rules that quietly undermined it no longer apply.
Editor’s note: This update corrects the 10-year Treasury yield figure from 5% to approximately 5.2%, reflecting current market levels, and adds context from the IRS final SECURE Act regulations issued in July 2024, which confirmed that annual RMDs are required during the ten-year window when the original owner had already begun distributions.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.