‘It’s Just Gone’: Daughter Says Her 84-Year-Old Mom Wrote 41 Checks in One Month and Gave Away $200,000
An 84-year-old woman moved in with her daughter carrying $400,000 from selling her home, and half of it has quietly vanished through a checkbook no one had the legal authority to close.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
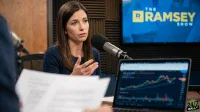
“It’s gone. It’s just gone.” A 60-year-old caller named Sophia used those words on a recent episode of The Ramsey Show to describe her mother’s money.
Her 84-year-old mother wrote 41 checks last month, averaging $27 each, to charities and political organizations. The total ran to about $1,100 in one month.
That monthly figure is the visible part of a much larger drain. The mother moved in with Sophia’s family in 2022 carrying a $400,000 check from selling her house. Roughly $200,000 of it has since left her accounts.
What remains is about $150,000 in a CD, $43,800 in savings and $2,000 in checking. Every check written today comes out of the fund meant for her later care.
That care is coming. Sophia is 60 and has MS. Her husband is 63 with a bad back. The family expects to need paid help in the home for her mother, who still drives.
A Safe CD Can’t Outrun an Open Checkbook
Hosts George Kamel and Jade Warshaw told Sophia to get a durable power of attorney, trace the checks, choke off the appeals, cap the giving and invest the CD. That advice is right, and the checkbook comes before the portfolio.
The FDIC national average 12-month CD rate was 1.7% in September 2026. At that rate, the $150,000 CD earns about $2,595 a year.
Her check-writing pace runs roughly $13,200 a year. The money is leaving about five times faster than the CD replaces it. Moving cash into a CD slowed nothing, because the leak runs through the checkbook.
The warning signs showed up earlier. A year before the call, the family found she had taken in about $48,000 in deposits against $90,000 in withdrawals. A gap like that, repeated year after year, is how half a house disappears.
The 1.7% figure is also just the bank average. Top online banks routinely pay 3 to 5 times the national average, and CD rate roundups this week show competitive yields well above it. CD interest is taxable, too, and can push more of a retiree’s Social Security benefits into the taxable zone.
Why is the leak so steady? Sophia said her mother’s name had been “sold to everyone.” Charities call, then mail follow-up appeals, and her mother answers them with checks. She is “forgetful” and “getting more and more forgetful over time,” and she does not know how much has left her account. Kamel raised the possibility of elder abuse.
Her Signature Still Counts, for Now
The variable that determines how this ends is capacity. Sophia’s mother is forgetful but still drives and is not completely incapacitated. While she can understand what she is signing, a durable power of attorney is a simple legal document. It lets Sophia act on her accounts and stays in force if her mother’s memory declines further.
If the family waits until she can no longer sign, that door closes. The usual path then runs through a court guardianship or conservatorship, a process that is slower, more expensive and public. Meanwhile, the checks keep clearing and Sophia has no legal standing to stop them. Getting the document signed while she still has her faculties is the most time-sensitive advice from the call.
Five Moves That Stop the Bleeding This Month
- Sign the durable power of attorney first. Book an elder-law attorney and have the parent sign while she has capacity. Every other step on this list gets easier with that authority in hand.
- Pull the bank statements. Every check leaves a paper trail, as the hosts noted. List every payee from the past year, flag repeat recipients and unfamiliar organizations, and verify any charity before more money goes out.
- Cut off the pipeline. Register her phone numbers on the National Do Not Call Registry and stop the junk mail before it reaches her. Fewer appeals mean fewer checks.
- Set a giving budget. The hosts suggested $100 to $200 a month. That keeps her generosity and dignity intact while limiting the spending well below last month’s $1,100.
- Put the CD money to work. Once authority is in place, move it into investments matched to her care timeline, as the hosts advised. Even cash reserved for near-term care can earn more than a bank-average CD.
Paperwork and a firm budget are what guard her remaining savings against the checkbook. Most late-life money messes trace back to a missing signature, a outdated beneficiary form, or an account no one has authority to touch, which is the whole reason we put a full estate checklist together in a free guide.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)