‘You Can Afford $52,000 Worth of Wasted Money’: Ramsey to Debt-Free 49-Year-Old Eyeing a Knight Rider Replica
A debt-free 49-year-old with a million-dollar net worth called Dave Ramsey for permission to blow $52,000 on a Knight Rider replica, and the answer surprised even him.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
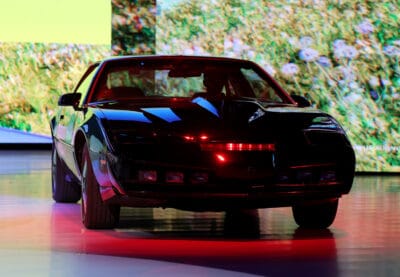
“You can afford $52,000 worth of wasted money. You’ve earned it.” That was Dave Ramsey’s take on the October 7, 2026 episode of The Ramsey Show. The caller was Matt, a 49-year-old from Philadelphia who wanted to buy a studio-accurate Knight Rider replica for $52,000.
Matt is single and has no debt besides his house. He earns a $120,000 base salary plus a 25% bonus. His net worth is about $1 million, including home equity and his 401(k), and he has roughly $110,000 in liquid savings.
He told Ramsey the show changed his life seven years ago, after he bought a car he shouldn’t have. Spending the savings now “pains” him. That hesitation is reasonable. A replica with almost no resale value is a one-way trip for your money. If the math behind the purchase is wrong, you’ve traded your safety net for a toy.
Why Ramsey Got Matt’s Call Right
Ramsey used his standard test. Picture $52,000 stacked in the middle of the floor and set on fire. Does your life change? He noted the purchase would cut Matt’s liquidity in half. He also warned that the resale market for a replica “would be very small.” Then he told Matt to buy it anyway. Co-host George Kamel added: “Enjoy the car.”
Ramsey is right, and the burn test is the right tool. It makes you value the purchase at zero resale. For a niche collectible, this is the realistic accounting.
Do the math. The car is about 5% of Matt’s net worth. Against his total pay of roughly $150,000, it comes to about 35% of a single year’s earnings. He would still have about $58,000 in cash. For a single earner at his income, that still covers a full emergency fund of several months’ expenses.
Opportunity cost is the real price. Say Matt invested the $52,000 at a 7% annual return until age 65 (an assumption for example). It would grow to about $153,500. That’s a real number. Next to a seven-figure net worth that keeps compounding, though, it’s a small, manageable dent. He can see what the fun costs and pay it knowingly.
Cash Versus Credit Decides Every Car Verdict
Earlier in the same episode, Ramsey told a 22-year-old caller that “one definition of maturity is the ability to delay pleasure for a greater good, which is impulse control.” Jonathan from Savannah also called in. He is 18 and earns $2,200 a month. He had financed a $27,000 car with a $24,260 loan. Ramsey told him: “You bought a car that’s completely out of your league. It’s very difficult to prosper when you own a car that costs as much as you make in a year.”
It sounds like a double standard: two men want a car they love, and only one gets a approval. The dividing line is cash versus credit. Matt pays out of surplus he spent years building. Jonathan pays out of paychecks he hasn’t earned yet.
Here’s Jonathan’s math. His annual income works out to about $26,400, which is less than the car’s price. Take a 9% rate over 72 months (an illustrative example). His payment would be about $437 a month.
That eats up nearly 20% of his income. He would also pay about $7,226 in interest on a car that loses value every month.
Matt already did the delaying Ramsey preached to the 22-year-old. He spent seven years building the cash. Now he’s spending it.
Run Your Own Burn Test Before Buying Any Big Toy
- Price it at zero. Take you’ll never get a dollar back. If the purchase only makes sense when you count on resale, it fails the test.
- Divide the price by your net worth. Matt’s car came to about 5% of his net worth. Apply the same division to your own purchase and ask whether you could handle that loss without changing your plans.
- Check what’s left in cash. After the purchase, you should still have three to six months of expenses in savings. If you don’t, wait and keep saving.
- Calculate the opportunity cost. Use a compound interest calculator to grow the price at a conservative return until your retirement age. Look at that number before you decide.
- Refuse financing on wants. If you need a loan to buy it, the burn test fails automatically. You’d be setting fire to money you haven’t earned yet.
If you can buy something you want with cash and lose all of it without changing your life, buy it and enjoy it.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)