He Will Retire in Tennessee Short on Savings. The Lake Houses Their Owners Never Have Time to Manage Will Become His Business
Tennessee's lakes are ringed with vacation homes whose owners live states away and dread every call about a frozen pipe. One retiree with a savings gap and a truck full of tools is wondering whether their headache could become his…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
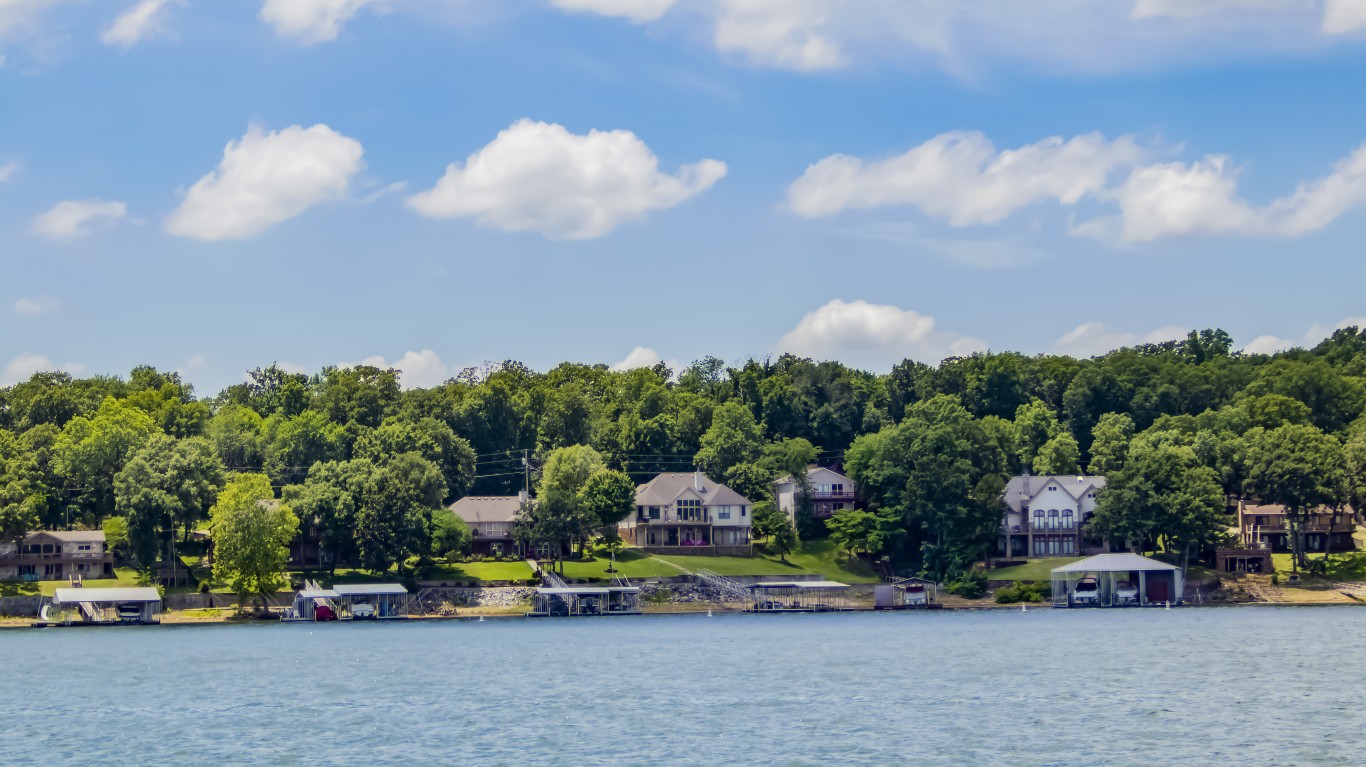
Some retirees settling near Tennessee’s lakes have less savings than planned, while many nearby lake houses sit empty much of the year and still need someone to check pipes, let cleaners in, and winterize boats. This piece looks at what it would take for a retiree to run a caretaking business for those homes, and whether the income actually closes his retirement gap.
How Big His Gap Is Without the Work
Tennessee is cheaper than most places, with a cost-of-living index of 91.87 (100 is the national average). The average U.S. household spent $78,535 in 2024, and when adjusted to Tennessee prices, that’s roughly $72,000. A single retiree may spend less, so this is a conservative benchmark. Lake housing isn’t cheap, though. Near Tellico Lake, many well-kept homes off the water sell for $500,000 to $800,000, and lakefront homes cost more.
The average retired worker’s Social Security check is $2,071 a month after the latest cost-of-living raise. That’s about $24,850 a year, which leaves a gap of roughly $47,300. If he plans to withdraw 4% of his savings each year, covering that gap would require about $1.18 million. For someone short on savings, that figure represents the shortfall.
Taxes also help, since Tennessee is one of nine states with no personal income tax, so the state takes nothing from his wages. The statewide sales tax is 7%, and local governments can add up to 2.75%. Compared to income, the state’s combined state and local tax burden of $5,333 per person is among the lowest in the country.
What Caretaking Lake Houses Actually Involves
The work is mostly showing up. He’d handle guest check-ins and check-outs, schedule cleaning crews, inspect docks and boat lifts, check houses after storms, and winterize water lines to prevent pipes from freezing. Home watch services across the country charge about $50 to $150 per visit, or $150 to $400 a month for a package. Full short-term rental management usually costs more and comes with more rules.
Once he’s marketing, booking, and renting other people’s homes to guests staying no more than 14 days, Tennessee calls that a Vacation Lodging Service. That requires a firm license and a designated agent license, but not a supervising real estate broker. The designated agent license application costs $90, and the agent must complete an 8-hour prelicensing course. Simple caretaking with no booking may fall outside that definition, and the Tennessee Real Estate Commission can say where that line sits.
Cities and counties add their own rules. Knoxville, for one, requires a permit to operate short-term rentals. HOA covenants can limit rentals too. He’ll also need general liability coverage, plus coverage for damage to property he’s looking after but doesn’t own.
How the Earnings Hit Social Security and Medicare
Self-employment tax is 12.4% for Social Security plus 2.9% for Medicare, applied to net earnings from self-employment. On $30,000 of net profit, that’s about $4,240. If he claims Social Security before full retirement age, the earnings limit is $24,480. Net self-employment income counts toward that limit, and the SSA holds back $1 for every $2 over it. At $30,000 net, that’s about $2,760 withheld. Those withheld benefits get credited back as a higher check after full retirement age.
The business also lets him save. A SEP IRA allows contributions of up to 25% of compensation, capped at $72,000 for 2026, and federal law counts net earnings from self-employment as the compensation. Medicare surcharges are based on income from two years earlier. They start above $109,000 for single filers, on top of the standard Part B premium of $202.90 a month. Caretaking income alone probably won’t get there, but a large IRA withdrawal in the same year could.
What the Math Needs, and Finding the First Owner
Say he clears $30,000 a year and pays the self-employment tax. The gap drops to about $21,500, and taking 4% a year, he’d need roughly $538,000 instead of $1.18 million. The 4% figure itself is worth pressure-testing (we made the case for an income-first approach in a free guide here: The 4% Rule Is Broken). If he spends less than the average household, or grows the business past one season, that target keeps falling. The plan depends on his ability to keep doing the work, and the number of years he earns may matter as much as the rate he earns on his savings.
His first client is probably close by. Neighbors on his own cove, marina staff, local cleaning crews, and agents who sell lake homes to out-of-state buyers all know which owners are struggling to keep up. If he has his license and insurance in hand before that first conversation, he can answer the first question every absent owner asks: who’s responsible if something goes wrong.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.