At 71 He’ll Prepay His Funeral for $12,000. If the Money Isn’t Held in a Trust or Insurance Policy, It Can Vanish if the Funeral Home Closes
Writing a $12,000 check at a funeral home feels like the responsible thing to do, but where that money goes next determines whether your family collects on your plan or inherits a very expensive lesson about state law.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
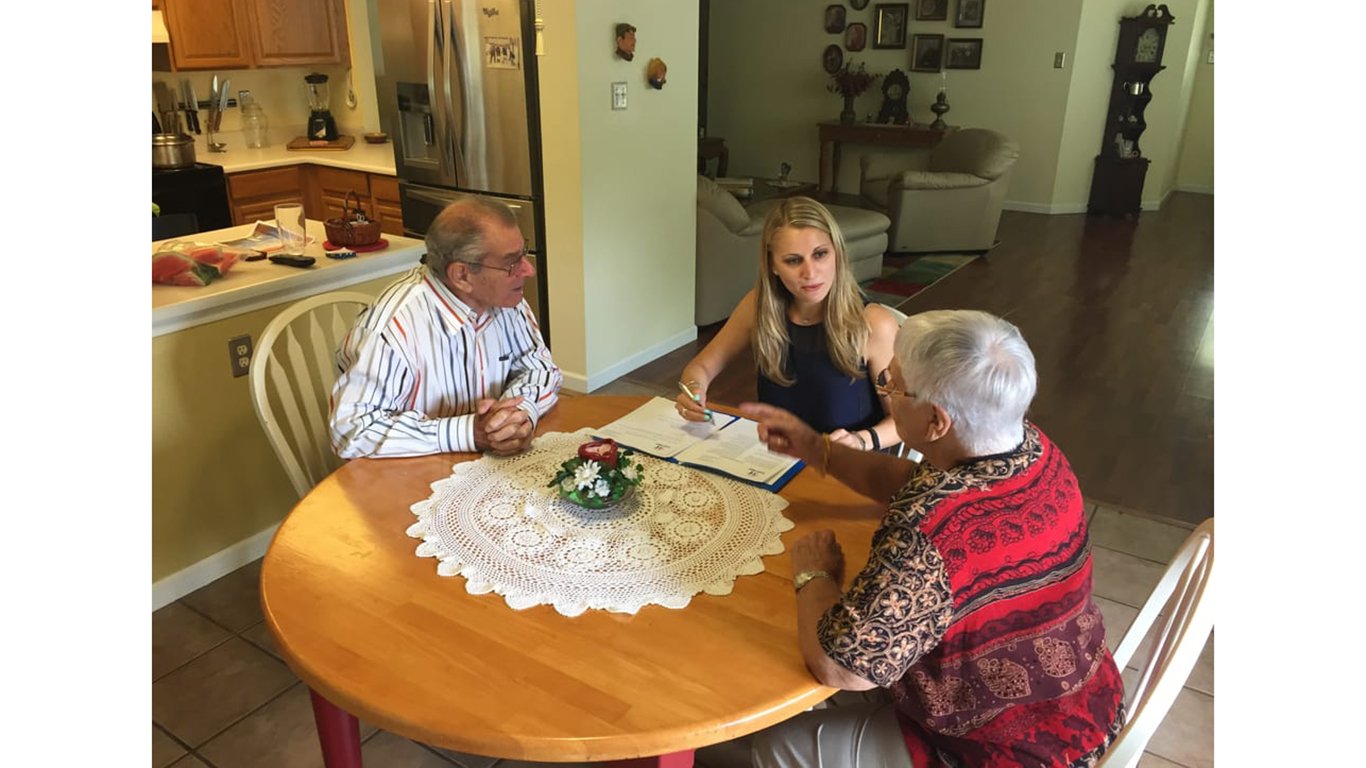
He’s 71, sitting at a funeral home desk with a pen in his hand. He’s picked the casket, the service, and the music. He signs a prepaid contract, writes a $12,000 check, and feels relieved. His kids won’t have to guess what he wanted or come up with cash in the worst week of their lives.
Many people do this, and it’s a kind thing to do. But with a prepaid funeral, the key question is where the check ends up. If it isn’t sitting in a trust or an insurance policy, it can disappear.
What You’re Really Buying With a Preneed Contract
A prepaid contract means paying today for a funeral that happens later, and two sets of rules apply. The Federal Trade Commission’s Funeral Rule covers pricing. But it doesn’t apply to many features of preneed contracts, which fall under state law.
State protections vary widely. Some states require a state-regulated trust. The funeral home must put a percentage of the money into it, or buy a life insurance policy that pays the funeral home when you die. Other states offer buyers little or no effective protection.
How a $12,000 Check Can Go Missing
Elder law publisher ElderLawAnswers reports that consumers lose millions of dollars every year when prepaid funds are misspent. Providers can mismanage or embezzle the money, and some go out of business before the funeral is needed.
Cases like this occur in real life. In Texas, the state Department of Banking found that Austin Peel and Son Funeral Home had illegally sold prepaid funeral benefits. It issued a consent order requiring restitution on November 6, 2018, and got paid in full on February 28, 2019. The department said it would distribute the money to affected customers. Not every case ends that way, since some providers go out of business before the funeral is needed.
There are other weak spots too. If he moves, some plans transfer only at added cost. And even under a price guarantee, costs paid to outside parties like a cemetery or clergy may not be locked in.
Inflation Is the Best Reason to Prepay
Consumer prices rose 3.7% over the past year. If funeral prices kept going up that fast for 10 years, a $12,000 funeral would cost about $17,300. CPI doesn’t track funeral prices specifically, so think of that as a rough guide, but the point still holds that a guaranteed contract shifts that price risk onto the funeral home. A non-guaranteed contract leaves the risk with his family, who may owe the difference later.
That protection is only worth something if the money is still there when you need it.
Five Questions to Get Answered in Writing
- Can I see your General Price List? The Funeral Rule requires funeral homes to give accurate, itemized price information, so he can compare homes and buy only what he wants.
- Where will my money be held? It should go into a trust, an insurance policy, or an escrow account, and he should also ask who keeps the interest the money earns.
- Is this guaranteed or non-guaranteed? Guaranteed means the listed services are covered no matter what they cost later, while non-guaranteed means the payment counts as a credit and his family pays any shortfall.
- Can I cancel, and what refund will I get? Revocable contracts can be canceled. Irrevocable ones generally cannot.
- If I move or die away from home, what happens? He should find out if the contract can move to another funeral home, and what fee applies.
Medicaid Decides Which Version Makes Sense
For a single person, Medicaid caps countable assets at $2,000 before it’ll pay for a nursing home. Prepaid irrevocable funeral arrangements are exempt. A revocable plan, or a savings account set aside “for the funeral,” still counts.
At 71, long-term care is a real possibility. For most people his age, an irrevocable, guaranteed contract funded through a trust or insurance policy is the better choice. It protects the funeral money from Medicaid’s asset count and from going up prices. The downside is that he can’t get the money back if he changes his mind. A prepaid funeral is only one line on a much longer checklist, and the paperwork around beneficiaries, ownership, and trusts is where most estates go sideways (we put the full cleanup checklist in a free guide here).
Two Alternatives Worth Pricing First
A payable-on-death savings account lets him keep control of the money, and the person he names can collect without probate. That works well if he has plenty of other assets, might move, and isn’t worried about Medicaid. The tradeoffs: no locked-in prices, and the account counts toward Medicaid’s limit.
Final expense insurance is a small whole life policy bought to cover end-of-life costs. The payout goes to whoever he names. Medicaid generally exempts a whole life policy only when its total face value is $1,500 or less, so a policy big enough to cover a funeral usually counts through its cash value, unless it’s assigned to an irrevocable funeral contract.
Ask This Before Signing Anything
The biggest mistake is handing over the check with nothing but a receipt. Before he signs, he should ask exactly where the money will be held. Get the name of the trust or insurance company in writing, then call the state agency that oversees prepaid sales to confirm the funeral home follows the rules. If the answer is vague, he should keep the money in a payable-on-death account until he gets a clear answer.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.