Everyone Talks About the Sun Belt. Nobody Talks About the Retirees Who Picked the Pacific Northwest for the Summers
A growing group of retirees is quietly trading the Sun Belt for Oregon and Washington, but the tax codes in those two neighboring states point in almost opposite directions, and earthquake deductibles alone can blow up a carefully built withdrawal…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Most retirees move to Florida, Arizona, and the Carolinas, but a smaller group goes to Oregon and Washington instead, trading Sun Belt heat for cooler summers. IRS migration data shows that many people moving north come from the same states retirees usually move to.
From 2022 to 2023, Washington took in 9,307 tax returns from Texas, 5,803 from Arizona, and 5,333 from Florida. Those counts include working households and retirees. Below is what retirement costs in the Pacific Northwest. How the two states’ tax rules differ, and which risks tend to get left out of the math.
Two Neighboring States With Opposite Tax Codes
Washington doesn’t tax wages or retirement withdrawals today. Its main revenue source is retail sales tax, with a state rate of 6.5% plus a local rate. It also taxes long-term capital gains: 7% on taxable gains up to $1 million and 9.9% above that. The tax applies only after a large annual deduction.
In March 2026, the governor signed a 9.9% tax on annual income above $1 million, set to take effect Jan. 1, 2028. Washington also imposes its own estate tax. The exclusion is $3,000,000 for deaths from July 1, 2026 forward, adjusted annually for inflation, and rates run from 10.0% to 20.0%.
Oregon takes the opposite approach. Oregon has no sales tax, but it imposes an income tax with a top rate of 9.9%. Social Security is exempt, but 401(k) and IRA withdrawals count as taxable income. Under the 8.75% bracket in Oregon’s 2025 schedule, every $10,000 taken out from an IRA adds about $875 in state tax.
That’s why people talk about living in Vancouver, Wash., and doing their shopping in Portland. The savings depend on use tax rules. Use tax is still owed. Washington law does not allow residents to avoid sales tax by crossing the border to Oregon and bringing items home. Since July 2019, Oregonians shopping in Washington have also paid sales tax at the register, with a few exceptions.
Pricing a Vancouver Retirement for Two
Vancouver is used as an example here because it’s close to Portland’s hospitals and follows Washington’s tax rules. Its median sale price was around $494,500 in September 2026. Bend, Ore., another retiree favorite, came in at about $724,606 for the three months ending June 2026.
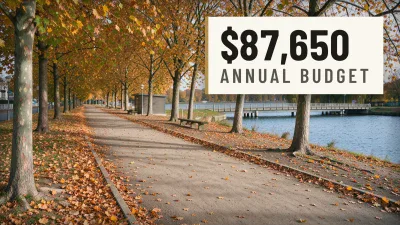
Average U.S. household spending was $81,905 in 2025. Washington’s price index is 107.013, so the adjusted budget comes to about $87,650 a year. That figure already includes healthcare. Medicare Part B runs $202.90 a month per person, or about $4,870 a year for a couple. Premiums rise once joint income passes $218,000.
The average aged couple with both spouses collecting gets $3,208 a month from Social Security, or $38,496 a year. That leaves a gap of about $49,150 for the portfolio to cover. A 4% withdrawal rate would require about $1.23 million. At 3.5%, it’s about $1.4 million (we made the full case for stepping away from the 4% rule, and what to run instead, in a free report). The lower rate gets some support from the Trustees, who project the combined Social Security trust funds will run out in 2034, with 83% of benefits still payable after that. Waiting longer to claim raises the monthly check and reduces the gap.
Earthquake Deductibles Rarely Make the Budget
Most homeowner policies do not cover earthquake damage, and only about 20% of Oregonians have bought separate coverage. Even with a policy, Oregon deductibles are usually 10% or 15% of the insured amount. Insure a home at about Vancouver’s median, and the out-of-pocket cost before coverage pays anything is $49,450 to $74,175. Some households hold that amount as a separate reserve outside the withdrawal plan, such as a Treasury ladder.
There are other trade-offs too. Winters are gray and wet across much of the region. Some summers bring wildfire smoke, and Oregon’s environmental agency runs a dedicated wildfire response program. On the estate side, a $1.4 million portfolio plus a median Vancouver home totals about $1.9 million. That’s under Washington’s exclusion today, but home values and portfolios can grow, and the exclusion only adjusts with inflation.
What the Numbers Add Up To
The figures above assume portfolio returns above inflation over time. Washington does not tax IRA withdrawals. Oregon’s Social Security exemption helps households that rely more heavily on benefits.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.