Bend Has Mountain Trails and No Sales Tax. What It Takes to Retire There at 63 on $1.2 Million

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
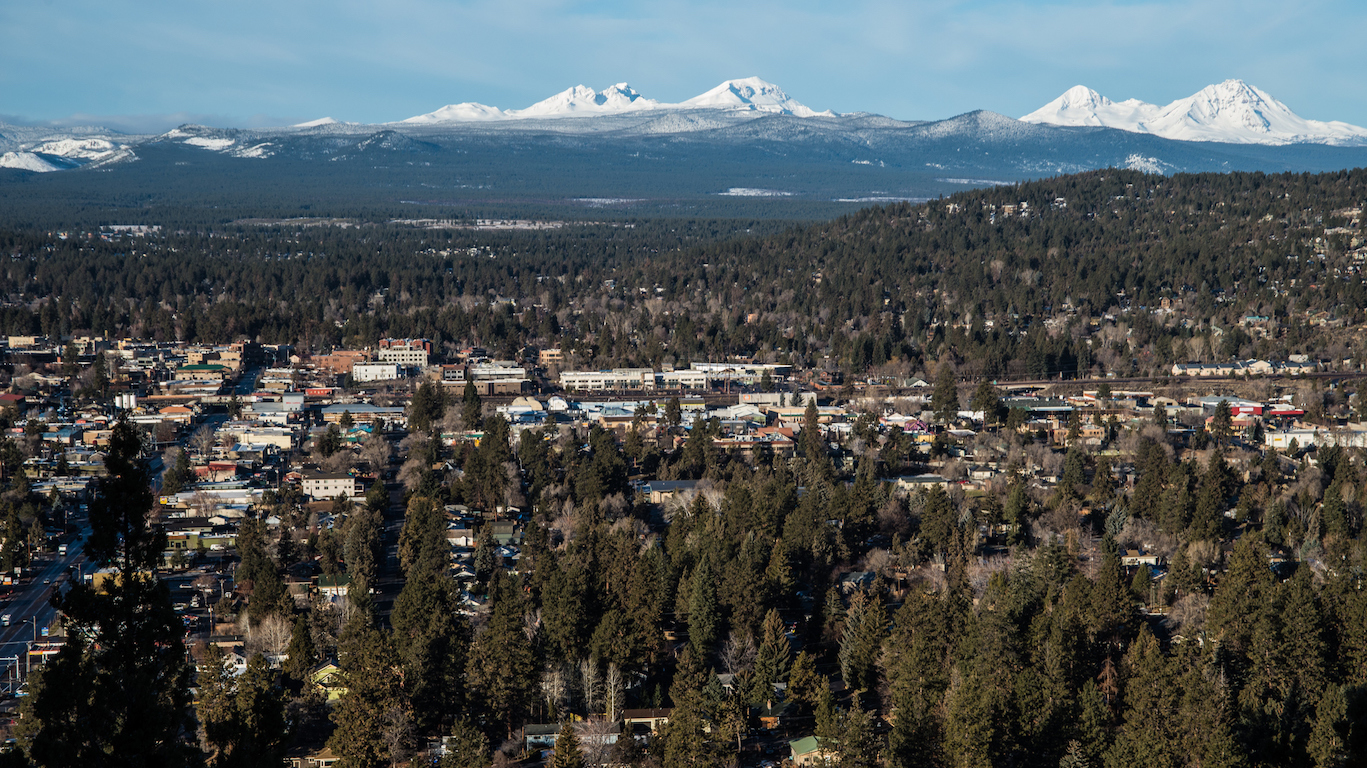
Bend, Oregon, comes up a lot when couples in their early 60s talk about where to retire. Common attractions include the Deschutes River Trail, Mt. Bachelor, and the local breweries, but the real question is whether $1.2 million covers that at 63, two years before Medicare, in a state that taxes most retirement income. The answer depends on a few conditions.
What Bend Delivers and Where It Pinches
The draw is easy to see: the Bend Ale Trail includes over 30 breweries and tasting rooms in seven territories, and the same map lists year-round recreation at Mt. Bachelor and floating the Deschutes River. On the medical side, St. Charles Bend is a full hospital with an Emergency Department open 24 hours.
Housing is the hard part. The median sale price recently held close to $750,000. Federal housing data show Bend prices up 0.65%[1] over the past year and 29.24% over five years, so the market has cooled a bit.
In August, the median price fell 5.7%, and 44.7% of closed sales came with seller concessions. Paying cash for a median house out of the portfolio would sharply reduce it, so the plan below assumes the house is paid for with equity from a home sold somewhere else. The other trade-offs don’t show up on a spreadsheet: summer wildfire smoke, snowy winters and long drives over the Cascades to major airports and some specialists.
No Sales Tax Still Leaves a Big Oregon Tax Bill
Oregon has no state sales tax and fully exempts Social Security benefits. Oregon generally taxes traditional IRA withdrawals and pensions, but qualified Roth withdrawals and certain other income are exempt.
According to the Oregon Department of Revenue, once someone moves to Oregon, “your pension income, along with all other income regardless of source, is taxable in Oregon.”[2]
Traditional IRA and 401(k) withdrawals count as ordinary income, and the brackets run from 4.75% to 9.90%. There’s a retirement income credit, but it depends on age and income[2] and is aimed at low-income senior taxpayers. Couples relying on IRA withdrawals will pay Oregon tax on nearly every dollar they take out.
Turning $1.2 Million Into a Bend Budget
Taking 4% out of the portfolio comes to $48,000 a year. An older couple both collecting Social Security gets $3,208 a month after the 2026 2.8% COLA, which is $38,496 a year. Combined, that totals $86,496. The average U.S. household spent $81,905 in 2025 by comparison. To cover that spending after Social Security, a 4% withdrawal rate calls for about $1,085,225. On that basis, $1.2 million covers an average budget before federal and Oregon taxes on the withdrawals.
Inflation pressures that margin a little more. Prices for households led by someone 62 or older rose 3.9%[3] over the past year, while the 2027 COLA is 3.6%. The gap is small, but it compounds, and it’s one reason we laid out the case against a static 4% withdrawal and the income-first alternative in a free report.
Health insurance from 63 to 65 is another cost to consider. KFF’s 2027 national benchmark silver premium is $704 a month for a 40-year-old, and insurers can charge enrollees in their 60s a lot more because of age rating. KFF also found that marketplace premium payments more likely than not doubled on average in 2026 as enhanced premium tax credits expired, and some states are offering extra ACA premium subsidies in 2027.
24/7 Wall St. has covered those subsidy changes before. Subsidies depend on household modified adjusted gross income: spending existing cash principal does not increase it, but realized brokerage gains, interest, and dividends count and can reduce or eliminate the credit. For 2026, the standard Part B premium is $202.90 a month, and joint-filer income surcharges begin above $218,000 in modified adjusted gross income; the figures will differ when this couple turns 65.
Roth Conversion Timing Can Shift the Oregon Tax Bill
Roth conversion timing affects the tax bill. A Roth conversion moves money from a traditional IRA into a Roth, and the amount converted counts as taxable income that year. Oregon taxes part-year residents on taxable income from Oregon sources while you’re a nonresident, plus your taxable income from all sources while you’re a resident[2]. A conversion done while the couple still lives in a lower-tax state happens outside Oregon’s reach. Once they’re Oregon residents, that same conversion gets taxed at rates up to 9.90%.
Timing also matters for the other programs. Converting in the last working year, while still on employer health coverage, keeps extra income out of marketplace subsidies. Converting at 63 or later raises the income Medicare looks at two years later when setting premiums. For anyone born in 1963, required minimum distributions don’t start until age 75, so balances left in traditional accounts keep growing toward larger required withdrawals that Oregon will tax.
Here’s what the plan looks like in full. The house is paid for with outside equity. The budget remains close to the national average of about $82,000. The portfolio is split between stock index funds and a treasury ladder, with withdrawals around 4% ($48,000 a year).
Social Security comes in near the couple’s average of about $38,500. A cash or taxable account covers two years of marketplace premiums without driving up reported income. Roth conversions done before becoming Oregon residents are taxed by the lower-tax state instead.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.