Why a $900,000 Traditional 401(k) Is Worth About $680,000 to the Kids, and a $900,000 Roth Is Worth All of It
Leaving a traditional 401(k) to your kids sounds straightforward until you factor in their tax brackets, a strict 10-year withdrawal deadline, and the silent cut the IRS takes from every dollar they inherit. The math may surprise you.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Picture a 66-year-old with $900,000 in a traditional 401(k) who has already decided the money goes to the adult children. The open question is whether to leave it alone or convert it to Roth first. That choice can change what the kids keep by six figures.
The question comes up on retirement forums all the time. One user on Reddit’s r/RothIRA gave the usual rule of thumb: “Roth conversions make sense if you anticipate being in a higher tax bracket in the future versus what you’re in today.” When the money is going to heirs, that future bracket is your children’s.
Same $900,000, Two Very Different Checks for Your Heirs
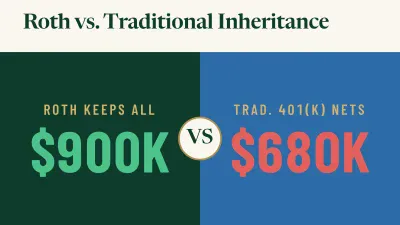
Every dollar an heir takes out from an inherited traditional 401(k) funded entirely with pretax money is taxed as ordinary income on their own return. Assume a 24% effective rate on the whole balance. That sends $216,000 to the IRS and leaves $684,000 for the kids.
A qualified Roth works differently. Withdrawals by beneficiaries are generally free of federal income tax. The full $900,000 comes free of income tax. These figures leave out investment growth. Growth only widens the gap under the assumed tax treatment, because qualified Roth gains are tax-free too.
A 10-Year Deadline Can Push Your Kids Into Higher Brackets
Most adult children have to empty an inherited account by December 31 of the 10th year after the owner’s death. Missing a required distribution can trigger a 25% excise tax on the shortfall, decreased to 10% if corrected in time.
Take a single heir making $150,000 at her career peak. Spreading the inheritance evenly adds $90,000 a year to her income. After the $16,100 standard deduction, her taxable income lands near $223,900.
That is above the 2026 single-filer limit of $201,775, where the 32% bracket begins.
Waiting and taking it all in year 10 is worse. Her taxable income would jump to about $1,033,900, well past the 37% limit.
Converting All at Once Gets Expensive Fast
You owe tax on a conversion in the year you make it. A married couple that converts the whole balance in one year can push hundreds of thousands of dollars into the 35% and 37% brackets. For joint filers in 2026, those start above $512,450 and $768,700 of taxable income.
Medicare adds a second bill. The income-related monthly adjustment amount (IRMAA) generally looks back two years, so a conversion in 2026 can raise your premiums in 2028. Under 2026 Medicare rules, joint income of $750,000 or more triggers the top surcharges of $487 a month for Part B and $91 for Part D, per person.
For a couple, that comes to $13,872 in annual surcharges at 2026 rates. The rates and income thresholds for 2028 have yet to be revealed. The conversion can also make more of your Social Security benefits taxable.
Spread Conversions Across Your Lower-Tax Years
Splitting the conversion across several years can keep more money out of the highest tax brackets. The first Medicare surcharge starts above $218,000 in joint income under 2026 rules, although future thresholds will change. The 22% and 24% federal brackets run up to $403,550 of taxable income for joint filers in 2026.
Leaving the account alone makes sense when your heirs will pay a lower rate than your conversion would cost, as with a child early in their career or in a lower-paid job. Conversions look better when you pay the tax from a taxable brokerage account. That money leaves your estate either way, and the full Roth balance keeps compounding. The calm years between your last paycheck and your first RMD are usually the cheapest time to do this, which is the whole subject of our free Roth conversion guide.
The five-year rule matters too. For a Roth 401(k), the clock starts with your first Roth contribution to that plan. For a Roth IRA, it starts with the first tax year you funded any Roth IRA. If you die before the applicable five years are up, heirs may owe income tax on the earnings, but not on the contributions or converted amounts.
Three Moves to Make Before December 31
- Project your 2026 income and compare it with the current Medicare surcharge thresholds of $218,000 for joint filers and $109,000 for single filers. Your 2026 income will generally determine your 2028 premiums, using thresholds announced closer to that year. Complete any planned 2026 conversion by year-end.
- Ask each child what tax bracket they’re in. If they pay 32% or more, every dollar you convert at 22% to 24% leaves them more after tax.
- If you have no Roth IRA yet, a small conversion this year starts its five-year clock. A conversion made at any point in 2026 starts that clock on January 1 of the same year.
What your kids actually keep depends on their tax brackets, when they withdraw the money and the conversions you make while you’re alive.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.