A Single Retiree’s Standard Deduction Rises to $16,600 in 2027, Before the Extra Breaks for Older Filers
One income line in 2027 does double damage to single retirees: cross it with a big IRA withdrawal or Roth conversion, and you pay a higher tax rate while a $6,000 break starts disappearing. Do you know where it sits?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Single retirees, whether never married, divorced, or widowed, face one key question for 2027: how much income can come in before federal income tax starts? The IRS gave the starting point on November 5, 2026. It set the standard deduction for single filers at $16,600 for tax year 2027. That covers returns filed in 2028.
Two Extra Breaks Stack On Top After 65
The standard deduction is the portion of income the IRS doesn’t tax, and every filer gets it. Single filers who are 65 or older by year-end get two additional deductions.
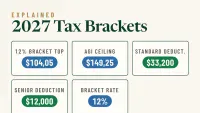
First is the extra standard deduction for age, which increases with inflation each year. In 2027, single filers 65 and older receive an additional $2,100, bringing their total standard deduction to $18,700. The IRS considers you 65 on the day before your 65th birthday.
The 2027 amount is set in Revenue Procedure 2026-35, but it wasn’t one of the headline numbers in the IRS announcement. So check the final form instructions before including a specific figure. The IRS treats you as 65 on the day before your 65th birthday.
Next is the newer senior deduction: $6,000 for each person 65 or older. It applies to tax years that start before January 1, 2029, so 2027 and 2028 are the last two years under current law. For a single filer, it shrinks by 6% of modified adjusted gross income (basically total income) above $75,000. You can claim it whether you itemize or not.
How Much Income Stays Tax-Free Next Year
Add the $16,00 standard deduction, the $2,100 age-based deduction, and the $6,000 senior deduction, and a single retiree 65 or older can generally have up to $24,700 in ordinary income before owing federal income tax. For many retirees, that means a part-time paycheck or small IRA withdrawals are fully covered.
Above that line, the brackets take over. Taxable income just means what’s left after deductions. The first $12,800 of it is taxed at 10%. After that, the rate is 12%.
Once taxable income goes past $52,025, every extra dollar is taxed at 22%.
So how much can come in before leaving the 12% bracket? Including all three deductions, a single retiree can have about $76,627 in adjusted gross income before reaching the 22% bracket, assuming modified adjusted gross income is the same. That’s after accounting for the senior deduction, which starts shrinking once income passes $75,000.
Social Security Runs on a Separate Test
Social Security benefits have their own test. The IRS takes half your benefits and adds all your other income, including tax-exempt interest. Publication 915 goes through the steps. If you’re single and that total stays under $25,000, none of your benefits get taxed.
If you go above that, up to half of your benefits can be taxed. Once you pass $34,000, up to 85% can be taxed. Both lines are written into the law as fixed dollar amounts. So unlike the standard deduction, they don’t go up with inflation.
For a typical retiree, after the 3.6% COLA for 2027, most retired workers collect $2,2170 a month, or $ 26,040 a year. Half of that, $13,020, counts toward the test. That leaves room for $11,980 of other income, like a pension or IRA withdrawals, before any benefits become taxable.
Widows Keep Joint Rates for Only a Short Window
In the year a spouse dies, the survivor can still file a joint return. After that, the qualifying surviving spouse status gives joint rates and the bigger standard deduction for 2 years. To qualify, you need a dependent son, daughter, or stepchild living with you, you have to pay over half the household costs, and you can’t have remarried.
Most widowed retirees don’t have a dependent child at home anymore. So they move straight to the single brackets in the year after their spouse dies. Our related coverage lays out the married-couple numbers they’re leaving behind.
One Number Worth Planning Around in 2027
For a single retiree, it’s $75,000 of modified adjusted gross income. That’s where the senior deduction starts to shrink, and it’s right next to where the 12% bracket runs out. A big IRA withdrawal or Roth conversion that crosses it hits twice: the next dollars get taxed at 22%, and the $6,000 deduction gets smaller.
Staying at or under that line keeps the full break in place for its final two years. The quiet years between a last paycheck and the first required withdrawal are usually the cheapest time to convert, and we sized up that window in a free Roth guide.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.