At 69 She’ll Inherit $300,000 From an Aunt in Italy. There’s No U.S. Tax on It, but Skipping One IRS Form Can Cost Thousands
A notary's letter from Italy promises a life-changing inheritance, and the IRS won't take a dime of it. Yet a quiet piece of paperwork, and a calendar date many heirs never circle, can still turn that windfall into a costly…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The envelope has Italian stamps and a notary’s letterhead. Inside, a letter explains that her late aunt left her a share of the estate. At 69, she reads it twice before it sinks in: $300,000 is coming her way. Inheriting from family abroad raises the same concerns again and again online. On Reddit’s r/personalfinance, one commenter explained it to a nervous heir: “Form 3520 part 4 is for any foreign gift/bequest totaling over $100k value in a year. It doesn’t matter what you do with the asset.”
Why Uncle Sam Won’t Take a Cut
Federal law is short on this point. Gross income “does not include the value of property acquired by gift, bequest, devise, or inheritance” under 26 U.S.C. § 102(a). So she owes no U.S. income tax just for receiving the money.
Once it’s hers, though, what it earns counts. Interest, dividends, and gains after she gets it are taxable under § 102(b)(1). If she inherits stocks or property instead of cash, her cost basis (the starting value used to figure gains) is generally the fair market value on the date of death. If she sells soon after, she may have little or no taxable gain.
A Missed Form Can Cost $75,000
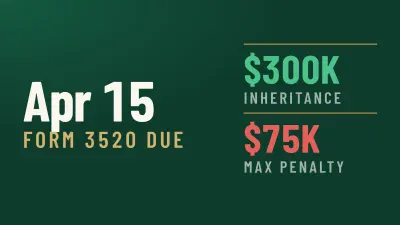
Any U.S. person who receives more than $100,000 from a nonresident alien individual or a foreign estate has to file Form 3520. It’s an information return, used only to tell the IRS the money arrived. It’s due by the 15th day of the 4th month after the end of the taxpayer’s tax year (April 15 for most people), and it gets the same extension as her tax return.
If she skips it, the penalty is 5% of the gift for each month the failure continues, capped at 25%. On her inheritance, that’s $15,000 a month, up to $75,000. The law exempts failures due to “reasonable cause and not due to willful neglect,” but arguing that after the fact is a headache she can avoid.
If the Money Sits in an Italian Account First
If she receives the inheritance into an Italian bank account she owns, that can trigger two additional reporting requirements. If the money remains in her aunt’s estate account, different rules apply. She may have a Form 8938 obligation for her interest in the foreign estate, but an FBAR isn’t automatically required.
- FBAR (FinCEN Form 114): Required if her foreign accounts together top $10,000 at any time during the calendar year. It’s filed with the Treasury, separate from her tax return, and due April 15, with an automatic extension to Oct 15.
- Form 8938: Attached to her tax return. For a single filer living in the U.S., it applies above $50,000 on the last day of the year or $75,000 at any time. For married couples filing jointly, it’s $100,000 on the last day or $150,000 at any time.
A $300,000 balance tops out on each of those lines. And moving it home later doesn’t eliminate the Form 3520 duty. As one r/tax commenter put it: “It is reportable when received irrespective of when it is transferred to the US.”
Italy Settles Its Side Before the Wire Leaves
Italy may charge its own inheritance tax, and that’s handled through the estate and the Italian notary. A tax pro who works in both countries is worth paying here because the Italian paperwork, any property sale, and her U.S. forms all have to line up.
Getting the Money Home Without Leaking Cash
Most heirs bring it back by international wire. The hidden cost is usually the exchange rate, since banks often build a markup into the euro-to-dollar conversion on top of a flat wire fee. She should get a quote from her bank and from a dedicated transfer service before agreeing to anything.
Her U.S. bank may ask where a large incoming wire came from. That’s routine. Keeping the notary’s letter and estate documents handy makes it quick. One Medicare wrinkle: the interest the inheritance earns counts as income. Part B premiums start rising for singles above $109,000 and joint filers above $218,000, from a standard $202.90 a month. Most heirs this size stay under those lines, but anyone already close should check.
Where $300,000 Can Sit Safely
FDIC coverage is $250,000 per depositor, per insured bank, for each account ownership category. Dropping the whole amount into one bank in her name alone leaves part of it uninsured. Splitting it between two banks fixes that. Treasury bills and CD ladders are other easy places to park it while she decides on a long-term plan, and our guides on T-bills, CDs and FDIC limits cover each in more detail.
Put One Date on the Calendar Now
If the money arrives in 2026, Form 3520 is due April 15, 2027, or later only if she extends her tax return. That’s the date that matters most. A frequent mistake is assuming that no tax means no paperwork. Filing the form takes the $75,000 risk off the table; she should also keep the estate documents and let the money sit somewhere secure while she makes her plan.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.