How Much Do You Really Need Invested to Replace a $175,000 Salary With Dividends?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The quick math in a situation like this one is relatively common. If you have a married earner making $175,000 a year, you usually divide the salary by a dividend yield to get the target. However, that answer could also be too high.
Before your paycheck reaches your account, income tax and payroll tax come out, so the income you actually need to replace is smaller. Prices also rise every year, so the target keeps moving, and we’ve run this math for other salaries before. This version works through one seven-holding portfolio using prices pulled in early November 2026.
Three Numbers Behind the Real Answer
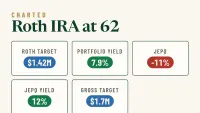
Yield is best known as a year’s payouts divided by the share price. Weighted by position size, the holdings here pay roughly 6.3%. To replace the full gross salary, you’d need roughly $2.78 million.
Take-home pay reduces the target. A married couple filing jointly gets a $32,200 standard deduction in 2026, which leaves $142,800 of taxable income. Run that through the 10%, 12%, and 22% brackets, and federal income tax comes to $20,840. Social Security takes 6.2%, and Medicare takes 1.45%, which adds up to about $13,388. That leaves take-home pay near $140,800, and replacing it takes roughly $2.24 million at a 6.3% yield before taxes on portfolio income. The actual amount needed would be higher after accounting for taxes on dividends and partnership income.
Separately, state taxes vary. Your dividends also get taxed: qualified dividends get 0%, 15%, or 20% rates, but several holdings here pay income that doesn’t qualify.
Inflation sets the third number, especially when you factor in that Consumer prices rose about 3.7% from September 2025 to September 2026. On $175,000, that means you’d need roughly $6,500 more next year just to stay even.
iShares International Select Dividend ETF
iShares International Select Dividend ETF (CBOE:IDV) holds high-dividend stocks from developed markets outside the U.S., with a heavy tilt toward Europe. The fund has a 20% weight, yields about 4.9%, and supplies 16% of the income. Payouts swing a lot: $1.10 in June, then $0.53 in September. Foreign governments withhold tax on dividends, though funds like this one can pass that tax through so you can claim a credit or deduction in some cases.
FT Vest S&P 500 Dividend Aristocrats Target Income ETF
FT Vest S&P 500 Dividend Aristocrats Target Income ETF (CBOE:KNG) owns companies with long records of raising their dividends. It also sells covered calls, which means it takes in option premiums and gives up some upside in exchange. It carries a 15% weight, yields about 8.0%, and supplies 19% of the income. Monthly payouts stayed between $0.34 and $0.37 in 2026.
Rexford Industrial Realty
Rexford Industrial Realty (NYSE:REXR) is a real estate investment trust that owns 384 industrial properties totaling approximately 44.5 million square feet as of September 30, 2026. It carries a 15% weight, yields 4.5%, and supplies 11% of the income. The quarterly dividend rose from $0.12 in 2014 to $0.435. Its latest raise was only 1.2%, which is below the inflation rate.
Sixth Street Specialty Lending
Sixth Street Specialty Lending (NYSE:TSLX), a business development company, loans to midsize businesses. It carries a 15% weight, yields 9.4%, and supplies the most income of any holding: 22%. Lower interest rates pushed the base dividend down from $0.46 to $0.42. Extra supplemental payouts fell to $0.01, so plan your budget on the base dividend alone.
Exxon Mobil
Exxon Mobil (NYSE:XOM | XOM Price Prediction) has 15% of the money but yields just 2.6%, so it supplies only 6% of the income. Its job is dividend growth. Exxon has raised its dividend for 44 consecutive years, and its latest raise to $1.07 works out to about 3.9%, a little ahead of inflation.
MPLX
MPLX (NYSE:MPLX) is a partnership that owns pipelines. It carries a 15% weight, yields 8.5%, and supplies 20% of the income. It raised its payout by 12.5% for the third year in a row. Owners get a K-1 tax form instead of a 1099. IRAs remain subject to unrelated business income tax under 26 U.S.C. § 408(e)(1), so keeping the units in a retirement account can still trigger a tax bill.
Invesco Preferred ETF
Invesco Preferred ETF (NYSEARCA:PGX) holds preferred stock, which pays fixed dividends that come ahead of common shareholders. The fund has a 5% weight, yields 7.3%, and supplies 6% of the income. Because the payouts are fixed, prices fall when rates rise. With the 10-year Treasury at 4.84%, shares fell 7% over the past year.
Which Number Should Drive Your Plan
When all is said and done, replacing the gross salary takes about $2.78 million, while replacing take-home pay takes about $2.24 million. The income also has to grow about 3.7% a year. For most couples, take-home pay is the number that matters, because it’s what you actually live on.
Once a year, compare how much of your portfolio’s income grew against the latest CPI reading. Reinvesting some dividends can help future income keep pace with inflation, but payouts aren’t guaranteed, and reinvesting means less cash available to spend. A $2.24 million portfolio yielding 6.3% would generate roughly $140,800 annually before taxes, though maintaining that income over time depends on dividend stability and growth (we laid out the full mix, payment calendar, and withdrawal order in a free guide to building paycheck-style income).
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.