A Couple in Their Early 60s Living on a $60,000 Pension Has $77,250 of Room Left in the 12% Bracket in 2027. That’s Their Roth Conversion Number

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A married couple with a $60,000 pension and no other income has one Roth conversion figure to determine for 2027: how much pre-tax money to move before income exceeds past the 12% bracket. Converted amounts are generally taxed in the year of the conversion (IRS Publication 590-A), so the 2027 room closes on December 31, 2027.
How a $60,000 Pension Leaves $77,250 in the 12% Bracket
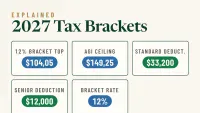
For 2027, the joint standard deduction is $33,200. Subtracting it from the $60,000 pension leaves $26,800 of taxable income. The 12% bracket ends at $104,050 for couples filing jointly, which leaves $77,250 of room ($104,050 minus $26,800).
The pension already uses the full 10% bracket, which ends at $25,600 for couples filing jointly in 2027. Every converted dollar up to the limit is therefore taxed at 12%.
Assumptions: tax year 2027, joint return for a married couple, both spouses under 65, $60,000 fully taxable pension, no Social Security and no other income, standard deduction, conversion tax paid from outside the account, federal income tax only (state income tax varies).
| 2027 item | No conversion | Convert $77,250 |
|---|---|---|
| Pension | $60,000 | $60,000 |
| Roth conversion | $0 | $77,250 |
| Total income | $60,000 | $137,250 |
| Standard deduction | $33,200 | $33,200 |
| Taxable income | $26,800 | $104,050 |
| Federal income tax | $2,704 | $11,974 |
Converting the full amount adds $9,270 of 2027 federal tax. A dollar converted past $104,050 of taxable income moves into the 22% bracket (2027 IRS rate schedule).
TSP Holders Can Convert Without Leaving the Plan
Since January 2026, a Roth in-plan conversion has let participants move money from the traditional balance to the Roth balance inside their TSP account (tsp.gov)[1]. A 401(k) or traditional IRA balance can also go to a Roth IRA, and the conversion adds to gross income (26 U.S.C. § 408A(d)(3)(A)(i))[2].
Either path means the same 2027 tax bill. The trade-offs are practical: staying in the TSP keeps its fund selection and costs, while the Roth option offers different investment and withdrawal rules. Neither Roth IRAs nor designated Roth accounts require lifetime distributions for the owner (IRS RMD FAQs; 26 U.S.C. § 402A(d)(5)).
Four Events That Change the $77,250
- Taking Social Security. Up to 85%[3] of benefits can become taxable (26 U.S.C. § 86(a)(2)), and each taxable benefit dollar fills bracket space a conversion would otherwise use. Benefits also rise with the 3.6% 2027 COLA.
- Turning 65. The extra standard deduction amounts for older filers, including the senior deduction added by the Working Families Tax Cuts, lift the deduction and extend the room (IRS).
- IRMAA. Medicare’s income-related monthly adjustment amount sets Part B and Part D surcharges using income from two years earlier (lookback). In 2027, joint filers at or below $224,000[4] pay the standard $209.40 monthly Part B premium. The $137,250 total here falls under that line, though the thresholds for the premium year a 2027 conversion affects have not yet been published.
- Paying the tax. The IRS notes converters may need to raise withholding or make estimated payments (Publication 590-A). Paying the $9,270 from savings outside the plan lets the full $77,250 reach the Roth side. Tax withheld from the conversion itself is still taxed but never reaches the Roth balance.
2026 Trustees Report Projects 83% of Benefits Payable After 2034
The 2026[5] Trustees Report projects the combined Social Security trust funds will be depleted in 2034, with 83% of scheduled benefits payable later. An aged couple receiving the SSA’s estimated average of $3,208 a month would get $2,662.64 at that level. A smaller benefit would put less taxable Social Security into later returns.
RMDs at Age 75 Close the Conversion Years
Anyone born on or after January 1, 1960, which covers a couple in their early 60s in 2027, starts required minimum distributions at 75 (26 U.S.C. § 401(a)(9)(C)(v)(II)). The amount due for a given year cannot be converted (Publication 590-A), and any shortfall carries a 25% excise tax (26 U.S.C. § 4974(a)). Each year before then brings a new bracket limit.
The first deadline is December 31, 2027. A conversion completed by that date, whether through a TSP Roth in-plan conversion or a rollover into a Roth account, counts against the $77,250 of 2027 room. Bracket space left unused that year does not carry into 2028.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)