What It Takes to Retire in Coeur d’Alene, Idaho, at 63 on $900,000, Where the Lake Is the Main Attraction

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
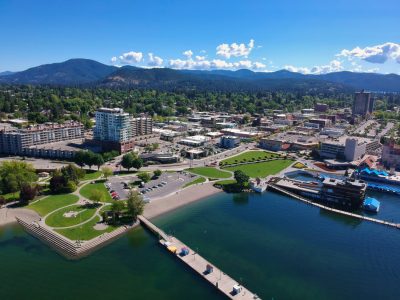
Can a 63-year-old afford to retire in Coeur d’Alene, Idaho? The follow-up question is whether $900,000 in savings can pay for it when Medicare is still two years away. For a couple who already owns a home outright, the numbers seem feasible, though health insurance before Medicare accounts for much of the budget uncertainty.
What a Lakeside Budget Costs Before Medicare
National spending data is a reasonable place to start. The average U.S. household spent $81,905 in 2025. Idaho’s cost-of-living index is 95.494, where 100 is the national average. Scaling the national figure by that index gives a working budget of about $78,200 a year. That’s a statewide number, and Coeur d’Alene falls on the pricier end.
The median listing price in the 83815 ZIP code is about $590,000. Kootenai County’s homeowner exemption is capped at the smaller of $125,000 or 50% of the property’s value. The actual tax bill depends on which school, fire, and highway districts a property falls in (Kootenai County levy data). Paying for a house that size out of the $900,000 wouldn’t leave enough to live on, so the math below assumes the home is already paid for.
How $900,000 and Social Security Close the Gap
A 4% withdrawal from $900,000 produces $36,000 a year (we made the case against leaning on that old 4% figure, and what to run instead, in a free guide: here). An aged couple who are both receiving benefits can expect an average benefit of $3,355 a month[1] after the 3.6% COLA for 2027. That works out to $40,260 a year. Together, the two come to $76,260, about $1,954 short of the Idaho-adjusted budget. A small trim to travel or dining covers that.
The harder years are 63 and 64. Without those benefits, the portfolio would have to cover the whole budget, which means a withdrawal rate near 8.7%. Claiming at 63 locks in a smaller check for good. Some couples in this spot set aside a cash reserve or a short Treasury ladder for the bridge years and start benefits later.
Idaho Taxes Go Easy on Social Security, Less So on IRAs
Idaho deducts any Social Security that’s included in federal income (Idaho Code § 63-3022(l))[2]. Joint filers pay a flat 5.3% of taxable income over $5,000[3], and that rate applies to traditional IRA and 401(k) withdrawals. Idaho’s retirement benefits deduction is narrow. It covers federal civil service and foreign service annuities, certain Idaho firefighter and police pensions starting at age 65, and military retirement at 62 (Idaho Code § 63-3022A(1))[4]. Sales tax is 6%, and residents can take a $155 grocery credit per person (Idaho State Tax Commission).
The Property Tax Reduction program cuts the bill by $250 to $1,500. Its income limit is the greater of $37,000 per household or 185% of the federal poverty guideline for two[5]. Homes assessed above the greater of $400,000 or 200% of the county median[5] get sent to the deferral program instead, and that takes a lot of lake-area houses out of the running. The same state rules apply on the Treasure Valley side, as covered in our earlier piece on retiring to Boise at 62 on $900,000.
Lake Days, Ski Days and Smoke Days
Silver Mountain in Kellogg is about thirty minutes from town, and five ski resorts sit within 90 minutes. Spokane, just over the Washington line, has the nearest major airport and a bigger hospital network, and winters bring real snow while summers bring tourist crowds on the lake and downtown. Wildfire smoke shows up most often in late summer, and air quality across the Pacific Northwest was rated poor in early September 2025. The 83815 median listing is down 1.65% from a year earlier.
Why Health Insurance Before Medicare Decides It
The enhanced ACA subsidies ran out at the end of 2025, and the 400% of poverty ceiling is back (GenerationHealth). For a two-person household buying 2027 coverage, that line is about $86,560 of modified adjusted gross income. Below it, a benchmark plan costs up to 10.22% of income. Just under the line, that’s about $8,846 a year, or roughly $737 a month for the couple. Above that line, the credit is no longer available.
In Kootenai County, the cheapest silver plan for a 30-year-old costs $476.40 a month before subsidies in 2027, up 11% from 2026. Federal rules allow age-based pricing. Insurance companies can charge older adults up to three times what younger adults pay, so two 63-year-olds paying full price would owe several times the subsidized amount. Once Medicare starts, the standard Part B premium is $202.90[6] per person per month.
Every dollar taken out of a traditional IRA counts toward that $86,560. So does Social Security, if you take it early. Paying for ages 63 and 64 from cash, Roth money, or the cost basis in investments held outside retirement accounts keeps that income figure low. One combination of these figures is a 4% withdrawal, Social Security delayed to at least 65, roughly $78,000 a year in spending, about $36,000 from the portfolio and about $40,000 from Social Security, with Idaho tax owed only on the IRA withdrawals. Until Medicare kicks in, health coverage remains a large variable for a Coeur d’Alene retirement at 63 on $900,000.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.