For 20 Years, 60% of Her $2,000 Annuity Check Was Tax-Free. The Month After She Turned 85, the IRS Began Taxing Every Dollar

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
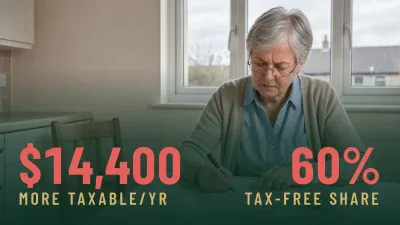
A retiree who turns after-tax savings into a lifetime annuity gets a tax break that can feel permanent: part of every check comes back tax-free. For contracts with an annuity starting date after Dec. 31, 1986[1], the federal tax code sets a limit on that break. Once the buyer has recovered her original cost, every dollar of every later check counts as taxable income. The switch happens the month after she turns 85. Any retiree considering an immediate annuity should know where that cutoff falls before signing the contract.
How One $2,000 Check Got Split in Two
Take a hypothetical retired school administrator. At 65, she moves $288,000 of after-tax (nonqualified) savings into a single premium immediate annuity. It pays her $2,000 a month for life. Under 26 U.S.C. § 72(b)(1)[1], the part of each payment she can leave out of gross income is the same share of the payment that her investment in the contract is of the contract’s expected return.
Expected return comes from IRS actuarial tables in 26 CFR 1.72-9[2]. The Treasury’s regulations direct buyers to Tables V through VIII when the investment went in after June 1986. The IRS’s own worked example in Publication 939 uses a multiple of 20.0 at age 65.
Hypothetical example:
- Expected return: $2,000 x 12 x 20.0 = $480,000
- Exclusion ratio: $288,000 / $480,000 = 60%
- Tax-free part of each check: $1,200
- Taxable part of each check: $800, or $9,600 a year
The IRS describes the split this way: each payment consists of a return of cost and taxable income “until the net cost of the contract is fully recovered.”
Why Payment Number 241 Is Fully Taxable
The cutoff comes from 26 U.S.C. § 72(b)(2)[1]. That paragraph says the excluded portion of any annuity payment “shall not exceed the unrecovered investment in the contract immediately before the receipt of such amount.” Section 72(b)(4)[1] defines unrecovered investment as the original investment minus everything already excluded from income.
Dividing $288,000 by $1,200 of tax-free money per check works out to 240 payments, or 20 years. Her last partly tax-free check arrives in the month she turns 85. The next one is fully taxable, and her annual taxable income from the annuity grows by $14,400. The legal trigger is that she outlived the table: the 20.0 multiple assumed about 20 years of payments, and her basis ran out on schedule (this is one of several quiet IRS rules that can drain six figures from a retirement plan, and we detailed the rest of them in a free guide here).
That leaves a long fully taxable period for anyone who keeps going. The IRS Single Life Table used for required minimum distributions shows 8.1 more years of life expectancy at 85. That table is a different one from the annuity tables used to set the exclusion ratio. It still gives a rough idea of how many fully taxable years a healthy 85-year-old might face.
What Happens If She Dies Before Recovering Her Cost
The rule works in both directions. If payments stop because the annuitant dies while some of her investment is still unrecovered, Section 72(b)(3)(A)[1] lets the unrecovered amount be taken as a deduction on her final tax return. So the total amount that comes back tax-free is limited at her cost, whether she lives a short time or a long one.
Other Tax Rules Retirees Tend to Miss
- Raises are taxable. The tax-free dollar amount is fixed at the annuity starting date. Under IRS guidance, “All increases in the installment payments are fully taxable.”
- Net investment income tax. Payments from a nonqualified annuity count as net investment income when figuring the NIIT.
- Nonqualified buyers must use the General Rule. Annuities paid under a nonqualified plan must use the General Rule rather than the Simplified Method.
- Qualified money works differently. IRA distributions are taxed “in the manner provided under section 72”[3]. A pre-tax IRA usually is clear of after-tax costs, so an annuity bought with that money typically pays fully taxable income from the first check, and it also falls under the RMD rules that Treasury is still finalizing.
Run This Decision Framework Before You Annuitize
The exclusion ratio gives the most tax relief in the early years, which is when many retirees also have other income coming in. The questions below help show whether that timing fits your plan.
- Map the recovery date. Divide your cost by the tax-free part of each payment, or ask the insurer for the projected date. Put that year in your retirement income plan.
- Model the jump in income. Higher taxable income later in life can make more of your Social Security benefits taxable and can push up income-based Medicare premiums. Run those numbers for the years after your cost is recovered, not only for year one.
- Compare the options. Interest from a CD or Treasury ladder is taxed every year, with no exclusion. If you delay Social Security instead, you get a bigger inflation-adjusted benefit with its own tax rules. Compare each option’s after-tax income at 70, 80 and 90.
- Know what supports the guarantee. Lifetime payments depend on whether the insurer can actually pay them. State guaranty associations offer a backstop, but each state sets different caps, so check yours.
- Consider who it fits. Buyers with after-tax savings who expect to live a long time and want a floor of income get the most out of the guarantee. They also face the longest period of fully taxable checks. Buyers in poor health get less income, though the final-return deduction gives back some of the tax benefit.
Keep an Eye on These Items
Annuity owners should check their annual tax statements against their own records of unrecovered investment, because the tax-free amount should drop to zero exactly when the cost is used up. The IRS revised Publication 939 in December 2025, and it remains the main worksheet guide. Owners of annuities held inside IRAs should also follow Treasury’s final RMD regulations. Under Announcement 2026-7, those rules will apply starting in a distribution year that begins no earlier than six months after publication.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.