The “Buffer” on His $400,000 Annuity Covered the First 10% of Losses. The Market Fell 25%, and the Other $60,000 Was His

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Market volatility is climbing again. The CBOE Volatility Index closed at 22.91[1] on November 16, 2026, up 18.7% from the prior session. Readings between 20 and 30[1] signal higher uncertainty, and the index reached 31.05 on March 27, 2026. Some retirees moved savings into a registered index-linked annuity (RILA) because it promised downside protection, only to find out in a drawdown exactly how far that “buffer” reaches.
How a 10% Buffer Splits a 25% Loss
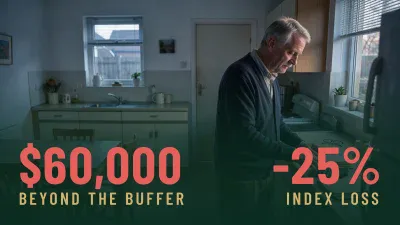
Hypothetical example: A retired engineer puts $400,000 of taxable savings into a RILA tied to a stock index, with a 10% buffer over a multiyear term. The insurance company covers the first 10% of index losses at the end of the term. He covers everything beyond that.
Say the index ends the term down 25%. Without any protection, he would lose $100,000. The buffer covers $40,000 of that. The remaining $60,000 is his loss, so the contract is worth $340,000.
Many buyers hear “protection” and picture a floor. A floor works the other way around. The owner takes losses up to a set level, and the insurance company covers anything beyond it. With a 10% floor on the same contract, his maximum loss would have been $40,000, however far the index fell. Buffers work best in mild or moderate declines. Floors work best in severe ones. Insurers price each design differently, and that pricing shows up as how much upside you get.
What the Buffer Costs You in Upside
The insurance company funds the buffer by limiting your gains. That usually comes through a cap, a participation rate, or both. The insurance company sets these terms and can reset them each time a new term begins. Many contracts credit returns based on a price-return index, which leaves out dividends.
If you surrender early, surrender charges apply. Money taken out before a term ends is valued using an interim formula, which can produce a lower figure than the buffer math suggests. Commissions also influence which designs get pitched.
RILAs are registered securities and are sold with a prospectus, which is where the buffer, cap and surrender terms are detailed. The U.S. SEC has worked on a registration form designed specifically for index-linked annuities. The buffer is a contractual promise, and only the insurance company’s financial strength backs it up. State guaranty funds serve as a backstop if an insurer fails, but coverage limits and terms vary by state. Check your own state’s association.
Tax Rules That Kick In After a Loss
In a nonqualified contract, earnings grow tax-deferred, and the taxable part of any distribution is taxed as ordinary income. Under IRS Publication 575 (2025), money taken out before the annuity starting date comes from earnings first and cost second. In the hypothetical, the contract is worth less than the $400,000 he paid, so a withdrawal would merely return the cost. If he surrenders the whole contract, the proceeds are tax-free up to his unrecovered cost. Nonqualified annuity income also counts toward the Net Investment Income Tax.
Owners younger than 59½[2] owe an extra 10% tax on the taxable portion of a distribution under 26 U.S.C. § 72(q)(1). You can swap one annuity for another without recognizing gain under 26 U.S.C. § 1035(a)(3)[3]. But that replacement contract may carry its own surrender schedule.
RILAs held inside a standard individual retirement account are subject to required minimum distribution rules. An owner calculates each IRA’s RMD separately but “can withdraw the total amount from one or more of the IRAs”. That flexibility lets an owner take the RMD from another account instead of selling a buffered contract partway through a term at a low interim value.
Who a Buffered Annuity Fits, and Who Should Pause
- Time horizon: The buffer applies at the end of the term. Buyers who can leave the money in for the full term get the protection they paid for.
- Loss tolerance: Run the contract through 25% and 35% declines. If your income plan hinges on the amount left after the buffer, a floor design or a principal-protected product may fit better.
- Alternatives: A CD or Treasury ladder gives up equity upside in exchange for guaranteed principal safety. A buffered annuity accepts some loss in exchange for limited stock-market participation.
- Renewal terms: Find out how the insurance company sets caps on later terms and how much notice you get before a renewal.
- Insurance company strength: Every guarantee depends on the issuer staying solvent.
Buyers who need easy access to their money, or who would be forced to sell during a decline, run the most risk of locking in losses beyond the buffer.
Signals to Track Before Your Term Renews
Households are already nervous. University of Michigan consumer sentiment came in at 48.1[4] in September 2026, below the 60 mark the index associates with recessionary levels. Insurers base caps on the cost of hedging, and volatility affects that cost, so renewal terms can shift after turbulent periods. Before a term rolls over, read the renewal notice. Compare the new cap and buffer to the original ones, and check how much of the term’s loss falls on you. In the hypothetical, that share came to $60,000.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.