An Umbrella Girl Hummel Sold for $800 in 2000. Auction Houses Now Get About $100, and the Kids Who Inherit the Collection Get No Tax Break for the Drop

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
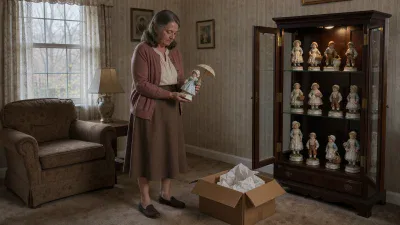
A retired mother spent decades filling a lit curio cabinet with Hummel figurines. Her favorite was an Umbrella Girl, a piece that sold for $800 in 2000. Amid the slide Kovels documented, auction houses now get about $100 for the same figurine. When she dies, her adult children inherit porcelain worth a fraction of what she paid, and federal tax law gives no one a deduction for the lost value.
She and her children are a composite family, but the price drop is real and the tax rules come straight from the Internal Revenue Code, and many families are settling estates full of mid-century collectibles, so the timing matters. Heirs who understand the rules early can avoid overpaying for appraisals they don’t need and holding out for prices that won’t return.
Why Hummel Prices Collapsed
Kovels covered the slide in its “What NOT to Collect” update, published in August 2018. As of that date, Kovels reported that Hummels had once sold for hundreds of dollars each, the generation that collected them was downsizing, and younger buyers showed little interest. Kovels also found a few Hummel figurines listed on eBay (NASDAQ:EBAY | EBAY Price Prediction) for $1[1] as of August 2018.
Kovels named two exceptions in that same update: rare Hummels more than 12 inches[1] tall, or made before 1949, still sold in the hundreds of dollars. Most cabinets hold the smaller, later pieces that were mass-produced for gift shops and collector clubs.
Longaberger baskets followed the same path. Kovels reported in August 2018 that some baskets sold for more than $100[1] in the 1990s, while most, including limited editions that once commanded high prices, sold for less than $20.
No Deduction for the Original Collector
The mother never had a tax write-off coming, even if she had sold the Umbrella Girl herself at today’s price. Under 26 U.S.C. § 165(c)[2], loss deductions face strict limits. An individual’s loss deduction is limited to losses “incurred in a trade or business,” losses “incurred in any transaction entered into for profit,” and losses of other property only when they “arise from fire, storm, shipwreck, or other casualty, or from theft.” Figurines bought to display at home fit neither of the first two categories, so a market decline on them generally produces no deductible loss.
The casualty path is narrow. Under 26 U.S.C. § 165(h)(1)[2], each casualty or theft loss counts only to the extent it exceeds $100[2]. Section 165(h)(2)(A)(ii)[2] then allows net personal casualty losses only to the extent they exceed 10% of adjusted gross income. A shelf of figurines that loses value over time never qualifies for either rule.
Heirs Inherit Today’s Price as Their Basis
The children’s basis resets at death. Under 26 U.S.C. § 1014(a)(1)[3], the basis of property acquired from a decedent is the value of the property on the date of the decedent’s death. If the Umbrella Girl appraises near the current auction level, that lower figure becomes the heirs’ starting point. A sale at that price produces no gain and no loss, and the gap from the original purchase price drops out of the tax system entirely.
The same rule helps when a piece has gone up in value. A rare, oversized or pre-1949 figurine passes to heirs at its value when the parent died, so the gain built up during the parent’s lifetime is never taxed. IRS Publication 550 adds that when inherited property that is a capital asset is sold, the gain or loss “is considered long term, regardless of how long you held the property.”
Documentation depends on the size of the estate. Publication 550 says that if the executor provides a Schedule A (Form 8971), heirs use the final estate tax value reported there. If no Form 706 was filed, heirs use the appraised value on the date of death for state inheritance or transmission taxes. Very few families file Form 706. IRS data show 7,195[4] estate tax returns were filed in 2024, and 1,296 of them reported art, totaling $2,718,935,000. For most families with a figurine cabinet, a date-of-death appraisal is the evidence that counts (the appraisal sits alongside the beneficiary forms, titling, and trust paperwork we laid out in a free estate checklist, here).
Steps to Take Before Emptying the Cabinet
- Get a realistic appraisal close to the date of death. Base it on recent sale results for similar pieces. That figure becomes the heirs’ basis under Section 1014.
- Pull out the exceptions first. Check for pieces that Kovels said still held value as of August 2018: figurines taller than 12 inches[1] or made before 1949. Those deserve individual attention. Common pieces can be grouped together.
- Decide what to keep and what to sell. Heirs who keep a figurine for sentimental reasons give up nothing for tax purposes, since selling at the value set when the owner died produces no gain to report. Selling the rest in groups saves families from paying commissions and spending time on pieces that may bring only a few dollars each.
- Know the paperwork rules for donations. Under 26 U.S.C. § 170(f)(11)(B)[5], a donor claiming a deduction of more than $500[5] must include a description of the property with the return. Under § 170(f)(11)(C)[5], a deduction of more than $5,000 requires a qualified appraisal. At current prices, most figurine donations stay well below the appraisal threshold.
- Keep the records together. Store the appraisal, any Schedule A (Form 8971) and sale receipts in one file so each heir can support the basis used on their return.
Kovels documented the Hummel decline, and the Umbrella Girl math is settled: $800 then, about $100 now, and no deduction anywhere along the way. The decisions that still matter are how to value the collection at death, which pieces to keep, and how to document any donation.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)