She’ll Inherit Her Mother’s $240,000 IRA at 57 and Be Told She Has Ten Years to Empty It. Because Her Mother Was Already Taking RMDs, the IRS Will Also Want a Withdrawal in Each One of Them

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A daughter who inherits her mother’s IRA often focuses on the ten-year deadline. She is 57, the account holds $240,000, and her plan is simple: leave the money invested, let it grow, and deal with the taxes when year ten arrives. That plan can cost her money.
A parent who had already started required minimum distributions (RMDs) passes that schedule on to the heir. What follows covers how the yearly withdrawals work, how the amount is figured, what a missed one costs, and the year-of-death withdrawal that is easy to overlook.
Why Ten Years Comes With Yearly Withdrawals
According to IRS Publication 590-B (2025), when an IRA owner dies after 2019, most beneficiaries must empty the account within ten years. The exceptions cover a surviving spouse, a minor child, a disabled or chronically ill person, and someone not more than ten years younger than the owner. A 57-year-old daughter usually fits none of those groups.
The timing of her mother’s death matters. The tax code says that once an owner has started distributions, the rest of the account must be paid out “at least as rapidly”[1] as under the method she was already using. Final regulations published July 19, 2024 read that rule to require yearly withdrawals from beneficiaries on the 10-year clock. Those rules apply to RMDs starting in 2025.
Many heirs assumed they could wait until the last year. The IRS waived the excise tax on certain missed withdrawals for 2021, 2022, 2023 and 2024, but those waivers did not extend the 10-year deadline. Vanguard puts the current rule simply: an RMD “may be required in years 1–9 when the decedent had already begun taking RMDs.”
How Each Year’s Amount Is Figured
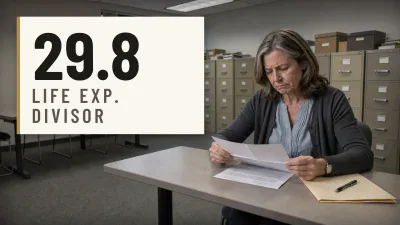
Each withdrawal depends on two numbers. The first is the account balance as of December 31 of the prior year[2]. The second is a divisor from the IRS Single Life Table, the greater of the beneficiary’s remaining life expectancy or the deceased owner’s, reduced by one each year. Because the daughter is decades younger, her own life expectancy usually gives the larger divisor.
For a 57-year-old, the table divisor is 29.8. If the balance were still $240,000 at the relevant year-end, dividing it by 29.8 gives a first-year withdrawal of about $8,054. Each later year uses that year’s balance and a divisor one lower.
Those early withdrawals are small next to the balance. Anything still in the account at the end of year ten has to come out in that single year, though. A beneficiary who takes only the minimum through year nine can end up with a large lump sum on one tax return.
What a Missed Withdrawal Costs
Skipping a year brings a 25% excise tax on the shortfall under 26 U.S.C. § 4974(a). Before SECURE 2.0 changed it, the rate was 50%. If the full $8,054 withdrawal were missed, the tax would be about $2,014.
The rate drops to 10% if the shortfall is fixed within the correction window. That window closes at the earliest of three events: the IRS mails a deficiency notice, the tax is assessed, or the last day of the second tax year after the year the tax applied arrives. On the same missed amount, 10% comes to about $805.
Her Mother’s Unfinished Withdrawal
One more withdrawal may already be due before the first inherited-IRA RMD. Vanguard notes that a beneficiary “must take an RMD for the year of the IRA owner’s death if the owner had an RMD obligation that wasn’t satisfied.”
A mother who died early in the year may not have taken hers yet. If she held several IRAs left to different people, Treasury regulations split the unpaid amount among those accounts based on their balances[2]. Her account history for that year shows whether the money ever came out.
Inherited IRA timing is one of several IRS rules that quietly pull money out of retirement accounts at the wrong moment. We mapped it alongside eight others in a free guide to retiree tax traps.
Rules That Are Still Being Finalized
Some guidance is still pending. IRS Announcement 2026-7, issued March 9, 2026, said certain parts of future final RMD regulations will take effect no earlier than 6 months after publication. Until then, taxpayers must use a “reasonable good-faith interpretation” of the statute. The yearly withdrawal rule for heirs of owners who had already started RMDs is part of the 2024 final regulations and is already in effect.
For a 57-year-old who inherits $240,000 from a mother already taking RMDs, ten years marks the deadline for emptying the account. Her first required withdrawal comes the year after her mother’s death, and her mother’s unfinished one may be due even sooner.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.