The $400,000 of Stock He Put in His Kids’ Trust in 2012 Is Worth $4 Million. Everyone Says It Will Never Get a Step-Up. He’ll Swap It Back for Cash, and the IRS’s Share of That Gain Will Be Zero

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
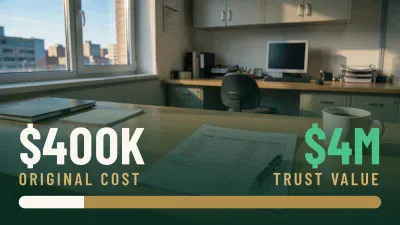
He put $400,000 of stock, with a cost basis of $400,000, into a trust for his kids in 2012, and today it’s worth $4 million. He’s proud of that number until his accountant explains what comes with it. The trust is irrevocable, so the shares still carry his original cost. When his kids sell, they’ll owe capital gains tax on nearly all of the growth.
There is a way around it, though, and it’s written into many of these trusts. If the trust is a grantor trust with a swap power, he can get a step-up in basis on irrevocable trust assets by buying the stock back with cash. The swap itself is tax-free, and the stock steps up when he dies.
A Swap Clause Can Reverse the Lost Step-Up
Our earlier piece on grantor trusts explained the problem. Stock you give to an irrevocable trust stays out of your taxable estate, so it gets no fresh basis when you die. In Rev. Rul. 2023-2, the IRS said such a trust “does not fall within any of the seven types of property listed in Section 1014(b).” Plenty of these trusts, however, let the grantor take assets back by replacing other property of equal value.
That’s what planners call a swap power. He gives the trust $4 million of cash and takes the stock back. The trust still holds exactly the same value as before. The stock is in his name again, so it’s part of his estate and qualifies for a basis reset at death under 26 U.S.C. § 1014[1].
Why the IRS Treats the Swap as a Deal With Himself
The power comes from 26 U.S.C. § 675(4)(C)[2], which describes “a power to reacquire the trust corpus by substituting other property of an equivalent value.”[2] When someone holds that power in a nonfiduciary capacity, the grantor is treated as the trust’s owner for income tax purposes. In a 1985 IRS revenue ruling, Rev. Rul. 85-13, the IRS treated deals between a grantor and his grantor trust as deals with himself. You can’t sell something to yourself, so the swap triggers no gain. Then, when he dies, the stock’s basis resets and the $3,600,000 of built-in gain is wiped out. A second ruling, Rev. Rul. 2008-22, found that a retained swap power “will not cause the value of the trust corpus to be included in D’s gross estate under § 2036 or 2038.”
Who Qualifies and Who’s Shut Out
To use this, the trust must be a grantor trust, the document must include the substitution power, the grantor must be alive, and he must have assets of equal value to hand over. It won’t work if the trust has no substitution clause, if grantor trust status has been terminated, or after he dies. His estate stays the same size, because cash goes out and stock of equal value comes in. For 2026, the federal estate tax exclusion is $15,000,000 under the One Big Beautiful Bill Act (OBBBA).
Five Steps to Complete the Swap
- Read the trust document. Confirm it has a § 675(4)(C) power, see who holds it, and check that it’s held in a nonfiduciary capacity.
- Pin down the value on the swap date. With publicly traded stock, that’s the market price that day. Put it in writing.
- Have the cash ready. A $4 million block of stock takes $4 million of cash.
- Give the trustee written notice. Under Rev. Rul. 2008-22, the trustee has “a fiduciary duty to ensure that the assets exchanged are of equivalent value.”
- Retitle the assets and keep the records. The stock moves to him and the cash moves to the trust. His executor will need date-of-death values, and § 1014(f) requires basis consistency for property that increases federal estate tax liability.
Where This Plan Can Fall Apart
The biggest catch is money. Many grantors don’t have $4 million of cash sitting around. Swapping in a promissory note instead raises open questions, and estate planners still argue over whether a note can be swapped. Timing is the next trap. The swap only works while he’s alive, and nobody knows how much time they have. Waiting too long means the kids keep his $400,000 basis.
The stock also keeps that old basis while he holds it. If he sells it during his lifetime, he owes tax on the full gain. The trustee can refuse a swap if the values don’t match, and the trust gives up any future stock growth. After his death, the trust’s own tax brackets are tight. Trust capital gains above $16,250 are taxed at 20% in 2026.
Compare that with doing nothing. If the kids sell at $4 million using his basis, the federal tax at the 20% top rate plus the 3.8% net investment income tax comes to about $856,800, before any state tax. If he swaps in time and the kids sell at the date-of-death value, they owe nothing on the gain.
Look for One Clause Before Anything Else
Whether this works for him comes down to one paragraph in the trust document and enough cash to match the stock’s value. If both are in place, the gain that has built up since 2012 can be erased at his death.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.