He Worked 20 Years for the Railroad, Then 20 Years Off It. His Social Security Benefit Cut His Railroad Tier I Dollar for Dollar.
A freight-rail mechanic paid into two federal retirement systems for 40 years and expected two checks in retirement. What the Railroad Retirement Board does when Social Security kicks in catches most split-career workers completely off guard.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
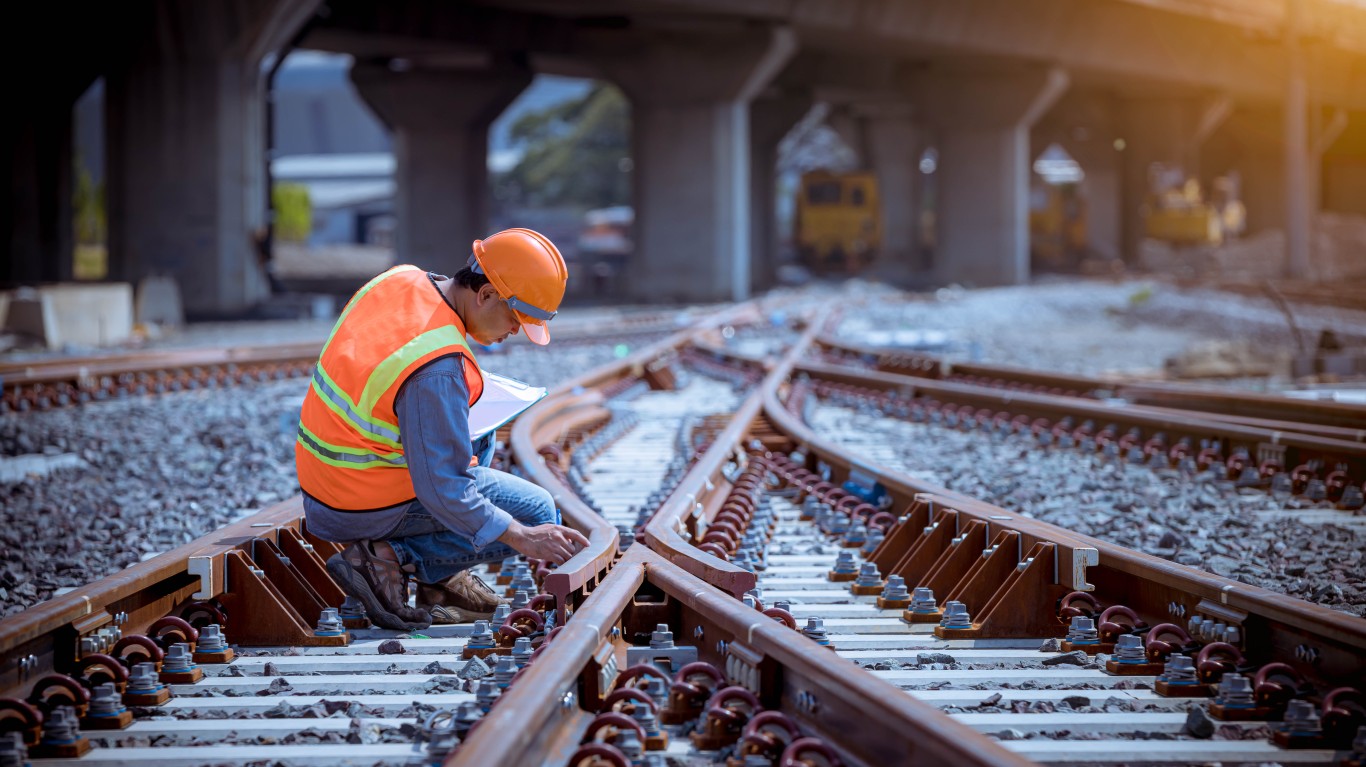
Picture a freight-rail diesel mechanic who spent 20 years turning wrenches on locomotives, then took a job at a manufacturing plant for the next 20. Two careers, two contribution histories, two federal retirement systems paid into. On paper, it looks like a windfall: a Railroad Retirement annuity and a Social Security benefit, both legitimately earned. Then the numbers arrive, and Social Security appears to erase most of one part of the railroad benefit.
Splitting a career between rail and non-rail work is common. Roundhouse mechanics, conductors, signal maintainers, and yardmasters frequently leave the industry mid-career for logistics, manufacturing, or the trades. Their families see two systems on the pay stubs and reasonably assume the retirement benefits stack. They do not stack dollar for dollar. The reason traces directly to coordination built into Railroad Retirement itself.
Why Tier I and Social Security Do Not Simply Add Up
Railroad workers are covered by the Railroad Retirement system, administered by the Railroad Retirement Board, for their rail service rather than Social Security. The benefit comes in two layers. Tier I is designed to correspond to what Social Security would provide and already takes the worker’s Social Security-covered earnings into account. Tier II is an additional benefit, closer in structure to a private pension, and is entirely separate.
Here is the mechanic’s situation in plain terms. His Tier I is calculated as if all of his earnings, rail and non-rail combined, were run through the Social Security formula. That produces a single Social Security-equivalent figure. When he becomes entitled to Social Security based on his 20 non-rail years, the Railroad Retirement Board generally reduces his Tier I by the full amount of that Social Security benefit. In most cases, the RRB then issues one combined monthly payment reflecting both amounts. The underlying wage record is counted only once.
A concrete example makes the arithmetic clear. If gross Tier I would have paid roughly $1,800 a month and his Social Security benefit comes to $900, Tier I is reduced by $900. The remaining $900 of Tier I and the $900 Social Security benefit still total approximately $1,800. Social Security replaces the portion that Tier I was already covering. The reduction exists precisely to prevent two Social Security-equivalent benefits from being paid on the same combined career record.
The Part That Still Stacks
Tier II is the piece that remains on top. It is based solely on railroad service and earnings and is never reduced because the worker also receives Social Security. That is the distinct pension-like benefit produced by the rail years, funded by the additional Tier II payroll taxes that rail employees and employers pay on top of standard Social Security rates. The most common mistake families make when they hear that Social Security cut the railroad benefit is stopping there. The cut applies to Tier I only. Total retirement income is the coordinated Tier I and Social Security amount, with Tier II added on top.
Tier I and Social Security are indexed using the same cost-of-living adjustment (COLA). The 2026 Tier I increase is 2.8%, matching the full CPI rise. Tier II receives only 32.5% of that COLA percentage, rounded to the nearest tenth, which produced a 0.9% increase for 2026. In dollar terms, the average regular railroad retirement employee annuity rose $80 a month to $3,636 as of January 2026. For workers with 30 or more years of creditable railroad service, the average age annuity at the end of fiscal year 2025 was $4,565 a month, a figure that reflects both the Tier I and Tier II components. The contrast in COLA rates matters over time: the Social Security-equivalent portion and the pension-like portion do not keep pace with inflation at the same rate, so their relative values shift gradually across a long retirement.
The Social Security Fairness Act: What Changed and What Did Not
One significant development affects a related but distinct group of railroad retirees. The Social Security Fairness Act, signed into law on January 5, 2025, repealed two provisions that the RRB knows internally as the non-covered service pension (NCSP) reduction and the public service pension (PSP) offset. These correspond to the Windfall Elimination Provision and the Government Pension Offset that applied when workers also received public pensions from employment not covered by Social Security. Under the new law, those Tier I reductions are eliminated for months after December 2023. By July 7, 2025, the Social Security Administration had completed sending more than 3.1 million payments totaling $17 billion to affected beneficiaries, finishing five months ahead of its original schedule. The Railroad Retirement Board has since confirmed that its own SSFA implementation, including all retroactive payments to railroad annuitants, is complete.
That change does not touch the standard coordination described in this article. The RRB’s own SSFA guidance is explicit: if an annuitant receives both an RRB benefit and a Social Security benefit, the Tier I amount continues to be offset by the Social Security benefit, because that offset prevents double-counting of the same career record rather than functioning as a WEP or GPO-style penalty. Split-career workers whose second job was in the private sector are not affected by the SSFA. Their coordination works exactly as it always has.
What to Do Before You File
The most expensive planning mistake is building a retirement budget by adding a full Social Security estimate to a full Railroad Retirement estimate. The RRB performs the coordination once Social Security entitlement begins, so the combined result must be modeled before either filing date is chosen. Two steps pay off before filing:
- Request a benefit estimate directly from the Railroad Retirement Board. Ask it to show gross Tier I, the Social Security reduction, net Tier I, and Tier II separately. The online RRB estimator does not account for every situation involving a separate Social Security benefit, so a split-career worker should contact an RRB field office for a tailored estimate.
- Pull your Social Security statement separately and compare the earnings records. Confirm that the non-rail wages on file with the Social Security Administration match your records. A missing year of covered wages could understate the Social Security benefit and distort the coordinated estimate.
Entitlement to both benefits is real. The key is recognizing that they are not two independent retirement checks. Tier I incorporates the worker’s entire rail and non-rail career, Social Security replaces the portion attributable to covered employment, and Tier II remains on top as a genuine additional benefit. Once those three pieces are separated and understood, the apparent cut becomes far easier to interpret and the actual retirement income far easier to plan around.
Editor’s note: This article was updated to add the fiscal year 2025 average annuity of $4,565 a month for career railroad employees with 30 or more years of service, sourced from the RRB’s August 2026 comparison of benefits. The Social Security Fairness Act section was expanded to reflect that the SSA completed distributing more than $17 billion in retroactive payments to 3.1 million beneficiaries by July 2025 and that the RRB has confirmed its own SSFA implementation is now complete.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.