ConocoPhillips Sold 43,000 South Texas Acres for $1.2 Billion. At 63, a Landowner Can Keep Getting Oil Royalties Without Social Security Calling Them Work.
A 63-year-old mineral owner collects royalty checks while another company drills his wells, but filing for Social Security early turns that seemingly passive income into a high-stakes question about which dollars actually count against him.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
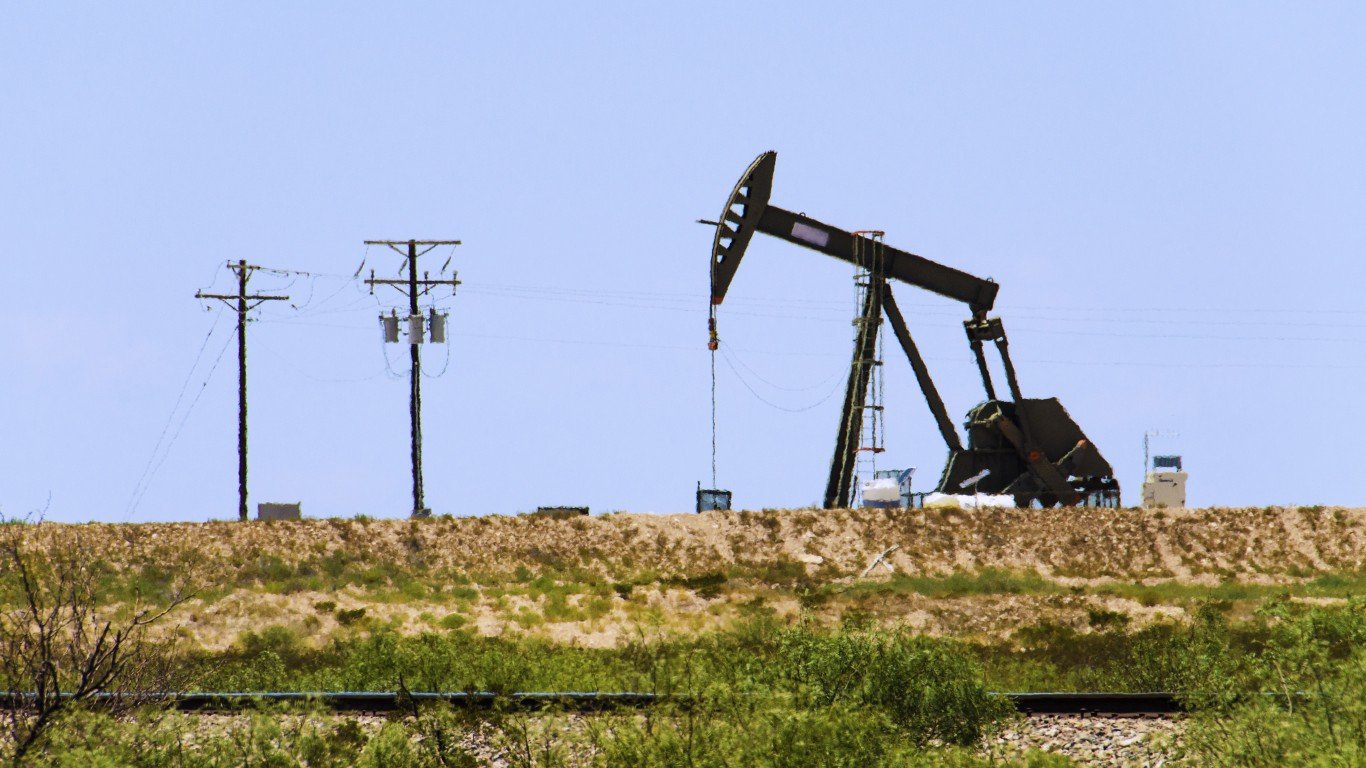
ConocoPhillips (NYSE: COP) has been pruning assets after its Marathon Oil acquisition, and one of the latest sales put a $1.2 billion price tag on 43,000 net acres in South Texas. NGP-backed Ensign Natural Resources II bought the Eagle Ford position in a July transaction. For mineral owners underneath those acres, the operator may change while the royalty checks keep coming.
Picture a 63-year-old ranch owner considering Social Security. He owns the minerals, another company drills the wells, and his share of production arrives as a royalty payment. Does that oil money count as earnings under Social Security’s retirement earnings test? For a typical nonoperating royalty owner, generally not.
Leave the Royalty Check Alone
Someone under full retirement age (FRA) all year can earn $24,480 in 2026 before Social Security starts withholding $1 in benefits for every $2 above the limit. But the test generally counts wages and net earnings from self-employment, not every kind of taxable income.
Social Security Administration guidance describes the usual oil-and-gas lease this way: the landowner grants an operator the right to drill, the operator pays the development and operating costs, and the owner receives a royalty from production. SSA excludes that landowner income when computing self-employment income. The IRS similarly directs royalties from oil, gas and mineral properties that are not operating interests to Schedule E. So a mineral owner can receive a large royalty check without that payment, by itself, triggering the earnings test.
A Working Interest Changes Things
The line shifts when the owner is participating as an operator. A working interest means sharing in the costs and economics of developing or operating the well. The IRS generally directs operating oil-and-gas interests to Schedule C, while SSA says ownership and operation of a working interest constitutes a business. Depending on how the venture is held, that income can become net earnings from self-employment.
Suppose our 63-year-old’s full-retirement-age benefit is $2,400 a month. Starting exactly at 63 would generally pay 75% of that amount, or about $1,800 monthly. If he receives $80,000 of ordinary nonoperating royalties, those royalties generally do not cause Social Security to withhold that early benefit. If the same income reflects net earnings from an operating business, the analysis changes. The claiming age question sits on top of all of that, and we condensed the 62 versus 67 versus 70 math into a free one-page framework if it helps frame the decision.
The Tax Return Still Sees the Oil Money
Earnings-test treatment and income-tax treatment are separate questions. Oil-and-gas royalties are generally taxable as ordinary income. They can also affect whether part of a retiree’s Social Security becomes federally taxable.
For a single filer, combined income above $25,000 can begin pulling benefits into taxable income; above $34,000, up to 85% of benefits can be taxable. The comparable thresholds for married couples filing jointly are $32,000 and $44,000. That does not mean 85% of the benefit is lost to tax. It means up to 85% can be included in taxable income and taxed at the household’s applicable rate. A royalty-heavy year can also affect the timing of IRA withdrawals or Roth conversions. For someone who is 63 in 2026, required minimum distributions generally do not begin until 75.
Oil Check
Before filing for Social Security, pin down what the mineral interest actually is.
- Confirm whether the payment is a royalty or an operating interest. The lease, division order and tax reporting should help establish which side of the line the income falls on.
- Separate the earnings test from the tax bill. A royalty payment can be taxable without becoming wages or net self-employment earnings.
- Run the tax projection with Social Security included. Avoiding the earnings test does not make the royalty income disappear from the federal return.
ConocoPhillips can sell the acreage and another operator can drill the wells. For the retired mineral owner, owning the oil is not the same thing as working the oil.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.