SNAP Near $5 With 25M Paid Subscribers and Bulls Refusing to Quit
Still one of the big names in the social media space, Snap Inc. (NYSE:SNAP | SNAP Price Prediction) is sitting near $5 a share, down 37% year-to-date and roughly 52% over the past year. Despite trading near multi-year lows, retail…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Still one of the big names in the social media space, Snap Inc. (NYSE:SNAP | SNAP Price Prediction) is sitting near $5 a share, down 37% year-to-date and roughly 52% over the past year. Despite trading near multi-year lows, retail sentiment has held at 78 out of 100 this morning. The reason comes down to one word: subscribers.
On February 18, Snap announced that its direct revenue business crossed a $1 billion annualized revenue run rate, anchored by 25 million Snapchat+ subscribers, which grew 71% year-over-year in Q4 2025. CEO Evan Spiegel called it “an outside source of growth” that is “playing a critical role in diversifying our top line.” The subscriber momentum has drawn independent scrutiny from retail investors: one Reddit user documented their findings in a post titled “I manually collected n=13196 datapoints to see how many people subscribed to Snapchat+ ($5/mo) after they started charging for photo storage”, writing: “I manually collected n=13196 datapoints to see how many people subscribed to Snapchat+ ($5/mo) after they started charging for photo storage.”
I manually collected n=13196 datapoints to see how many people subscribed to Snapchat+ ($5/mo) after they started charging for photo storage
by u/wallstreetbets in wallstreetbets
Why Reddit Bulls Are Holding Their Ground
Discussion in r/wallstreetbets centers on Snap’s path to 1 billion monthly active users and what subscription monetization looks like at scale. A post titled “$110k SNAP YOLO – 1 Billion MAU” captured the mood: “They just hit 1 bil monthly users, have talked extensively about unlocking more rev per user, just turned a profit, and are spinning Specs into…”
$110k SNAP YOLO – 1 Billion MAU
by u/wallstreetbets in wallstreetbets
Three reasons bulls are digging in:
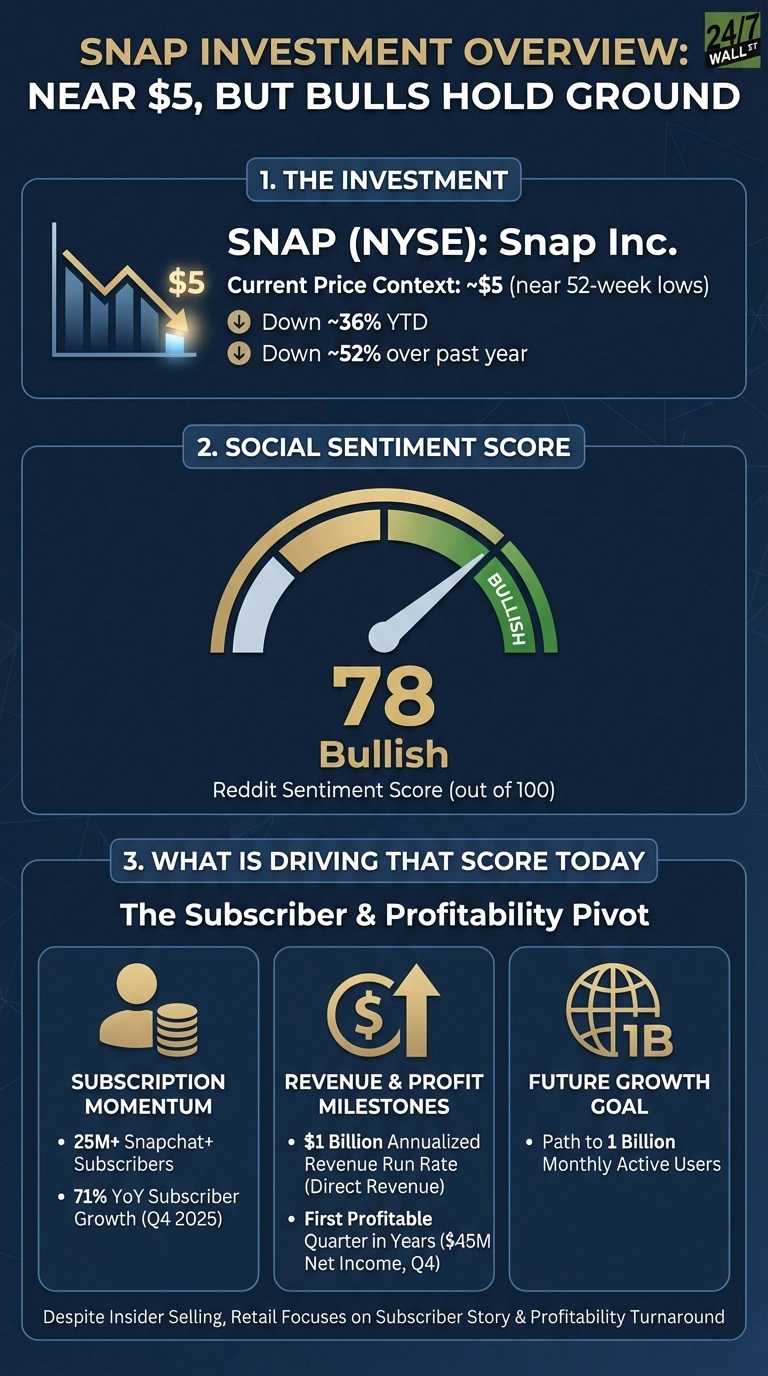
- Snapchat+ revenue grew 62% year-over-year to $232 million in Q4 2025, with a $1B annualized run rate confirmed
- Snap posted positive net income of $45 million in Q4, its first profitable quarter in years, with adjusted EBITDA margins at 21%
- Analyst consensus sees 74% upside from current levels, with a consensus price target of $8.98 across 25 analysts
The Insider Selling Problem
Even if Reddit bulls remain bullish, the bearish case is hard to dismiss as CEO Spiegel sold roughly $20 million in shares between December and January when the stock traded above $8. CTO Robert Murphy followed with $10.6 million in sales in early February. The CFO, General Counsel, Chief Business Officer, and Chief Accounting Officer all sold shares in mid-February as the price fell to the $4.70-$4.84 range. As notable as it is that executives sold shares, so too is it a potential flag that no executive bought shares during this period either.
For its part, Wall Street is split as Goldman Sachs cut its target from $9.50 to $8.50 and Morgan Stanley slashed from $9.50 to $6.50, while Arete and B. Riley upgraded the stock, citing limited downside.
Snap’s subscription business carries structurally higher margins than advertising. Gross margins hit 59% in Q4, with management targeting above 60% in 2026. Prediction markets price a Snap acquisition at just 13.1% probability before year-end. Q1 2026 guidance of $1.5 billion to $1.53 billion in revenue will be the next real test of whether subscriber momentum can outweigh the pressure from insider selling and intensifying competition.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.