The smartphone era is ending the way it started: with Apple
In 2007, Apple opened the smartphone era. In 2026, Apple (NASDAQ:AAPL) is positioned to close it. The handheld glass slab that reshaped computing is now the device the industry is racing to replace with always-on, heads-up ambient AI. The company…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
In 2007, Apple opened the smartphone era. In 2026, Apple (NASDAQ:AAPL | AAPL Price Prediction | AAPL Price Prediction) is positioned to close it. The handheld glass slab that reshaped computing is now the device the industry is racing to replace with always-on, heads-up ambient AI. The company that drew the first map is drawing the next one.
Q2 FY2026 net sales hit $111.2 billion, up 17% year over year, and net income of $29.6 billion came in 22% above the year-ago period. iPhone alone delivered nearly $57 billion, a March quarter record fueled by what Tim Cook called “extraordinary demand for the iPhone 17 lineup.” Services set an all-time record at $30.98 billion, up 16% year over year, at gross margins above 76%. Total company gross margin expanded to 49.3%. R&D spending for the quarter rose to $8.2 billion, up 34%, pointed squarely at glasses and AI.
The momentum continued into the summer. Apple’s Q3 FY2026 results, reported July 30, delivered another record June quarter: $109.4 billion in revenue, up 16% year over year, and net income of $29.8 billion with diluted EPS of $2.02, up 29%. Gross margin reached 50.1%, aided in part by tariff refunds. R&D spending climbed further to $11.7 billion in the quarter, up 32% from a year earlier, as the company accelerated investment across AI, custom silicon, and new device categories. Apple’s installed base of active devices topped 2.5 billion for the first time.
Those financials frame a pivotal leadership moment. Apple announced on April 20, 2026 that Cook would step down as CEO on September 1, transitioning to the role of executive chair of the board. John Ternus, who served as senior vice president of Hardware Engineering, took over as chief executive on that date. Johny Srouji stepped into an expanded chief hardware officer role to fill the gap Ternus left behind. The handover places a hardware-engineering mind at the top of Apple just as the company prepares its most consequential product bets since the iPhone itself.
The roadmap is the thesis
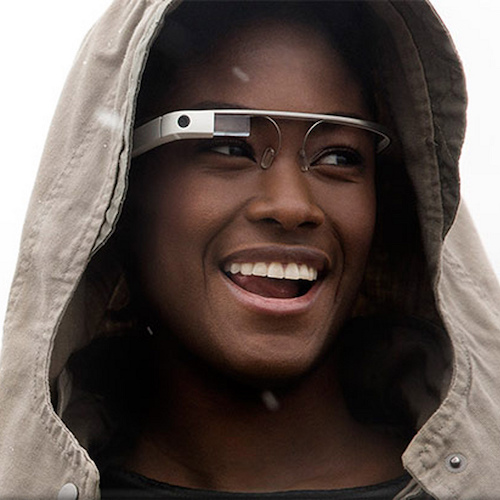
Apple refreshed Vision Pro to M5 silicon and is now targeting a late-2027 commercial launch for its first Ray-Ban-style AI glasses. That timeline represents a meaningful slip: the original plan, per Bloomberg’s Mark Gurman, called for a late-2026 reveal and early-2027 shipment, but development bottlenecks around visual AI software pushed the schedule back by roughly a year. The glasses, code-named N50, will feature cameras, speakers, and microphones, with multiple frame styles and no display in the first generation. They will run a Watch-derived low-power chip and pair tightly with the iPhone rather than operating as standalone devices. Apple is targeting a price range of roughly $200 to $500 for the N50, which would put it in direct competition with Meta’s lineup.
The broader Vision roadmap has also shifted. A lighter, more affordable Vision Air headset was pushed to 2028 or 2029 after Apple redirected engineers toward the glasses project. Incoming CEO Ternus ordered a sharper focus on smart glasses over headsets, with analyst Ming-Chi Kuo reporting that the refined product set narrowed to two glasses products. Vision Pro Gen 2 with LCoS waveguides remains on the longer-horizon roadmap.
The structural advantages
Three competitive positions are difficult for rivals to replicate. The first is distribution: the iPhone install base of more than one billion units (Apple counts 2.5 billion active devices across all categories) becomes the compute backbone for its glasses, with most processing offloaded to the paired phone. The second is silicon: Apple has reportedly booked more than 50% of TSMC’s initial 2nm capacity for 2026, and the GAA nanosheet architecture delivers up to 30% better power efficiency than 3nm, a decisive edge in heat-limited eyewear. The third is capital: Apple holds $147 billion in cash and marketable securities, providing ample runway for multi-year memory pre-buys as DRAM and HBM prices have surged.
The company also returned substantial capital even as it invested aggressively. Apple authorized $100 billion in share repurchases alongside a 4% dividend increase to $0.27 per share quarterly. Through the first nine months of fiscal 2026, the company generated approximately $117 billion in operating cash flow, compared with $81.8 billion in the same period a year earlier.
Google and Meta as foils
Google’s Android XR strategy leans on Warby Parker, Gentle Monster, Gucci, Samsung, and Xreal, a broad coalition that brings distribution but also fragmentation. Meta has a commanding head start: its Ray-Ban lineup held 69.2% of the global smart glasses market in Q1 2026, according to IDC, and Meta sold more than 7 million Ray-Ban and Oakley Meta units in 2025 alone, nearly three times what the two products sold combined across 2023 and 2024. Apple is developing its frames in-house rather than through co-branding partnerships, betting that owning the customer relationship, the silicon, and the retail storefront creates a more defensible position over time.
The inflection
The smart glasses category is growing fast enough to matter regardless of which unit forecast proves accurate. IDC projects display-less smart glasses will reach 13.6 million units in full-year 2026, with revenue hitting $5.1 billion, and the category is expected to grow to 27.3 million units by 2030. Display-less smart glasses shipped roughly as many units in Q1 2026 alone as the entire category did across all of 2024, a 167% surge year over year. Either trajectory makes 2026 the breakout year, and Apple has yet to enter.
Apple is arriving late by design. That is the iPhone playbook: let a category prove itself, then redefine it. Risks remain, including U.S. and EU antitrust pressure on App Store economics, GDPR friction around camera-equipped frames, rising memory costs that Apple’s own CFO has flagged as an increasing headwind, and potential yield slips on 2nm production. None of those risks alter the fundamental setup. By 2030, the smartphone peak will be remembered as the precursor to the ambient era.
Once again, Apple is drawing the new map.
Editor’s note: This article has been updated to reflect Apple’s Q3 FY2026 results (revenue $109.4 billion, net income $29.8 billion, R&D spending $11.7 billion, active device base surpassing 2.5 billion), the confirmed September 1, 2026 handover of the CEO role from Tim Cook to John Ternus, the clarified Apple glasses timeline (originally a late-2026 reveal with early-2027 shipment, now a late-2027 launch per Bloomberg), an updated target price range of $200 to $500 for the N50, and Meta’s 69.2% smart glasses market share in Q1 2026 with more than 7 million units sold in 2025.
Contact [email protected] for any questions or corrections.
Don Lair writes about options income, dividend strategy, and the kind of boring-but-durable investing that actually funds retirement. He's the founder of FITools.com, an independent contributor to 24/7 Wall St., and a former writer for The Motley Fool.