Nvidia vs Palantir: Clash of AI Titans Heats Up
NVIDIA (NASDAQ: NVDA | NVDA Price Prediction) and Palantir (NASDAQ: PLTR) just delivered the cleanest hardware-versus-software split in the AI economy. NVIDIA closed FY2026 with $215.94B in revenue and another Data Center blowout. Palantir followed up with Q1 2026 revenue…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
NVIDIA (NASDAQ: NVDA | NVDA Price Prediction) and Palantir (NASDAQ: PLTR) just delivered the cleanest hardware-versus-software split in the AI economy. NVIDIA closed FY2026 with $215.94B in revenue and another Data Center blowout.
Palantir followed up with Q1 2026 revenue of $1.633B, up 85% year over year, the fastest growth it has ever reported as a public company. Two reports, one AI build-out, very different exposures.
Blackwell Floods the Data Center. AIP Floods the C-Suite.
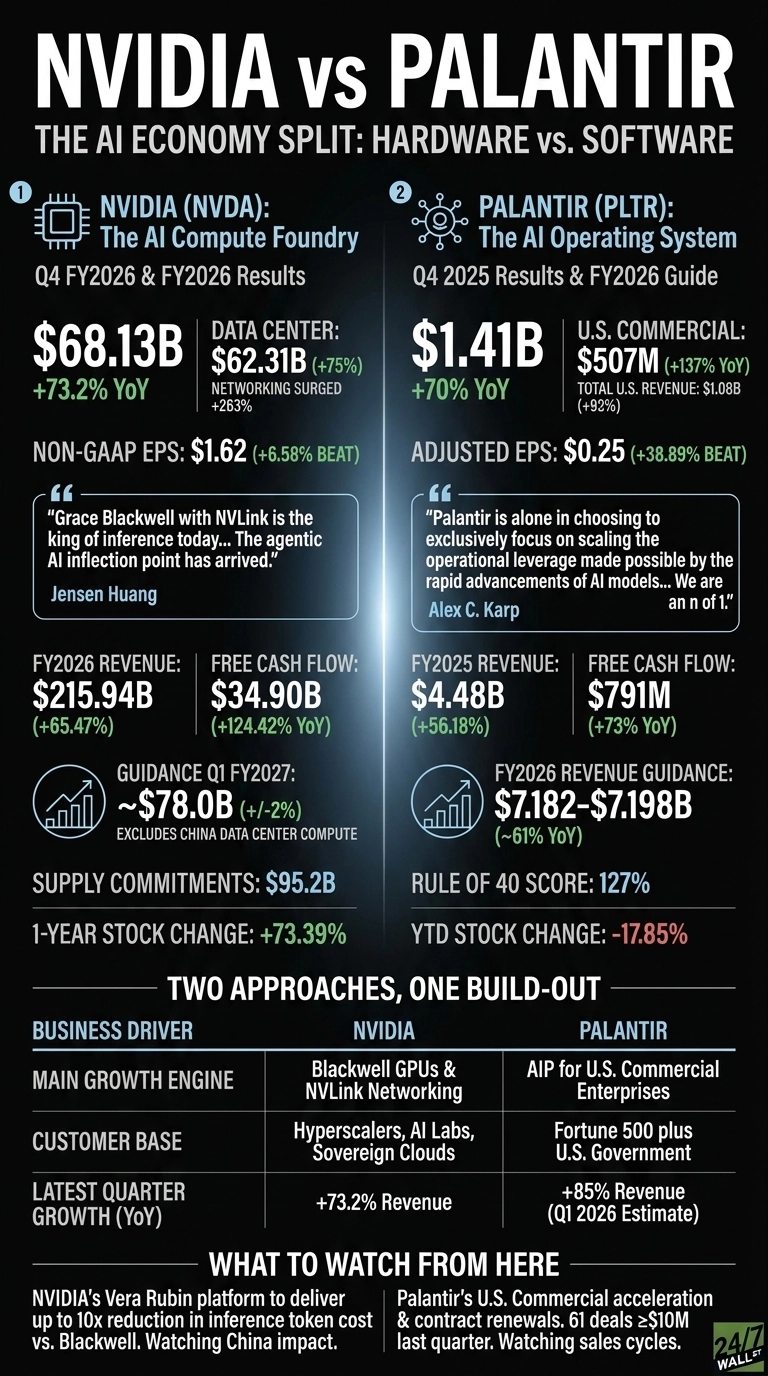
NVIDIA’s Data Center segment generated $62.31B in Q4 FY2026, up 75%, with networking surging 263% as NVLink fabrics shipped inside GB200 and GB300 racks. Non-GAAP EPS came in at $1.62, beating the $1.52 consensus. Jensen Huang told investors “Grace Blackwell with NVLink is the king of inference today”, and the guide reflected it: $78.0B for Q1 FY2027, even with China Data Center compute revenue stripped out.
| Business Driver | NVIDIA | Palantir |
| Main Growth Engine | Blackwell GPUs and NVLink networking | AIP for U.S. commercial enterprises |
| Customer Base | Hyperscalers, AI labs, sovereign clouds | Fortune 500 plus U.S. government |
| Latest Quarter Growth | 73.2% revenue YoY | 85% revenue YoY |
Palantir is selling the layer above the silicon. U.S. Commercial revenue hit $595M, up 133% year over year, and adjusted EPS landed at 33 cents, beating the 28 cent estimate. Alex Karp framed it bluntly, calling Palantir “an n of 1” focused on what he calls commodity cognition. Customer count keeps climbing, and management raised the FY2026 revenue guide to $7.66B, roughly 71% growth.
One Builds the Factory. The Other Runs the Floor.
The strategic split is sharper than the headline beats suggest. NVIDIA is committing capital like a utility: $95.2 billion of supply commitments and multiyear deals with Meta, OpenAI, Anthropic, and CoreWeave. Vera Rubin is already teed up to deliver up to a 10x reduction in inference token cost versus Blackwell. Margins still expanded, with non-GAAP gross margin reaching 75.2%.
Palantir is taking the opposite shape: capital-light, software-pure, and unusually profitable for a hyper-grower. Karp pointed to a Rule of 40 of 145%, a number historically reserved for chip companies. Adjusted free cash flow of $925M at a 57% margin shows AIP deployments are landing without expensive customization tails. Stock-based comp remains high, and valuation reflects the optimism.
China Risk for One. Sales Cycle for the Other.
I will be watching whether NVIDIA’s Q1 FY2027 actually clears the $78B bar without any China Data Center contribution. Networking is the tell. If the 263% NVLink growth holds even partially, the Blackwell-to-Rubin transition is intact.
Rosenblatt analyst John McPeake raised the firm’s price target to $225 from $200 and keeps a Buy rating on the shares. Palantir’s deal mix is also worth watching. 61 deals of $10M or more last quarter says enterprises are signing real contracts, but termination-for-convenience clauses make every renewal cycle a fresh negotiation.
What To Watch From Here
NVIDIA’s setup rests on backlog, margin profile, and the Vera Rubin roadmap, with shares already up 73.39% over the past year. Palantir’s case rests on growth at scale: 85% reacceleration at multi-billion-dollar revenue is rare, and shares have pulled back 17.85% year to date. If commodity cognition disappoints, the multiple compresses fast. The two stocks offer distinct exposures to the same AI build-out: hardware scale at NVIDIA, software leverage at Palantir.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.