Prediction: IonQ Faces Headwinds That Could Push It Lower Despite Quantum Hype
I’m going to lead with the verdict. Our 24/7 Wall St. price target for IonQ (NYSE:IONQ | IONQ Price Prediction) is $43.82 over the next 12 months, against a current price of $52.57. That implies -16.65% downside, and our model…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
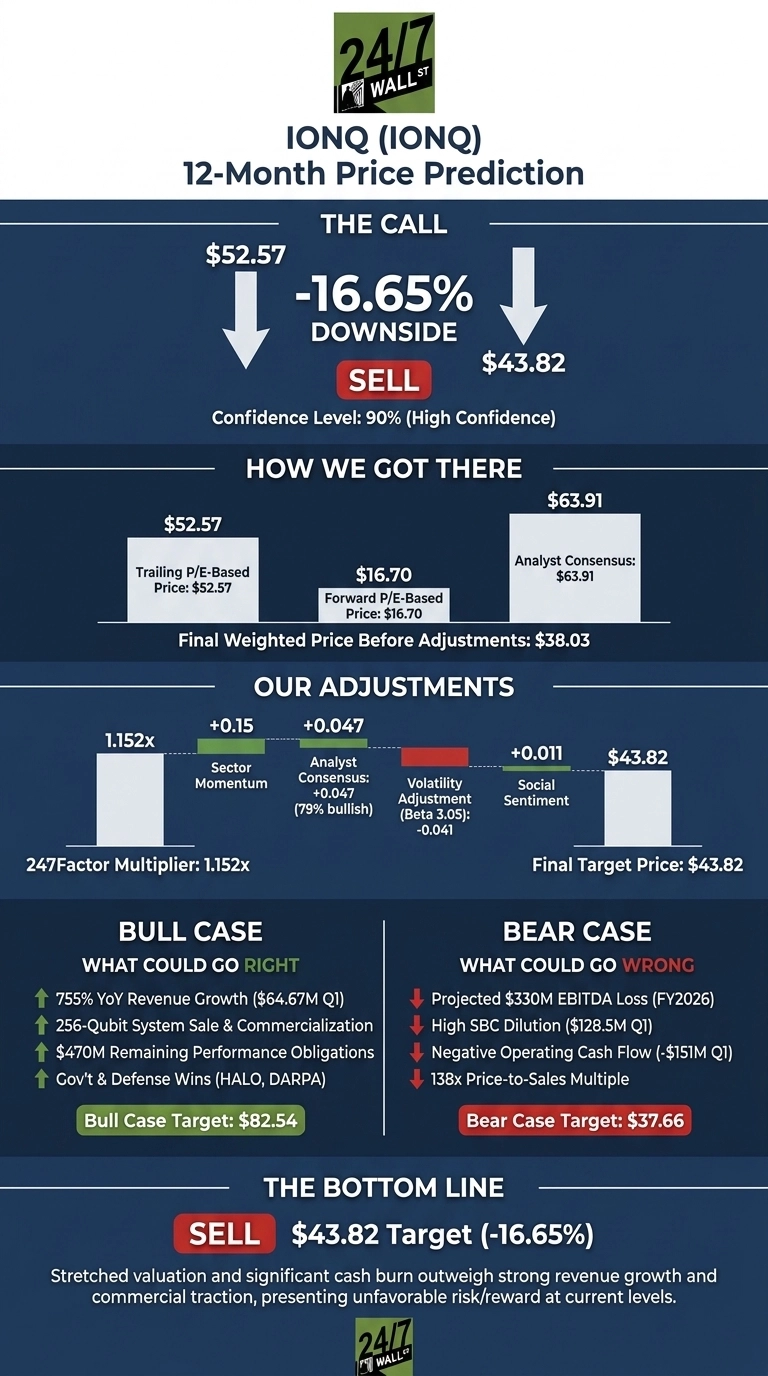
I’m going to lead with the verdict. Our 24/7 Wall St. price target for IonQ (NYSE:IONQ | IONQ Price Prediction) is $43.82 over the next 12 months, against a current price of $52.57. That implies -16.65% downside, and our model assigns this call a 90% confidence score, which I read as high conviction. The recommendation is sell, but as you’ll see, the bull case here is genuinely strong.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $52.57 |
| 24/7 Wall St. Price Target | $43.82 |
| Upside/Downside | -16.65% |
| Recommendation | SELL |
| Confidence Level | 90% |
Why We Could Be Wrong
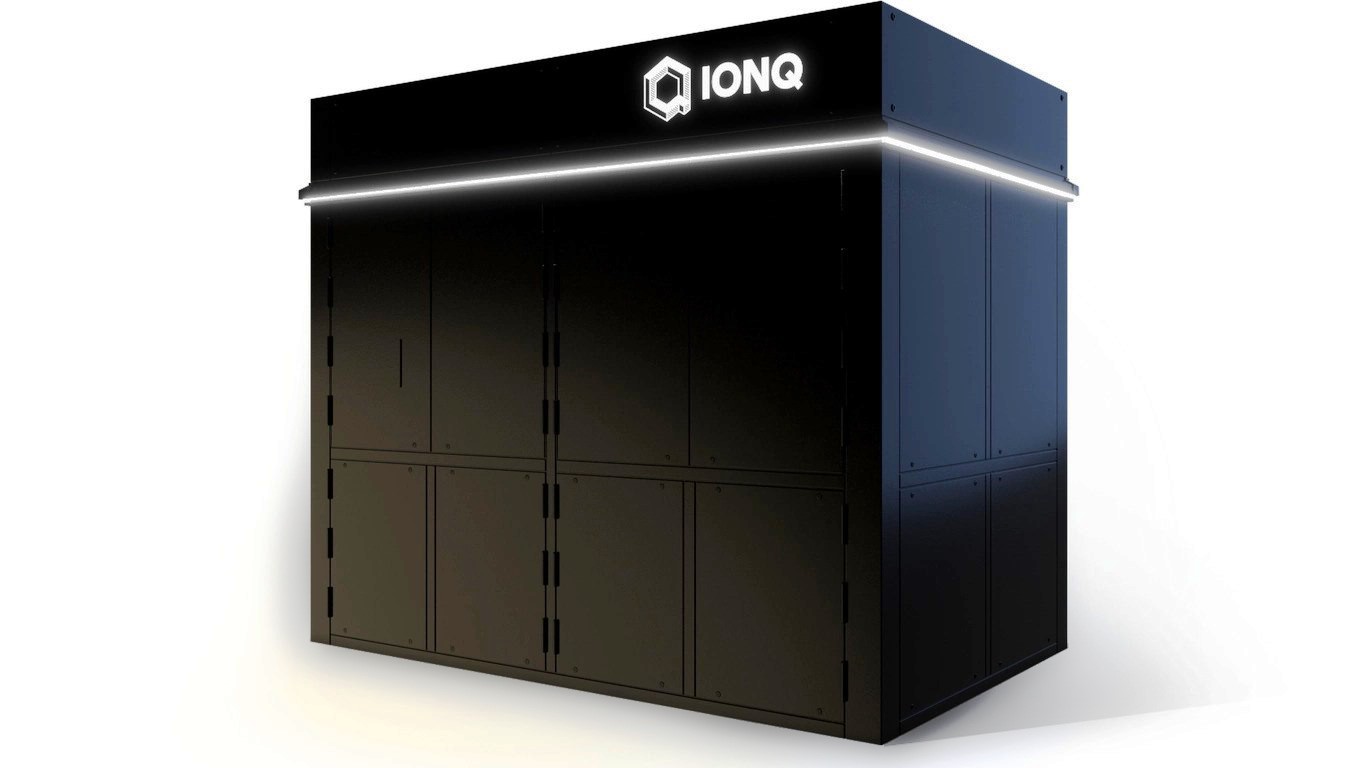
Before going further, I want to be honest: our price target sits below where IonQ trades today, and IonQ is one of the most divisive names in tech. Real upside could come from the 256-qubit system commercialization ramp, or from the Polymarket-tracked question of whether the US federal government takes a stake, currently priced at 47.5%. Treat our target as one datapoint. A full bull case follows below.
A 755% Revenue Beat and a Guidance Raise
IonQ shares jumped 9.52% on May 6, 2026 after Q1 2026 revenue landed at $64.67 million, up 755% year over year and 30% above the midpoint of guidance. Management raised full-year revenue guidance to $260 million to $270 million. The stock is up 79.79% in the past month and 78.69% over the past year, though it remains 24% below the 52-week high of $84.64. Adjusted EPS was -$0.34, with adjusted EBITDA loss of $96.75 million.

The Case for $80+
Bulls have a real story. Remaining performance obligations grew 554% year over year to $470 million, providing rare visibility for a quantum company. Roughly 60% of revenue now comes from commercial customers, signaling the long-promised shift away from pure government dependence.

Defense wins include a $39 million Space Development Agency HALO contract and DARPA’s HARQ selection. Of 14 covering analysts, 11 rate it Buy or Strong Buy with a consensus target of $63.91. Our bull-case scenario reaches $82.54 over 12 months.
The Risks Worth Watching
The bear case starts with cash burn. Operating cash flow ran -$151 million in Q1 alone, and full-year adjusted EBITDA loss is guided to ($330) million to ($310) million. Stock-based compensation hit $128.52 million, nearly double revenue, which is meaningful dilution. The price-to-sales multiple of 138x leaves little room for any execution stumble.
Bulls would counter that R&D spending of $125.74 million reflects deliberate investment in 256-qubit scaling and the pending SkyWater fab acquisition, not bloat. Still, our bear-case 12-month price is $37.66, and Reddit sentiment on options desks has skewed bearish at a 35 score.
The Bottom Line on IonQ
The 24/7 Wall St. price target of $43.82 reflects a sell recommendation with 90% model confidence. The decisive factor is valuation. A 138x sales multiple on a company guiding to a $300M+ EBITDA loss leaves the math unforgiving. The thesis would strengthen if commercial revenue mix pushes past 75% and cash burn narrows by year-end. The bear case holds if SBC remains above revenue and the SkyWater integration slips. After a 79.79% one-month run, the risk/reward looks stretched at current levels.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $48.00 |
| 2027 | $43.82 |
| 2028 | $42.50 |
| 2029 | $41.20 |
| 2030 | $40.18 |
These projections assume IonQ executes against current guidance and the quantum sector continues its multi-year normalization off frothy 2025 multiples. Significant upside could result from a federal government stake or commercial-scale 256-qubit deployments outpacing our base case.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.