Spotify vs. Netflix: Which Streaming Stock Deserves Your Retirement Capital?
Spotify and Netflix have both built dominant subscription platforms, but for a retirement-focused investor allocating capital in mid-2026, which streaming name deserves the slot? Spotify Technology (NYSE:SPOT | SPOT Price Prediction) and Netflix (NASDAQ:NFLX) are screening as bargain candidates after…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
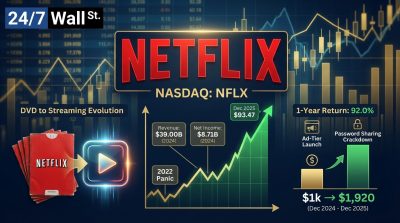
Spotify and Netflix have both built dominant subscription platforms, but for a retirement-focused investor allocating capital in mid-2026, which streaming name deserves the slot? Spotify Technology (NYSE:SPOT | SPOT Price Prediction) and Netflix (NASDAQ:NFLX) are screening as bargain candidates after both stocks have given back ground this year, but the underlying businesses are not in the same league. Three dimensions decide it.
Dimension 1: On Valuation, Netflix Wins
Netflix is materially cheaper on every multiple that matters for a long-duration holding. Custom analysis pegs Netflix at roughly 30x 2026 estimates against Spotify at 50x. The cleaner trailing snapshot tells the same story: Spotify carries a P/E of 34x with a forward P/E of 34x, while Netflix sits at a trailing 28x and a forward 27x. On enterprise value to EBITDA, the gap is even wider: Netflix at 11x versus Spotify at 27x.
Retirement capital cannot afford to overpay for growth that may not show up. Spotify is asking investors to underwrite a premium multiple on a business growing slower than the one trading at a discount. That math does not work.
Dimension 2: On Growth Trajectory, Netflix Wins
Netflix grew Q1 2026 revenue 16% year over year to $12.25 billion, with full-year guidance reaffirmed at $50.70B to $51.70B (12% to 14% growth). Spotify, by contrast, posted Q1 2026 revenue growth of just 8%, and management’s Q2 operating income guide fell short of Wall Street forecasts, causing post-earnings stock decline.
The forward driver is even more lopsided. Netflix’s ad-supported tier represented over 60% of all Q1 sign-ups in ads markets, advertiser count grew 70% YoY to over 4,000 clients, and ad revenue is tracking to ~$3B in 2026. Spotify’s ad-supported segment, by contrast, declined 5% year over year in Q1. One company is accelerating into a new revenue stream. The other is leaning on subscription mix.
Dimension 3: On Profitability and Cash Engine, Netflix Wins
This is where the gap turns into a chasm. Netflix’s operating margin is targeted at 32% for 2026, with Q2 already guided to 33%. Spotify’s operating margin sits at 16%. Return on equity tells the same story: Netflix at 49%, Spotify at 38%.
Free cash flow is the clincher. Netflix raised 2026 FCF guidance to ~$12.50 billion from $11B prior, and Q1 alone produced $5.09 billion in FCF. Spotify’s full-year 2025 FCF came in at $2.874 billion. Netflix also has $6.8B remaining on its buyback authorization, repurchasing 13.5M shares for $1.3B in Q1 2026.
The Verdict
Neither name pays a dividend, so retirees seeking yield should look elsewhere entirely. For retirement capital being deployed into streaming as a growth-stable communications-services holding, Netflix is the answer. It is cheaper, growing roughly twice as fast, and producing margins and cash flow that Spotify’s business model cannot structurally match in this decade.
Spotify has a place: it suits a growth-tilted retiree who specifically wants exposure to a fortress balance sheet (the company runs net cash with a net cash balance sheet) and AI-driven audio optionality. Spotify shares are also down 24% over the past year and 13% year to date, which could appeal to contrarians. But as the core retirement holding between these two, Netflix wins on valuation, scale, and the predictability of the cash engine. Spotify is the speculative leg in this pairing; Netflix screens as the core holding.
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.