Microsoft Forecast: Strong Buy With Near-Unanimous Analyst Support
Microsoft (NASDAQ:MSFT | MSFT Price Prediction) has been one of the cleanest setups in mega-cap tech this year. After a sharp pullback from last summer’s highs, the stock now trades where the analyst community, prediction markets, and our model align.…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
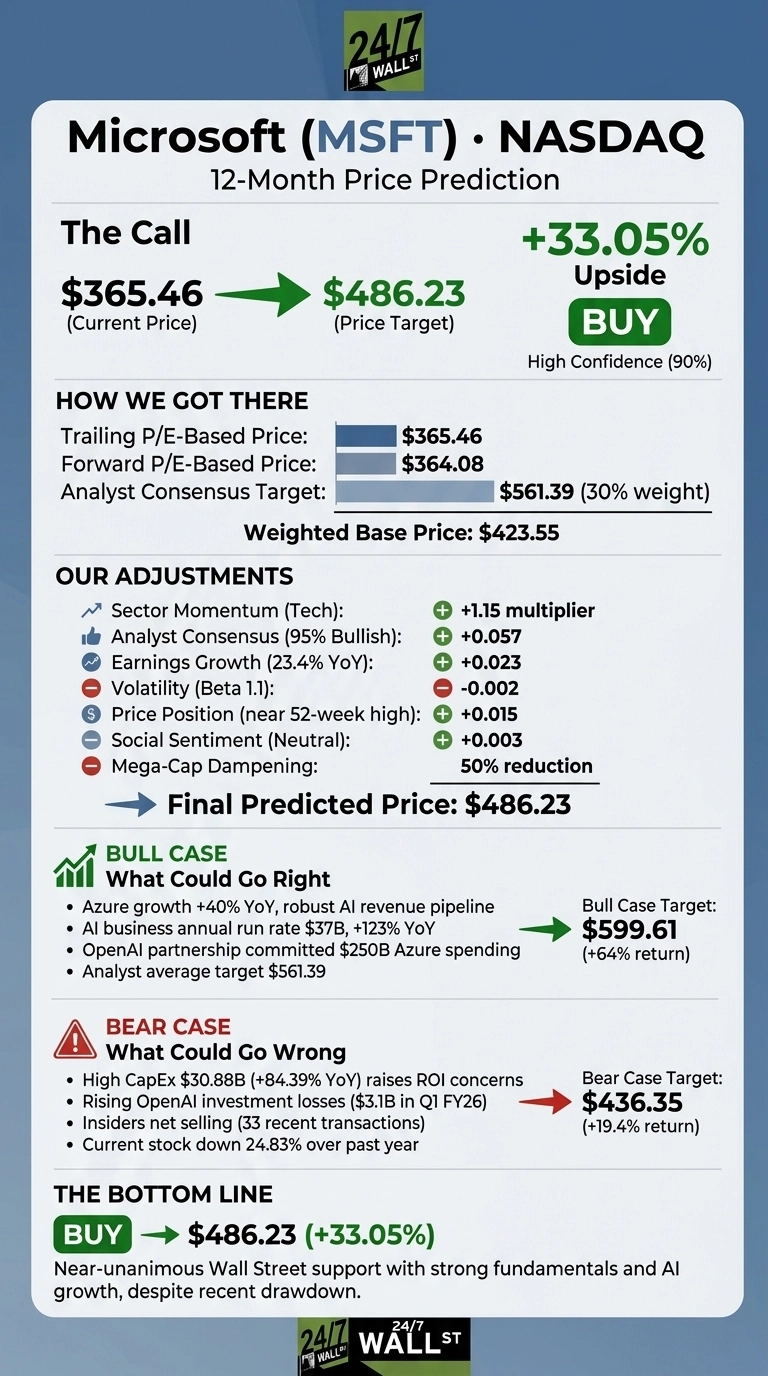
Microsoft (NASDAQ:MSFT | MSFT Price Prediction) has been one of the cleanest setups in mega-cap tech this year. After a sharp pullback from last summer’s highs, the stock now trades where the analyst community, prediction markets, and our model align. Our 24/7 Wall St. price target for Microsoft is $486.23, and our confidence in that number is high.

The 24/7 Wall St. Price Target at a Glance
| Metric | Value |
|---|---|
| Current Price | $365.46 |
| 24/7 Wall St. Price Target | $486.23 |
| Upside | 33.05% |
| Recommendation | BUY |
| Confidence Level | 90% |
That implied 33% upside over the next 12 months reflects a stock punished by the broader AI capex debate while the underlying business keeps compounding. With 52 Buy ratings against 3 Hold and 0 Sell, Microsoft enjoys near-unanimous Wall Street support.
A 25% Drawdown Despite Accelerating Fundamentals
Microsoft is down 24.83% over the past year and 24.1% year to date, with a 12.69% slide in the past month alone. Shares sit roughly 2% off the 52-week high of $551.05 after retracing from $520 in August 2025.
The fundamentals tell a different story. Q3 FY26, reported April 29, 2026, delivered EPS of $4.27 against a $4.07 estimate and revenue of $82.89 billion, up 18.3% year over year.
Azure grew 40%, Microsoft Cloud reached $54.5 billion, and CEO Satya Nadella highlighted that “our AI business surpassed an annual revenue run rate of $37 billion, up 123% year-over-year.” Commercial RPO sits at $627 billion, up 99%.

Why Bulls See a Breakout Ahead
The bull case rests on Azure and Copilot monetization compounding faster than sell-side models. With OpenAI committed to $250 billion of additional Azure spending and Microsoft holding a 27% OpenAI stake worth roughly $135 billion, the revenue pipeline is pre-funded.
Vanguard’s 2026 outlook notes that “U.S. technology stocks could well maintain their momentum given the rate of investment and anticipated earnings growth.” The Street’s average target of $561.39 is well above our base case, and our bull scenario points to $599.61, a 64% return.

What Could Go Wrong
Microsoft’s CapEx hit $30.88 billion in Q3 FY26, up 84.39% YoY, and OpenAI investment losses ballooned to $3.1 billion in Q1 FY26 from $523 million a year earlier. If AI ROI disappoints, multiple compression follows.

Insiders have been net sellers across 33 recent transactions, and prediction markets assign just 31.5% odds that Microsoft’s valuation tops Anthropic plus OpenAI by year-end. Bulls counter that heavy CapEx funds the $627 billion backlog driving Azure’s growth. Our bear case lands at $436.35, a 19.4% gain.
Microsoft Price Prediction 2026-2030
My recommendation is buy with 90% confidence, anchored to the 24/7 Wall St. price target of $486.23. At a 26 P/E with 33% ROE and 40% Azure growth, Microsoft is cheaper than its growth profile deserves.
The bull thesis depends on Azure holding 30%+ growth into FY27. The bear thesis hinges on AI CapEx outrunning monetization for another two years.
Here is where the 24/7 Wall St. price target model projects Microsoft could trade, assuming current growth trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $415 |
| 2027 | $486 |
| 2028 | $572 |
| 2029 | $673 |
| 2030 | $791 |
These projections assume Azure and Copilot continue compounding at current rates. Significant upside or downside could result from the pace of AI monetization and OpenAI’s economics flowing back to Microsoft’s bottom line.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.