Price Prediction: Can Microsoft Reach $650 Next Year?
Microsoft's AI business is scaling at a pace that almost never happens at this size, yet the stock sits near its 52-week low. Here is what has to happen for shares to nearly double by 2027, and what breaks the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is running one of the fastest scaling AI businesses in corporate history, yet the stock is acting like the story just broke. Satya Nadella told investors “Our AI business surpassed $37 billion ARR, up 123%” and Microsoft Cloud delivered $54 billion in revenue, up 29% year over year.
Meanwhile, shares are down 20.02% year to date and trade at $392.17. Can this stock reach $650 by 2027? The math works if a few things line up.

Why Microsoft Shares Are Stuck Despite Record AI Growth
The disconnect is real. Fundamentals are accelerating, but the stock has been ugly. MSFT is off 1.38% over the past week, 3.09% over the past month, and 22.59% over the past year.
Capital expenditures ballooned to $30.88 billion last quarter, an 84.39% year-over-year jump, and management guided to roughly $190 billion in capital expenditures for calendar year 2026. Free cash flow compressed to $15.8 billion.
With a beta of 1.13, MSFT amplifies broader tech drawdowns. Investors are punishing the AI capex race even as gross margins remain healthy. The OpenAI partnership restructuring gives the market an excuse to sit on the sidelines.
Wall Street Sees 43% Upside. Our Model Sees 27%. Who Is Right?
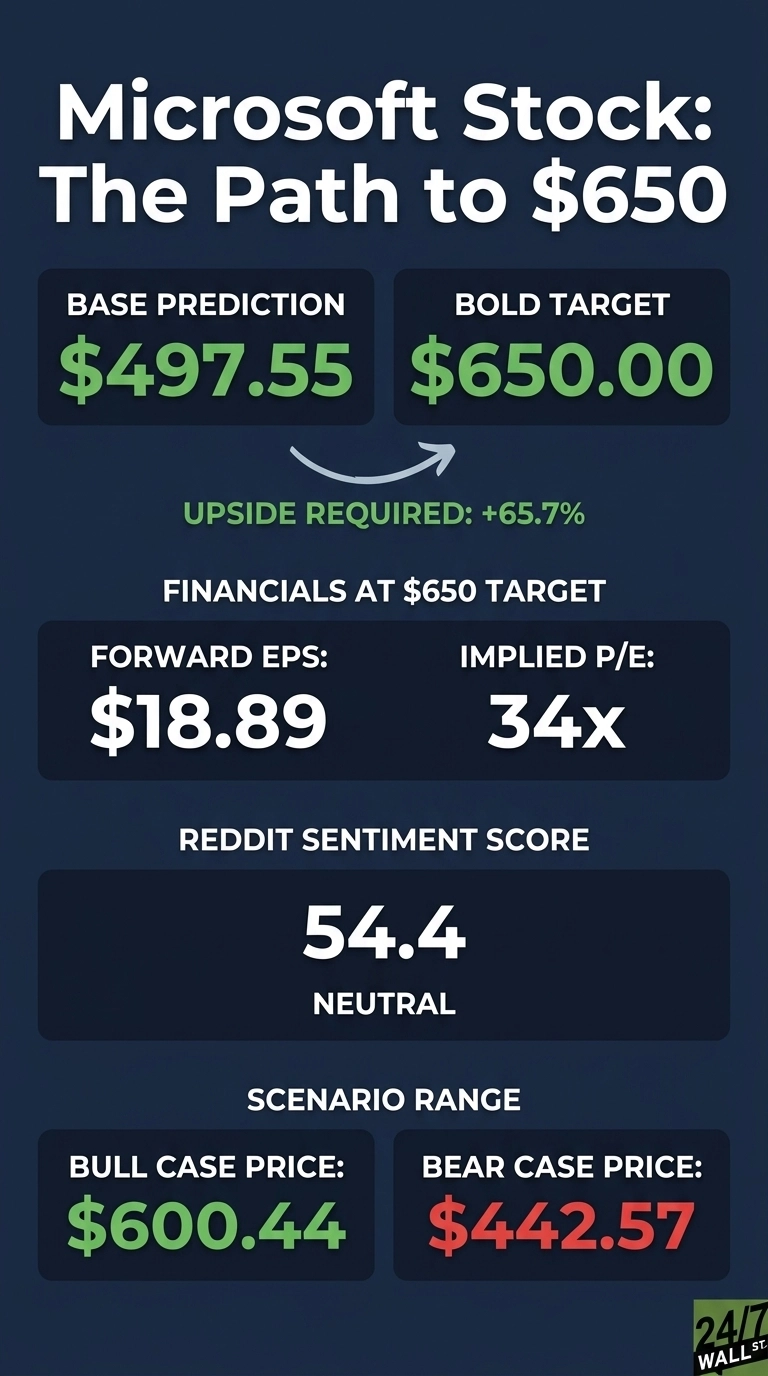
Consensus target sits at $559.86, with 13 Strong Buys, 41 Buys, and just 3 Holds. Zero sells. Our model: base case of $497.55, implying 26.87% upside, bull case of $600.44, bear case of $442.57, all at 90% confidence. The Street is likely closer to right.
Bullish analyst sentiment stands at 95%, and earnings growth runs at 23.4% year over year. Our model dampens targets 50% for mega-caps, but a company compounding AI revenue at triple digits may prove this discipline too cautious.

The Path to $650 Per Share
Reaching $650 from today’s price of $392.17 requires a gain of 65.7%. With forward EPS of $18.89, a price of $650 implies a forward P/E of 34x. Our base case of $497.55 already implies 24x, meaning the bold target requires roughly 10x additional multiple expansion. That is a stretch, but not impossible for a company where commercial remaining performance obligations reached $627 billion, nearly doubling year over year.
Nadella emphasized that “We are at the beginning of one of the most consequential platform shifts that will change the entire tech stack as agents proliferate”, and Microsoft added 20 million Microsoft 365 Copilot paid seats with seat additions up 250% year over year. The primary risk is that AI capex compresses margins faster than revenue can absorb.
Where Microsoft Trades Today vs Its Earnings Power
At $392.17 against forward EPS of $18.89, MSFT trades at roughly 21x forward earnings. For a business growing revenue 18.3% year over year with operating margins of 46%, that is not expensive.
Shares sit near their 52-week low of $349.20, well below the high of $551.05. Long term, MSFT has returned 718.59% over the past decade. The current multiple looks like a reset, not a topping pattern.
Can Microsoft Really Hit $650? My Verdict
Reaching $650 by 2027 requires a 65.7% gain.
Three things need to go right: Azure needs to sustain the 39% to 40% growth guided into Q4, Copilot needs to convert seat momentum into durable per-user economics, and margins need to stabilize as capex peaks. What derails it: a step-down in enterprise AI budgets or a demand cliff at Azure. We’ve outlined the blueprint for how Microsoft could reach $650 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.