Prediction: After a Blowout Quarter, Shopify Will End The Year at This Price
Shopify just posted its biggest single-day earnings pop in recent memory, and the rally may not be finished. Here is where the stock could land before December and what threatens to knock it off course.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Shopify (NASDAQ:SHOP | SHOP Price Prediction) just delivered the strongest earnings reaction in its recent history. Shares closed +16.98% on the Q2 print, rising from a prior close of $123.30 to $144.24.
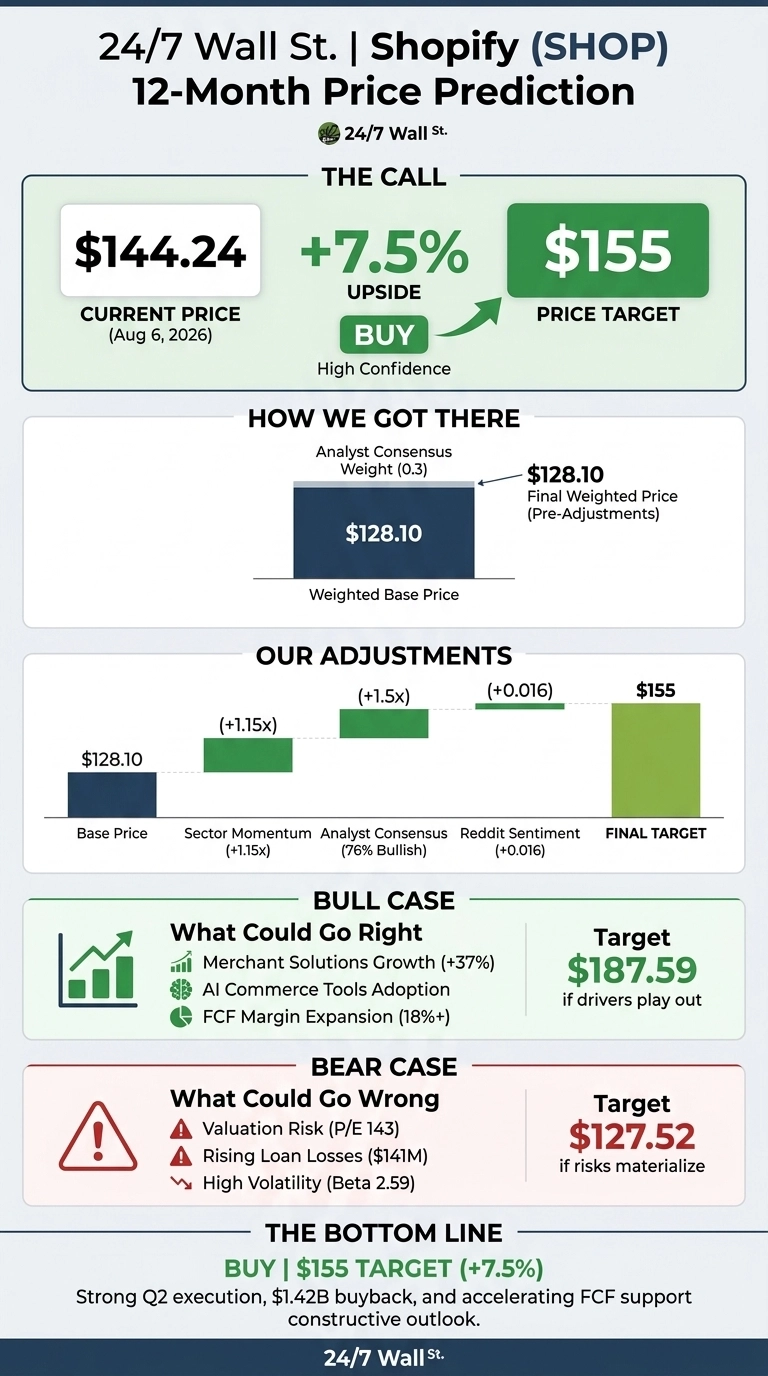
Our 24/7 Wall St. price target for Shopify is $155 over the next 12 months, implying roughly 7.5% additional upside from current levels. Our research framing leans constructive on the setup.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $144.24 |
| 24/7 Wall St. Price Target | $155 |
| Upside | ~7.5% |
| Research Stance | Constructive |
| Confidence Level | 75% |
Shopify was already showing signs of strong execution. The Q2 blowout, paired with a $1.42 billion buyback and accelerating free cash flow, transforms this into a compounding cash generator.

The Blowout That Reset the Narrative
Shopify posted Q2 2026 revenue of $3.58 billion, up 33.69% year over year, with GMV of $115.57 billion (+32%). Merchant Solutions revenue jumped 37% to $2.78 billion, operating income climbed 67.7% to $488 million, and free cash flow of $654 million represented an 18% margin.
The stock rallied 20.06% over the past month but remains -10.39% YTD and 19% below its 52-week high of $182.19.
Why Bulls See a Breakout Above $180
The bull case rests on operating leverage. Merchant Solutions compounds at 37% while OpEx as a share of revenue stays disciplined at 33% to 34%.
B2B GMV grew 96% in 2025, Shop Pay GMV rose 62%, and AI products like Sidekick and the Universal Commerce Protocol provide defensible edges as agentic commerce accelerates. The bull scenario targets a 1-year price of $187.59, a 30% return. Consensus sits at $148.39 with 10 Strong Buy ratings.

What Could Go Wrong
Valuation is the primary risk. Shopify trades at a P/E of 143 and an implied forward P/E of 101, with a beta of 2.59. Transaction and loan losses ballooned to $141 million from $80 million a year earlier as Shopify Capital scales.
Bulls counter that these losses reflect a $1.35 billion loan portfolio and remain a small fraction of GMV. After Q2 2025’s +21.97% earnings spike, shares fell -5.60% over the next 30 days. The bear scenario points to $127.52.
How Shopify Compares to Amazon and BigCommerce
Amazon (NASDAQ:AMZN) defines the ceiling on ecommerce economics. Amazon’s marketplace pressures Shopify on shipping and fulfillment, but Shopify’s merchant-friendly model produces gross margins of 48.07%, well above Amazon’s retail businesses. That margin gap explains why the market pays a premium P/E for SHOP and why $155 remains defensible.
BigCommerce (NASDAQ:BIGC) is the closest pure-play SaaS ecommerce comp. BigCommerce grows in the single digits and trades at a fraction of Shopify’s multiple. Shopify’s 33.69% revenue growth and 18% FCF margin justify the spread. Against this peer set, our $155 target looks reasonable.
Shopify Price Prediction 2026-2030
Our 24/7 Wall St. price target of $155 reflects a business that accelerated growth, expanded margins, and returned $1.42 billion to shareholders in a single quarter.
The setup looks constructive if Q3 lands inside the low-thirties revenue growth guide and FCF margins stay above 18%. The thesis weakens if loan losses continue to double year over year or if the stock retests its 52-week high without earnings support.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $155 |
| 2027 | $175 |
| 2028 | $198 |
| 2029 | $222 |
| 2030 | $248 |
These projections assume Shopify executes on its current strategy, with revenue compounding in the mid-twenties and FCF margins holding near 20%.
Upside could come from AI-native commerce adoption and enterprise wins, while a consumer spending recession or lending losses would pressure the trajectory. The internal model’s 5-year base case sits at $169.02, with a bull case of $273.21.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.