Forget Chips: This Analyst Says 4 “Old School” Themes Could Be the Real AI Industrialization Winners
A top Wall Street analyst says investors chasing chip stocks are looking at the wrong part of the AI trade entirely, and she is pointing to four industrial names that could capture the real windfall from a $5 trillion infrastructure…

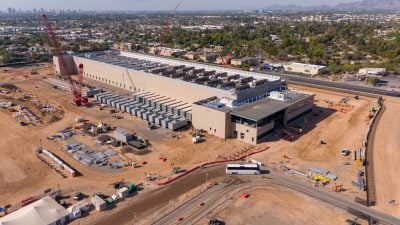
Kathryn Thompson, Partner and CEO of Thompson Research Group, appeared on CNBC on Thursday morning to help reframe the way investors think about AI. Her argument: markets are obsessing over near-term chip pricing while missing a historically massive industrial rebuild sitting behind it. “Just the projected spend over the next five years, $5+ trillion dollars, that is more than the combined spend for the interstate system, the electrification of the US, and the buildout of the US rail systems,” Thompson said.
The near-term constraints, she argued, sit outside the data center itself. “Power is the bottleneck right now. It will be solvable, but it’s going to take time. Financing is a big question mark,“ she noted, adding that water challenges are largely solvable. Her takeaway for investors was direct: “You might want to shift and look at really more old-school type names.”
Martin Marietta: The Raw Materials Behind the AI Boom
Martin Marietta Materials (NYSE:MLM | MLM Price Prediction) appears to fit the “old school” theme Thompson cited. Q2 FY2026 revenue reached $1.947 billion, up 7.5% year-over-year, with adjusted EPS of $5.00 and record aggregates shipments of 61.6 million tons. CEO Ward Nye pointed to “accelerating momentum in data centers and energy” as a key demand driver.
The company also announced a $13.5 billion acquisition of Lhoist North America, financed in part by a $1.5 billion three-year senior unsecured term loan, illustrating exactly the capital intensity Thompson flagged. Shares are down 12.41% year-to-date, trading at a forward P/E of 29.
CRH: A Direct Bet on America’s Reindustrialization
CRH (NYSE:CRH) has cited the AI infrastructure theme directly. CEO Jim Mintern pointed to “significant public investment in infrastructure and continued reindustrialization activity.” Q1 FY2026 revenue was $7.37 billion, up 18.1%, with Americas aggregate volumes up 14% and cement up 10%.
The stock is down 20.9% year-to-date, trading at a forward P/E of 17, a valuation that stands out for the AI tailwinds the company can capture.
Ferguson Enterprises: The Distribution Pipeline
Ferguson Enterprises (NYSE:FERG) sits at the plumbing and water infrastructure layer feeding data centers and factories. Q2 FY2026 revenue hit $8.75 billion, with non-residential revenue up 8% on large capital project activity.
CEO Kevin Murphy cited “water infrastructure, large capital projects, climate and comfort, and aging and underbuilt housing” as durable demand drivers. It’s expected that YTD acquisition activity totals roughly $1.4 billion in annualized revenue.
Generac: A Pure Play on AI’s Power Bottleneck
If power is the constraint, Generac Holdings (NYSE:GNRC) could be a direct beneficiary. Q2 FY2026 revenue rose 10.6% to $1.173 billion, with the Commercial & Industrial segment up 29% to $556.5 million. The data center backlog now stands at roughly $1.6 billion, and a second hyperscale supply agreement was signed.
CEO Aaron Jagdfeld said the company is “investing aggressively in incremental production and packaging capacity for large megawatt generators.” Shares are up 62.72% year-to-date.
Cisco Shows How Quickly AI Infrastructure Can Be Repriced
Thompson noted Cisco shares are up over 60% this year despite current weakness. Cisco Systems (NASDAQ:CSCO) reported Q4 FY2026 revenue of $17.25 billion and guided FY2027 AI infrastructure revenue to nearly double to $7.5 billion.
Thompson’s investor angle is that the distribution and power layers have not yet been repriced for the expected $5 trillion demand curve coming over the next 5 years.
Contact [email protected] for any questions or corrections.
Thomas Richmond is a financial writer and content strategist with 5+ years of experience covering stocks and financial markets. He has published over 500 articles focused on individual stock analysis, helping investors better understand business fundamentals, stock valuations, and long-term opportunities.
Thomas previously served as a Content Lead at TIKR, a stock research platform, where he helped scale the company’s blog to hundreds of articles per month and contributed to a weekly newsletter reaching more than 100,000 investors.
Outside of work, Thomas enjoys weight lifting and soccer.