One AI Stock I’d Watch Before Nvidia’s Earnings
Micron has surged nearly 675% in a year as Nvidia's top memory supplier, but with Nvidia's earnings report arriving this week, a single guidance line could either push MU toward four digits or trigger a swift reversal.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Micron Technology (NASDAQ:MU | MU Price Prediction) sits at the center of the AI memory trade. With NVIDIA (NASDAQ:NVDA) reporting later this week, the setup for its lead HBM supplier warrants careful pricing. Micron has run from the mid $120s a year ago to $910.43, and our proprietary model sees room to run into the earnings report.
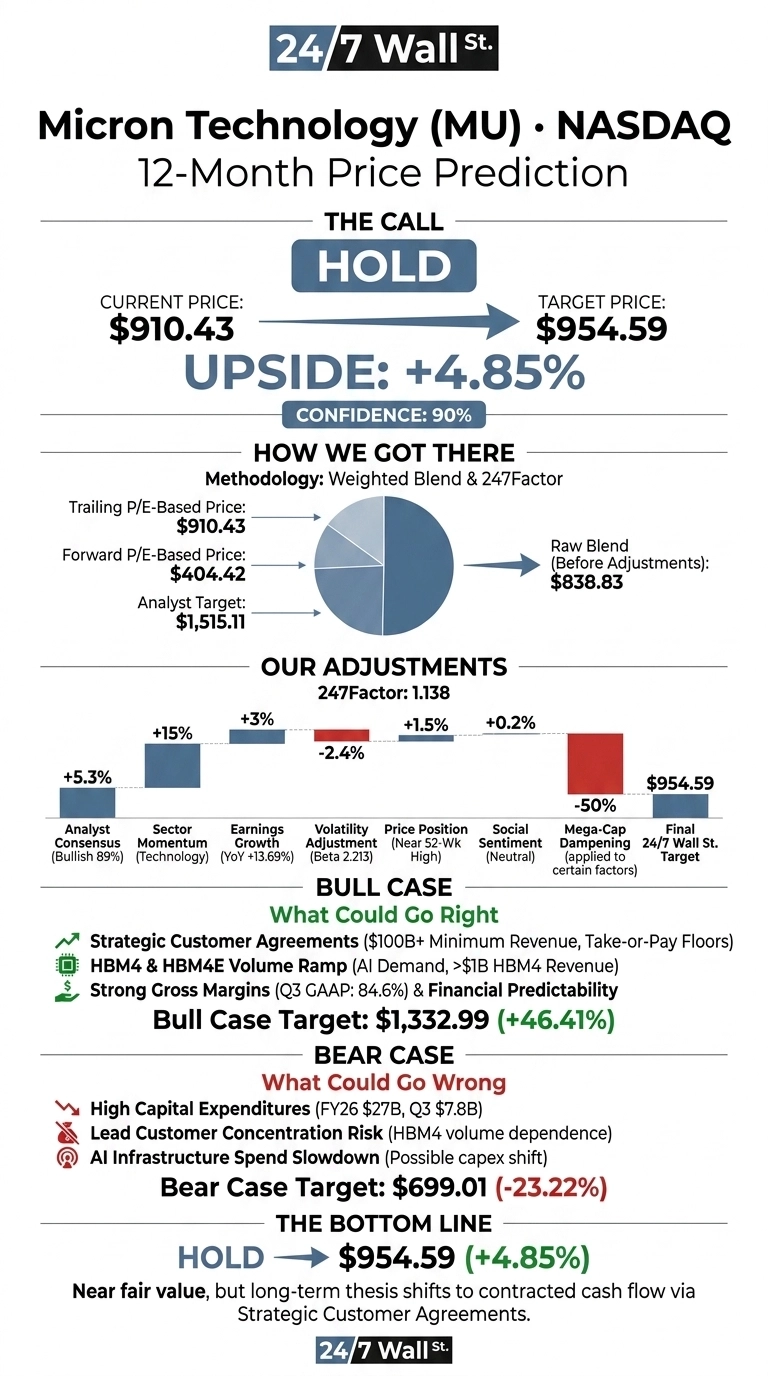
Our 24/7 Wall St. price target for Micron is $954.59 over the next 12 months, implying 4.85% upside from Monday’s close. The model returns a hold at high confidence (90%), reflecting a stock near fair value after a violent revaluation but tethered to the strongest memory cycle on record.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $910.43 |
| 24/7 Wall St. Price Target | $954.59 |
| Upside | 4.85% |
| Recommendation | HOLD |
| Confidence Level | 90% |
From $120 to $900 in a Year
Micron is up 674.9% over the past year and 219.19% year to date, but has cooled recently, falling 10.01% in the past week and 5.83% in the last session. It trades roughly 21% below its 52-week high of $1,254.81.
Fiscal Q3 revenue landed at $41.5 billion, up 346% year over year, with non-GAAP EPS of $25.11 beating consensus by 23.79%. Fiscal Q4 guidance calls for $50 billion in revenue and $31 in EPS at the midpoint. Retail sentiment on Reddit has cooled to neutral heading into Nvidia’s print.
Why Bulls See a Breakout Ahead
Management’s tone was aggressive. CEO Sanjay Mehrotra said “the memory industry has been structurally transformed by the proliferation of AI” and that “we see tightness persisting beyond 2027.”
The company has signed 16 Strategic Customer Agreements covering roughly 20% of DRAM volume and a third of NAND volume, with take-or-pay floors that CFO Mark Murphy said produce margins “significantly above prior peak margins.”
HBM4 12-high shipments are ramping twice as fast as HBM3E, with over $1 billion in HBM4 revenue already booked. The bull case scenario points to $1,332.99, a 46.41% return. The Street’s $1,515.11 consensus sits higher, with 9 Strong Buys, 31 Buys, and zero Sells.

Risks Worth Watching
Capex is exploding. Q3 burned $7.826 billion, with fiscal Q4 capex guided to roughly $10 billion and full-year FY26 spend near $27 billion. HBM4 concentration on a single lead customer amplifies Nvidia risk. A soft Nvidia guide could compress memory multiples fast.
Micron’s average one-week post-earnings change is -3.44% despite 8 beats and 0 misses. Bulls counter that the $100 billion minimum SCA revenue backlog and $18 billion in incoming cash deposits materially blunt cyclicality. Our bear case flags $699.01, or a 23.22% drawdown.
How Micron Compares to NVIDIA and Western Digital
NVIDIA is the demand engine. It trades at a P/E of 43 with Q1 FY27 revenue up 85.2% to $81.61 billion. Micron’s 6 forward multiple looks strikingly cheap against NVIDIA given similar exposure to AI infrastructure spend (we profiled seven non-chipmaker suppliers powering that same buildout in a free report here: 7 Stocks Powering the AI Boom).
Western Digital (NASDAQ:WDC), the pure-play HDD peer riding the same AI storage tailwind, posted fiscal Q4 revenue of $3.75 billion, up 43.8% year over year, with non-GAAP gross margins at 54.4%. Micron’s 84.9% non-GAAP gross margin dwarfs both. That combination of higher margins and lower forward multiple makes our $954.59 target look conservative relative to peers.
| Company | Forward P/E | Gross Margin |
|---|---|---|
| Micron | 6 | 84.9% |
| NVIDIA | N/A | 75.0% |
| Western Digital | N/A | 54.4% |
Micron Price Prediction 2026-2030

The 24/7 Wall St. price target is $954.59 with a hold rating at 90% confidence. The SCA backlog converts memory from a boom-bust asset into contracted cash flow.
The setup improves if Nvidia reiterates gigawatt-scale AI capex guidance and Micron re-tests $1,000. The setup weakens if HBM4 pricing shows softness in the earnings report.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $954 |
| 2027 | $1,010 |
| 2028 | $1,065 |
| 2029 | $1,115 |
| 2030 | $1,158 |
These projections assume Micron continues executing SCAs on schedule and HBM4E reaches volume production in calendar 2027. Significant upside or downside could result from a shift in AI capex or a change in the HBM lead-customer relationship.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.