Up 500% In 12 Months, This is Where Micron Is Headed
Micron just delivered the most jaw-dropping quarter any US semiconductor company has posted this cycle, yet the stock is sliding and analysts are at war over what comes next. Where the smart money lands may surprise you.

Micron Technology (NASDAQ:MU | MU Price Prediction) has become the most extraordinary story in semiconductors this year. Shares are up 512.68% over the past 12 months and 240.59% year to date, riding a memory super-cycle that most bulls did not price in until it was already unfolding.
Our 24/7 Wall St. price target for Micron is $949.19, which sits just below the current quote of $971.48. That implies roughly 2.3% of downside, and our model rates the stock a hold with 90% confidence.
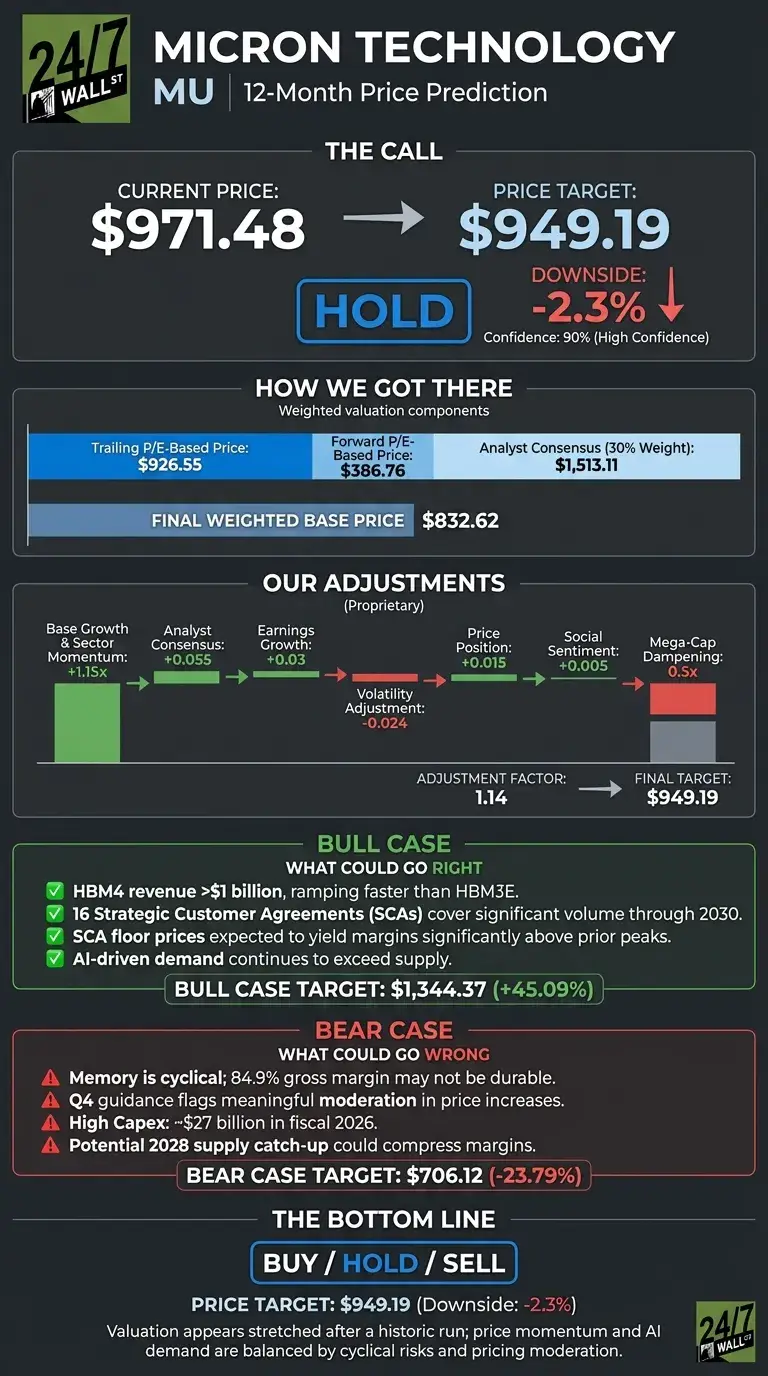
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $971.48 |
| 24/7 Wall St. Price Target | $949.19 |
| Upside/Downside | -2.3% |
| Recommendation | HOLD |
| Confidence Level | 90% |

Why We Could Be Wrong
Before diving in, we should note that our 24/7 Wall St. price target sits just below where Micron trades today. This is one of the most divisive stocks in the market.
Real upside could come from HBM4 share gains at a lead AI accelerator customer, or from the 16 Strategic Customer Agreements pushing realized pricing well above the contractual floors. Consider our target one datapoint among many. A full bull case appears below.
A Memory Super-Cycle in Full Force
Fiscal Q3 2026 was arguably the most impressive quarter any US semiconductor company has reported this cycle. Revenue reached $41.456 billion, growing 345.72% year over year and beating estimates by 17.6%. Non-GAAP EPS of $25.11 beat by 23.79%, GAAP gross margin expanded to 84.6%, and free cash flow hit $18.304 billion.
Management guided Q4 revenue to $50 billion and EPS to $31. Still, MU is down 5.48% over the past week as investors debate how much of this cycle is already priced in, a debate Barron’s flagged this week as competitive pressure builds on US memory supremacy.

Bull Case: A Path to $1,340+
Bulls have a very real path here. Micron has already shipped over $1 billion in HBM4 revenue, with the 12-high ramp tracking twice as fast as HBM3E. The 16 SCAs cover roughly 20% of DRAM and a third of NAND volume through 2030, with minimum cumulative revenue of approximately $100 billion and floor prices that generate margins “significantly above prior peak margins.”
Analyst consensus already sits at $1,513.11, and our own bull scenario points to $1,344.37 over 12 months if pricing holds and supply stays tight, a view MarketWatch echoed this week with a 70% upside call.

What Could Go Wrong
The bear case is straightforward: memory is cyclical, and Micron just reported an 84.9% non-GAAP gross margin that no sane analyst models as durable. Q4 guidance already flags “a meaningful moderation in the rate of price increases.” Capex is running at approximately $27 billion for fiscal 2026, and any 2028 supply catch-up would compress margins hard.
Our bear scenario pegs downside at $706.12, a 23.79% drop. Bulls would fairly counter that SCA floor pricing and take-or-pay commitments materially blunt the classic memory downcycle for the first time in industry history.
How Micron Compares to Western Digital and Seagate
Micron does not have a perfect US-listed pure-play memory peer, but the storage-infrastructure names offer the best available lens on AI-driven cyclical demand.
Western Digital (NASDAQ:WDC) just reported fiscal Q4 revenue of $3.747 billion, up 43.84% year over year, with non-GAAP EPS of $3.56 and gross margin of 54.4%. WDC’s growth is impressive but a fraction of Micron’s, which frames MU’s premium as earned.
Seagate Technology (NASDAQ:STX) posted fiscal Q4 revenue of $3.629 billion, up 48.49% year over year, with EPS of $5.71 and Q1 FY27 EPS guidance of $7.30. STX is riding the same hyperscaler AI storage build-out, but at a much smaller scale of expansion.
Set against peers growing 40% to 50%, Micron’s triple-digit revenue growth and 80%+ margins make our $949 target look reasonable rather than aggressive.
Micron Price Prediction 2026-2030
My verdict on Micron is hold, with 90% confidence in our 24/7 Wall St. price target of $949.19. The tipping factor is valuation math: at $971, the forward P/E anchor is already stretched, and Q4 guidance quietly warns that peak pricing is moderating.
A pullback toward $850, or evidence that HBM4 share is expanding beyond current customers, would materially strengthen the bull case. Conversely, margins normalizing faster than the SCA floor prices can protect would weaken it.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $949 |
| 2027 | $1,023 |
| 2028 | $1,062 |
| 2029 | $1,085 |
| 2030 | $1,117 |
These projections assume Micron continues executing on HBM roadmap milestones and that SCA floor pricing holds. Meaningful upside or downside could result from AI infrastructure capex trajectory and the timing of any 2028 supply catch-up. Memory is only one slice of that buildout, and we mapped seven other suppliers riding the same wave, from power to cooling to networking, in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.