Palantir Stock Could Be in for a Big September. Here’s Why.
Palantir just delivered one of the most explosive earnings reports in enterprise tech history, and September options positioning suggests traders are bracing for another major move. The question is whether the fundamentals justify what happens next.

Palantir is entering September on a tear. The stock ripped 43.09% higher over the past month after a blowout Q2 earnings report, and options positioning around the September 18 expiration is unusually heavy. Momentum has room to run, though the setup carries risk.
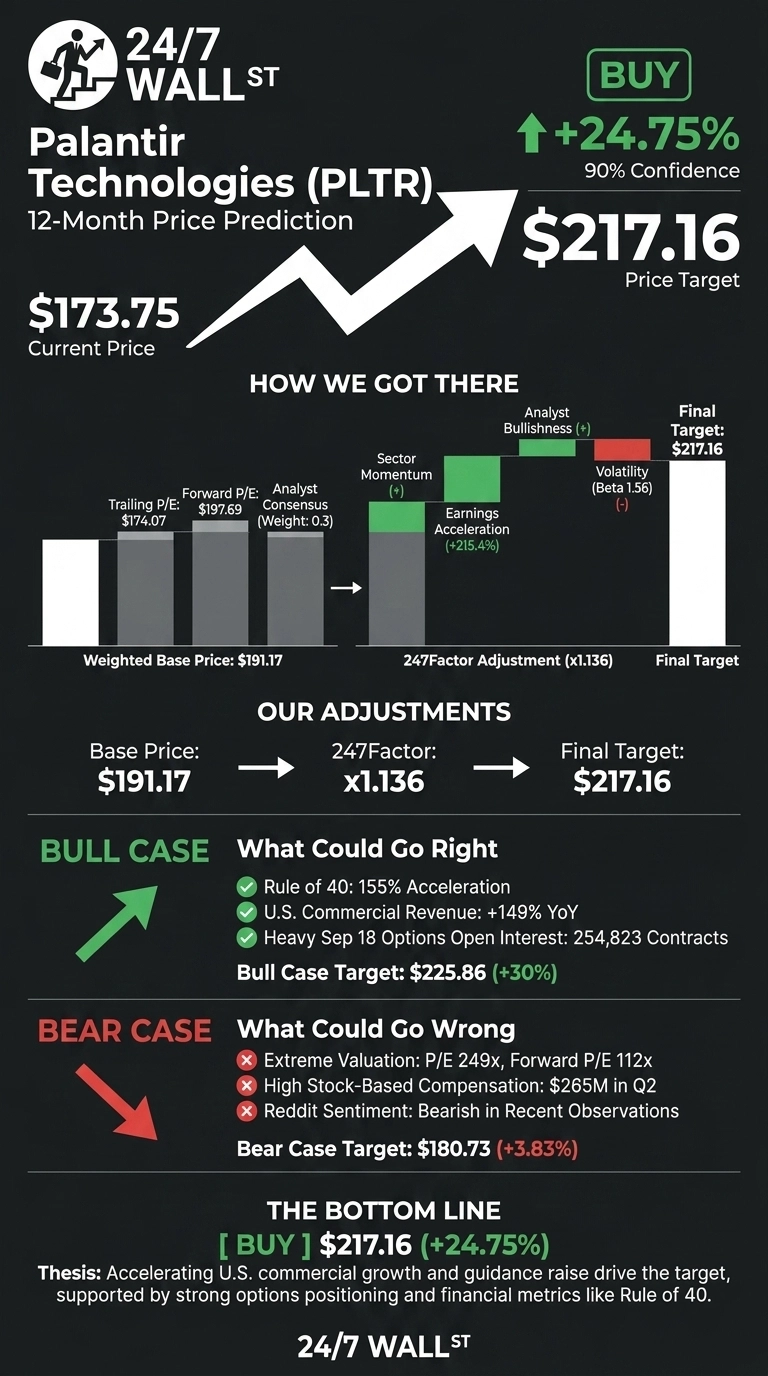
Palantir (NASDAQ:PLTR | PLTR Price Prediction) currently trades at $173.75. Our 24/7 Wall St. price target is $217.16 over the next 12 months, implying 24.75% upside. Our rating skews constructive at 90% confidence. Rule of 40 acceleration, raised full-year guidance, and September options positioning give this setup real teeth.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $173.75 |
| 24/7 Wall St. Price Target | $217.16 |
| Upside | 24.75% |
| Recommendation | BUY |
| Confidence Level | 90% |
Momentum Is Real, and the Q2 Report Was Otherworldly
PLTR is up 1.94% over the past week and 10.8% over one year, though year-to-date the stock is essentially flat at -1.05%. Shares sit roughly $33 below the 52-week high of $207.52.
The catalyst was Q2 FY2026 earnings on August 3. Revenue grew 93% to $1.935B, EPS came in at $0.41 versus a $0.28 estimate, and U.S. commercial revenue exploded 149% year over year. Palantir raised full-year revenue guidance to $8.154 billion at the midpoint, what management called its “largest-ever full-year revenue guidance raise.”
Case for $225 and a Breakout September
Bulls have substantial support. September options positioning is heavy: the September 18 expiration carries call open interest of 254,823 contracts, suggesting traders price in a large directional move. Fundamentally, Rule of 40 hit 155%, net dollar retention jumped to 157%, and adjusted free cash flow margin ran at 63%.
CEO Alex Karp said “Demand for AI sovereignty has now been unleashed” and committed to keeping company-wide growth at or above U.S. commercial rates for the next 18 months. Our bull case points to $225.86, roughly 30% above today.

Risks Worth Watching
Valuation is extreme. PLTR trades at a P/E of 249 and forward P/E of 112. Stock-based compensation of $265 million in Q2 alone continues diluting holders, though bulls argue this reflects aggressive hiring to sustain 82% guided revenue growth.
Post-earnings history is choppy: Q1 26 and Q4 25 both saw negative one-week reactions despite beats. Reddit sentiment turned bearish in every recent observation, and composite sentiment sits at 45.37, neutral. Our bear case puts the stock at $180.73 over 12 months.

How Palantir Compares to ServiceNow and Snowflake
Two U.S.-listed enterprise AI platforms belong in the conversation. ServiceNow (NYSE:NOW) is the closest peer on “AI control tower” positioning, with Q2 FY2026 revenue of $3.99 billion growing 24% and ServiceNow AI crossing $1 billion in annual contract value. PLTR grows roughly four times as fast, supporting our target’s premium valuation.
Snowflake (NYSE:SNOW) is the data-platform counterpoint. SNOW grew Q1 FY2027 revenue 33.5% and remains GAAP unprofitable with a market cap of $109.6B, versus Palantir’s $399.75B. Palantir is the only one of the three producing GAAP net income at scale, making our price target look reasonable on a growth-adjusted basis.
| Company | Revenue Growth YoY | Market Cap |
|---|---|---|
| Palantir | 92.83% | $399.75B |
| ServiceNow | 24.0% | $131.1B |
| Snowflake | 33.5% | $109.6B |
Why the September Setup Looks Compelling
The 24/7 Wall St. price target of $217.16 and buy rating at 90% confidence reflect accelerating growth, guidance raises, and heavy September options positioning. The tipping factor is U.S. commercial trajectory.
The bullish case strengthens if Palantir sustains Rule of 40 above 140 and September commentary points to continued AIP adoption. The setup weakens if stock-based compensation growth outpaces revenue growth or if the multiple compresses below 100x forward.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $189.51 |
| 2027 | $217.16 |
These projections assume Palantir continues executing on its U.S. commercial and sovereign AI playbook. Significant upside or downside could result from federal contract wins, competitive shifts in enterprise AI, or software multiple compression. For readers hunting the next monster tech winner early, we reverse-engineered what past 100x runs looked like before the headlines in a free playbook here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.