Figma Stock Price Prediction: Wall Street’s $30 Target May Be Too Low
Figma has lost more than half its value since IPO even as revenue growth accelerated, creating a rare tension between a beaten-down chart and fundamentals that are quietly getting stronger. Here is why the setup may be more interesting than…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Figma (NYSE:FIG) has been one of the most whiplash-inducing stories in software this year. After IPO’ing to euphoria, the stock is now down 61.26% over the past year and 27.03% year to date, even as revenue growth accelerated to 48% year over year in Q2. Wall Street’s consensus target sits at $30.80. I think that number is too conservative.
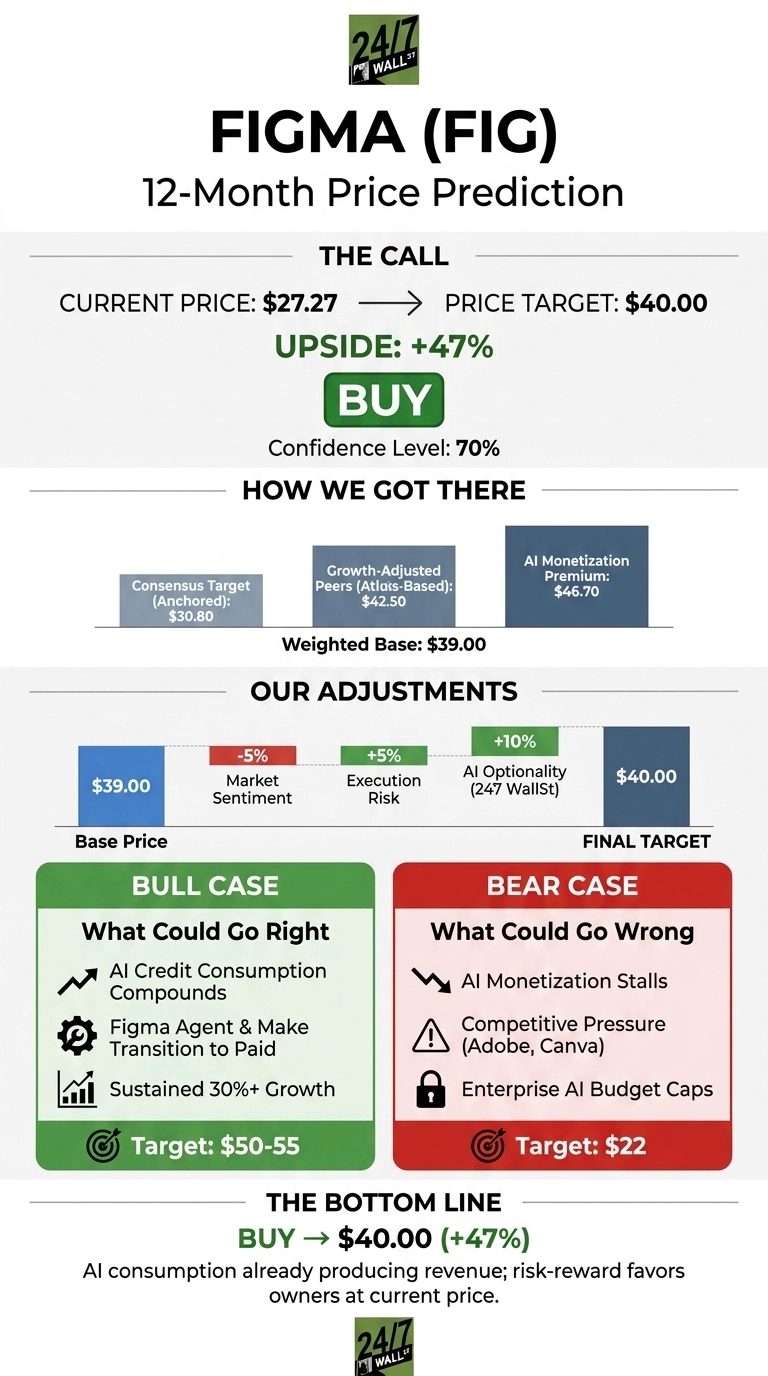
Figma currently trades at $27.27. Our 24/7 Wall St. price target for Figma is $40 over the next 12 months, implying roughly 47% upside. Our research view is constructive, with moderate-to-high confidence given the pace of AI monetization and the fact that the sell-off has compressed the multiple meaningfully.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $27.27 |
| 24/7 Wall St. Price Target | $40.00 |
| Upside | 46.7% |
| Research View | Constructive |
| Confidence Level | 70% |
How a 48% Grower Ended Up in the Bargain Bin
Figma’s chart tells a story of expectations collision. Shares hit a 52-week high of $72.11 and a low of $16.60 within the same year. Recent price action has been constructive, with FIG up 29.12% over the past month and 4.84% in the last week.
In Q2, Figma delivered $370 million in revenue, a net dollar retention rate of 136%, and non-GAAP operating income of $36 million. Management raised the full-year outlook to $1.463 billion to $1.467 billion, an increase of $40 million. The disconnect between fundamentals and price is the setup.
Why Bulls See a Breakout to $50+
The bull thesis is straightforward: Figma is turning into an AI infrastructure story with a design front-end. Approximately 80% of customers with more than $10,000 in ARR were drawing down AI credits weekly, and more than 50% of paid customers with more than $10,000 in ARR were using the Figma agent weekly. Paid customers with over $100,000 in ARR grew 46% year-over-year.
CEO Dylan Field said “the opportunity is bigger than even we expected“. Non-GAAP gross margin held at 85%, and free cash flow was $53 million for the quarter. If AI credit consumption compounds through 2027 and Figma Agent, Make, and Code Layers transition from beta to paid, a $50 to $55 stock is within reach.
Risks Worth Watching
Figma trades at 11.41x trailing sales and a forward P/E of 93x. Reported EPS is -$4.4, and TTM operating margin is -31.7%. Bulls counter that GAAP results reflect stock-based compensation from a recent IPO and heavy AI investment, while non-GAAP operating margin was 10% in Q2.
Competitive pressure from Adobe, Canva, and AI-native coding tools is real. A downside scenario, where AI monetization stalls, points to $22.
How Figma Compares to Adobe and Atlassian
Adobe (NASDAQ:ADBE | ADBE Price Prediction) is the incumbent competitor and natural valuation anchor. Adobe trades at a forward P/E of 10x and P/S of 4x, but revenue grew just 12.7% last quarter. Figma is growing nearly 4x faster, warranting a premium, but the size of that premium is the debate.
Atlassian (NASDAQ:TEAM) is a better growth-oriented comparable. TEAM sports a forward P/E of 32x, a P/S of 6.6x, and revenue growth of 27.6%. Figma grows faster and carries higher gross margin, supporting pricing above TEAM’s multiple. On that framing, the 24/7 Wall St. price target of $40 looks reasonable rather than aggressive.
| Company | Forward P/E | Revenue Growth YoY |
|---|---|---|
| Figma | 93x | 48% |
| Adobe | 10x | 12.7% |
| Atlassian | 32x | 27.6% |
Where the Risk-Reward Points
The 24/7 Wall St. price target is $40, the research view is constructive, and confidence is 70%. The factor tipping the scale is AI credit consumption, already producing revenue rather than sitting in a roadmap.
The bull case rests on whether Figma Agent and Make can compound weekly usage into 2027. The bear case assumes enterprises will cap AI budgets and lean on coding-first tools instead. On balance, the risk-reward at $27.27 favors owners.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $40 |
| 2027 | $52 |
| 2028 | $64 |
| 2029 | $76 |
| 2030 | $88 |
These projections assume Figma continues executing on AI monetization and sustains 30%-plus revenue growth through 2028. Significant upside or downside could result from acceleration or stalling of Figma Agent adoption and enterprise credit expansion.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.