Every Analyst Covering Webull Says Buy. We Disagree.
Wall Street analysts are unanimous on Webull, and unanimously bullish. Here is why our model lands in a completely different place and what would have to happen for us to change our minds.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Webull (NASDAQ:BULL | BULL Price Prediction) has one of the tidiest analyst scorecards in the market. Three buys, zero holds, zero sells, and a consensus target of $14.33. We are going the other way.
Our 24/7 Wall St. price target for Webull is $9.52, essentially where the stock closed at $9.57 on August 27. That implies a -0.48% return over the next 12 months and a hold rating with 90% model confidence. In plain English: the easy money has been made.
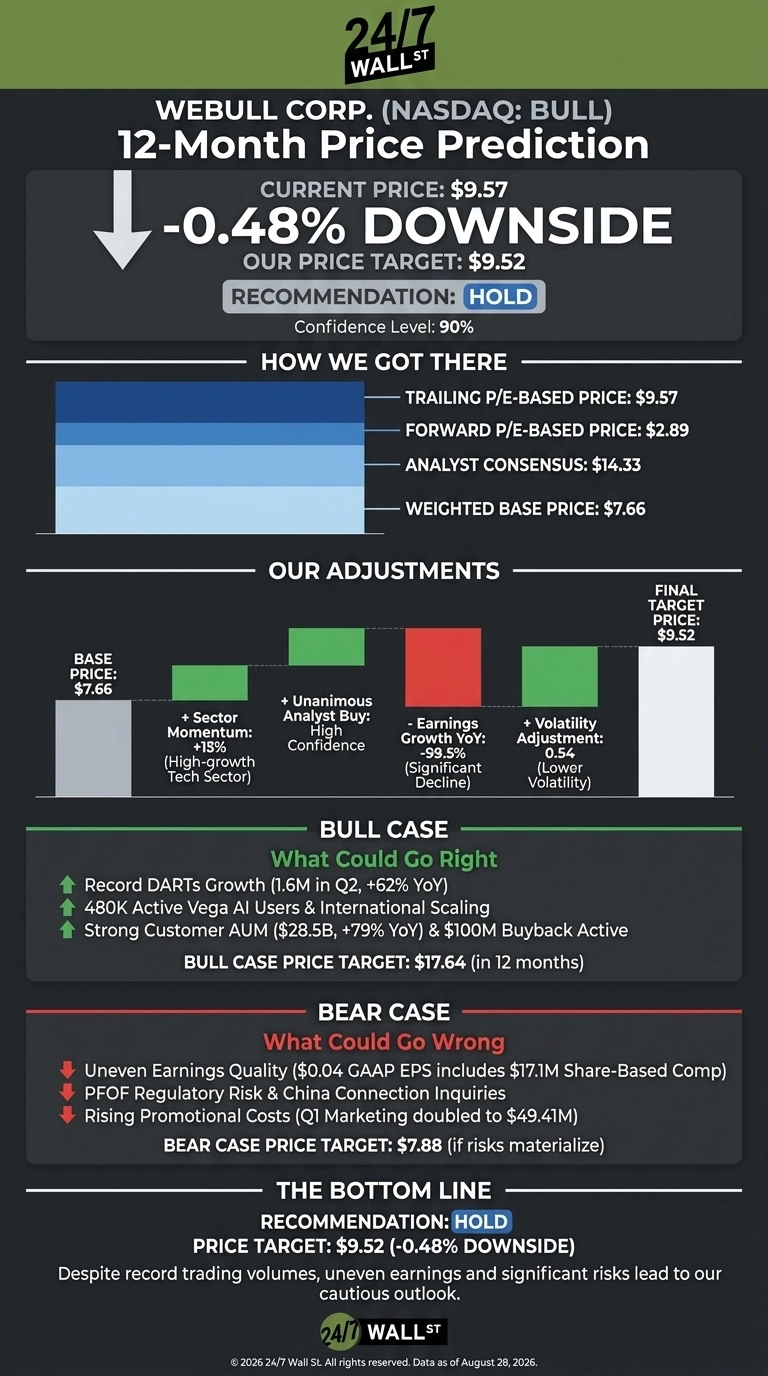
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $9.57 |
| 24/7 Wall St. Price Target | $9.52 |
| Upside/Downside | -0.48% |
| Recommendation | HOLD |
| Confidence Level | 90% |

Why We Could Be Wrong
Webull posted a strong Q2, and the June 4 elimination of the Pattern Day Trader rule appears structural. Real upside could come from durable DART growth or the Pi Securities Thailand acquisition scaling APAC assets faster than modeled. A fuller bull case follows below.
Setup Heading Into Q3
BULL has been a momentum name, up 8.14% in the past week, 31.64% in the past month, and 23.17% year to date. It remains down 33.73% over the past year and well off the 52-week high of $16.04.
The rerating was driven by Q2 results: revenue of $198.83 million, up 51%, beating consensus by 8.75%, GAAP EPS of $0.04 versus $0.025 expected, and record DARTs of 1.6 million. CEO Anthony Denier called the PDT change Webull’s “defining event for the quarter”.
Bull Case for $17+
Bulls have a real story. Trading-related revenue jumped 66% to $147.7 million, options volume hit 213 million contracts, and customer AUM grew 79% to $28.5 billion. Management believes PDT removal “will not revert” and said “August is looking even stronger than July”.
Add 480,000 Vega AI users, the Pi Securities deal, and a $100 million buyback already active at $6.03. The all-buy analyst target of $14.33 reflects that thesis. A bull-case scenario reaches $17.64 in 12 months if trading intensity holds.

What Could Go Wrong
Trailing P/E of 15x looks cheap, but earnings quality is uneven. Q2 GAAP EPS of $0.04 included $17.1 million in share-based comp and $3.9 million in FX losses. Q4 2025 missed EPS by 80% and Q1 2026 posted a $21.72 million net loss. Payment for order flow regulatory risk and government inquiries over China ties are real.
Bulls counter that the 1,031% YoY operating-income growth and 97.3% retention reflect a fundamentally healthier business. Our bear scenario lands at $7.88.
How Webull Stacks Up Against Robinhood and Interactive Brokers
Robinhood (NASDAQ:HOOD) is the direct retail comp. HOOD posted Q2 2026 revenue of $1.31 billion and EPS of $0.62, at an $86.8 billion market cap. Webull trades near $4.65 billion, roughly 7% of HOOD’s cap on roughly 15% of revenue. That gap supports our target as reasonable.
Interactive Brokers (NASDAQ:IBKR) is the profitability yardstick. IBKR generated Q2 2026 revenue of $1.90 billion at a 77% pretax margin with $930 billion in customer equity. Webull’s 31.5% adjusted operating margin is respectable but not premium. The peer set argues BULL is fairly priced.
Webull Price Prediction 2026-2030
Our $9.52 target says the good news is priced in. We would buy if BULL sustained Q2’s trading intensity into Q3 and pushed forward EPS meaningfully above $0.08. We would stay on the sidelines if PFOF headlines resurface or Q3 DARTs slip. For now, a hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $9.52 |
| 2027 | $9.75 |
| 2028 | $10.10 |
| 2029 | $10.45 |
| 2030 | $10.80 |
These projections assume Webull continues executing on its PDT-era trading tailwind and international expansion. Significant upside or downside could result from PFOF regulation or a step-change in Vega AI adoption.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.