Investors Are Looking Beyond the Magnificent Seven. Could This Be the Next AI Giant?
Palantir just posted a 51% single-month surge and the kind of revenue guidance that has analysts scrambling to revise their models, yet the stock still trades near Wall Street's consensus target. Here is whether the math actually supports a path…

Investors hunting for the next mega-cap AI winner keep circling back to Palantir (NASDAQ:PLTR | PLTR Price Prediction), the software company that has quietly built one of the most profitable AI franchises outside the Magnificent Seven.
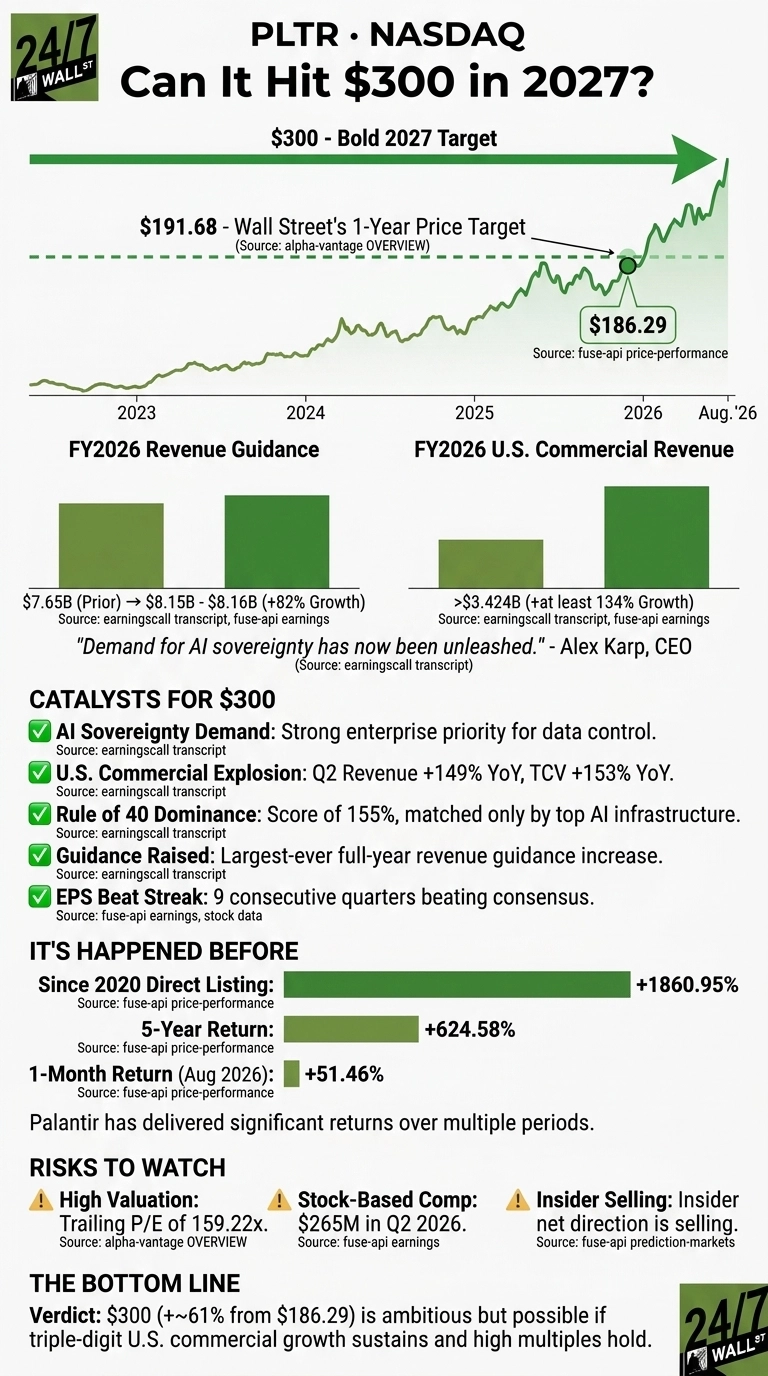
Shares are up just 4.8% year-to-date, but that masks a violent recovery: PLTR has ripped 51.46% in the past month alone after a blowout Q2 report, and shares now sit at $186.29. With CEO Alex Karp declaring that “demand for AI sovereignty has now been unleashed”, the question is whether Palantir can push to $300 per share in 2027.

Wall Street Is Warming Up, But Not Fast Enough
The Street’s consensus 12-month price target sits at $191.68, barely above today’s quote, with 20 buy ratings, 10 holds, and 2 sells. That caution reflects valuation anxiety more than business skepticism.
Palantir just guided full-year 2026 revenue to $8.15 to $8.158 billion, an 11-point increase over prior guidance and the largest-ever raise. U.S. commercial revenue is now guided to grow at least 134% for the year. Analysts are chasing the numbers higher.

Path to $300: Doing the Math
At $186.29, Palantir trades at a forward P/E of roughly 115x and a price-to-sales multiple of 73x. To reach $300, shares would need to gain about 61%. If revenue compounds at management’s target pace (Karp said he is “driving the business to grow at a rate equal or above to what we have in U.S. commercial for the next 18 months”), 2027 revenue could exceed $14 billion.
At $300, that would work out to roughly 50x sales, rich but consistent with today’s multiple on a much larger base.
What could push PLTR to $300?
- Beat streak: Palantir has topped consensus EPS nine straight quarters, including a 46.43% Q2 beat.
- Rule of 40 dominance: A 155 Rule of 40 score puts PLTR in the same bucket Karp compared to NVIDIA (NASDAQ:NVDA), Micron (NASDAQ:MU), and SK hynix.
- Commercial explosion: U.S. commercial TCV hit $2.132 billion, up 153% year-over-year, with net dollar retention of 157%.
- Defense tailwind: Palantir’s Pentagon revenue is still less than 25 basis points of the DoD budget, leaving massive runway.
- Retail conviction: Reddit sentiment around Q2 hit 95 on r/wallstreetbets, categorized as very bullish.
History Says 61% Gains Are Not Crazy for PLTR
Palantir has returned 624.58% over five years and 1,860.95% since its 2020 direct listing. A 61% year would rank as merely a strong one by PLTR’s standards. The stock’s 1.56 beta and 51% one-month move both underline how quickly sentiment can shift in Palantir’s favor.

Verdict on $300: A Stretch Goal With Real Support
Hitting $300 requires Palantir to keep beating estimates, sustain triple-digit U.S. commercial growth, and hold its premium multiple as revenue compounds.
Risks are real: $265 million in quarterly stock-based comp, a 159x trailing P/E, and insider selling. But with sovereign AI adoption accelerating and guidance climbing every quarter, we’ve outlined the blueprint for how PLTR could see outsized returns in 2027. The traits that showed up years before the biggest tech runs are the ones we cataloged in a free playbook on spotting the next Nvidia early.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.