Chasing ASML’s Dominance: Canon and Nikon Are Doing Something The Market Misses
ASML just dominated another quarter, but Canon and Nikon are quietly carving out a position in chip manufacturing that Wall Street's models barely account for, and one memory giant is already betting on it.

ASML (NASDAQ: ASML | ASML Price Prediction) just posted another blockbuster quarter, while Canon (OTC: CAJPY) quietly pushed its nanoimprint lithography platform deeper into customer fabs. Both stocks trade on the same theme: who patterns the next generation of chips, and at what cost. ASML owns the leading edge. Canon, alongside Nikon, is chasing an entirely different lane that Wall Street barely models.
EUV Demand Explodes While Canon Plays a Different Game
ASML’s Q2 2026 was a statement quarter. Revenue hit $10.65B, up 21.3% YoY, with EPS of $8.67 and free cash flow surging 268% year over year. Management raised full-year guidance to €43 billion to €45 billion. Memory net system sales are expected to grow over 75% in 2026, driven by HBM and advanced DRAM nodes. That is the kind of quarter that reshapes multi-year models.
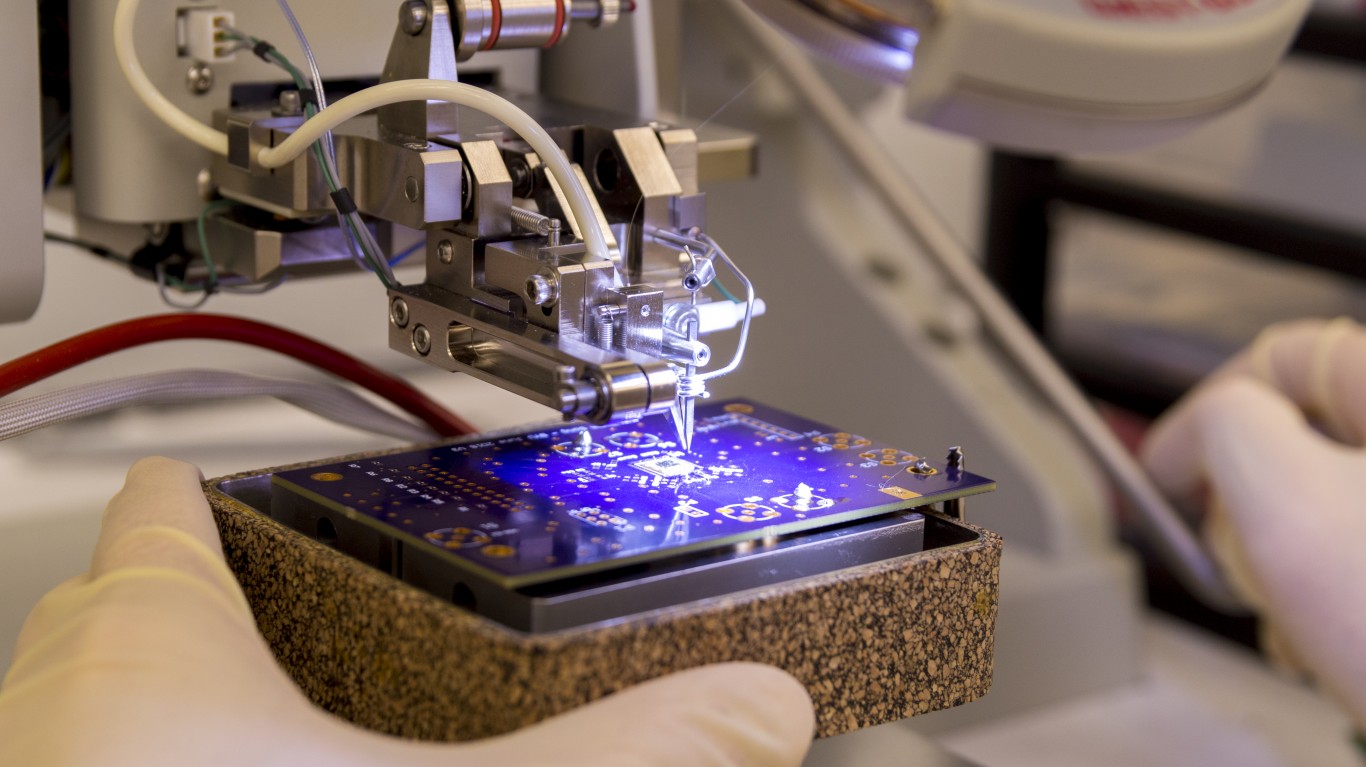
Canon’s lithography ambitions look tiny by contrast, but the strategy is real. Its FPA-1200NZ2C nanoimprint system stamps circuit patterns onto wafers using a mask, sidestepping the physics and price tag of EUV. Nikon, meanwhile, keeps iterating on i-line and ArF scanners for mature nodes. Instead of challenging ASML at 2nm, both target the layers below it, where cost per wafer matters more than resolution.
Where Nanoimprint Actually Wins
| Lens | ASML | Canon and Nikon |
| Core Bet | High NA EUV at leading edge | Nanoimprint and DUV for cost-sensitive layers |
| Target Customer | TSMC, Samsung, Intel, SK Hynix | NAND memory, power devices, specialty logic |
| Key Vulnerability | Export controls, order concentration | Adoption speed, defect density |
ASML’s own commentary underscores the opening. CEO Christophe Fouquet said customers are “aggressively” adding capacity, and CFO Roger Dassen described upgrade demand as “very, very strong because customers are looking for productivity.” That pricing power is real. It also creates a wedge for cheaper alternatives on layers that do not need a $400 million High NA tool. Kioxia has publicly adopted Canon’s nanoimprint approach for select memory work, which is exactly the kind of foothold that compounds quietly.
What Decides the Next Leg
I will be watching whether High NA EUV reaches the maturity ASML needs to justify its price against low NA plus multi-patterning. Fouquet flagged Intel Foundry adoption as “maybe the strongest sign so far that we’re getting there.” On the Canon side, the tell is customer count. If a second or third memory maker qualifies nanoimprint for production layers in 2027, the narrative shifts.
Why I Still Lean ASML, With a Canon Kicker
For me, ASML remains the cleaner way to own lithography. The 83.61% one-year run reflects backlog visibility that few capital equipment names ever get. Yet the stock also dropped 14.92% over the past month, a reminder that expectations are high. Canon, essentially flat with a 3.05% YTD decline, is the option trade. If nanoimprint scales, the re-rating could be sharp. If not, you still own a diversified imaging and medical business. Different risk, different reward, same industry tailwind.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.