Price Prediction: In 2 Years, Nvidia Will Be Worth This Much
Nvidia's earnings estimates have sprinted far ahead of its share price, and one upcoming product ramp could rewrite the revenue math entirely. Here is how the numbers stack up for the next two years.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
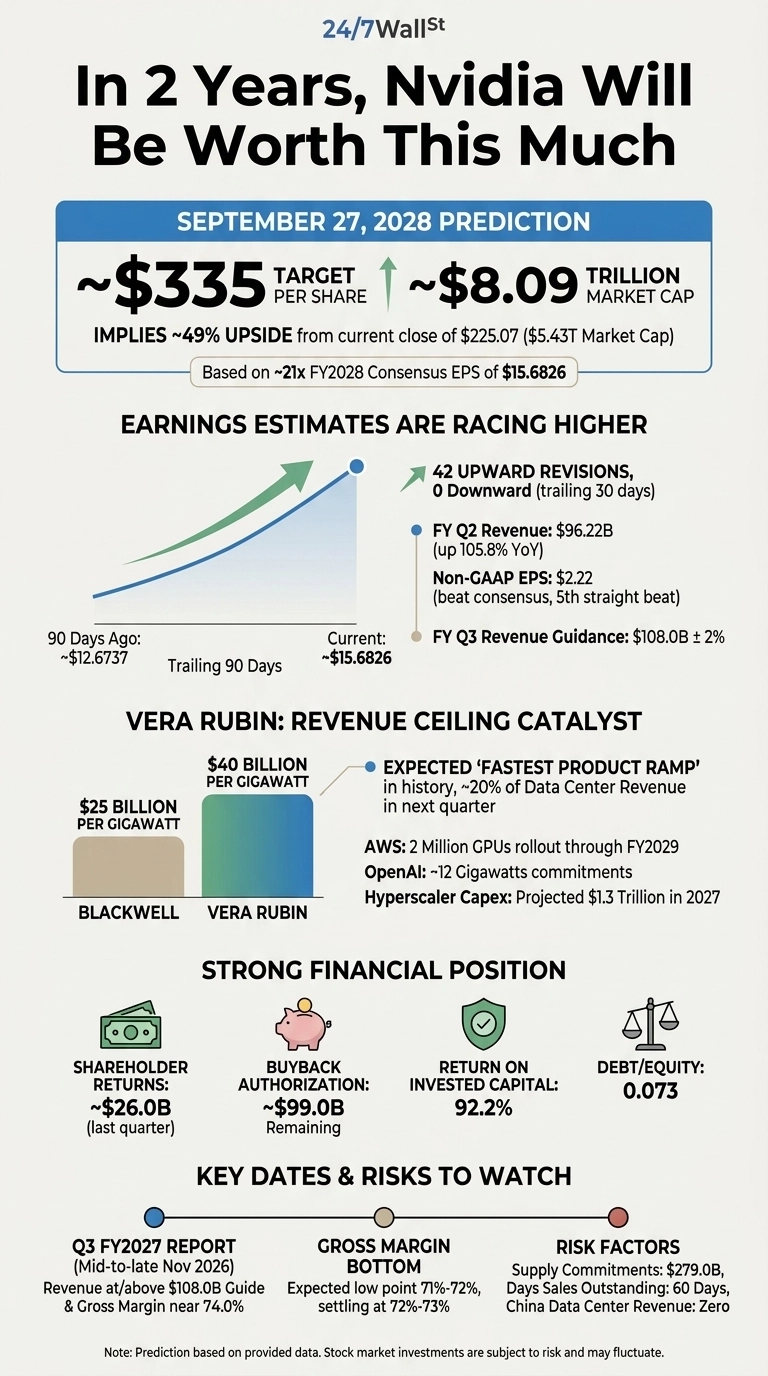
By September 27, 2028, NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) will close at or above $335 per share. At today’s share count of 24.147 billion, that works out to a market value of about $8.09 trillion.
The stock closed at $225.07 on September 25, with a market cap of $5.43 trillion, so the target is roughly 49% above that close.
Hitting it only requires a multiple of about 21x the fiscal 2028 consensus EPS of $15.6826. Today the stock trades at about 14x that figure and 45x trailing earnings.

Earnings Estimates Are Racing Higher Than the Share Price
In fiscal Q2, revenue reached $96.22B, up 105.8% year over year. Non-GAAP EPS of $2.22 exceeded the $2.09 consensus, the 5th straight beat. Q3 guidance calls for $108.0B ± 2%.
Management expects revenue to grow “approximately 70%” next fiscal year and calls that a supply-constrained number. It also said “customers’ forecasts point to our growth doubling next year.“
Analysts have raised the fiscal 2028 EPS average from $12.6737 90 days ago to $15.6826, with 42 upward revisions and zero downward over 30 days. The stock is up 26.97% over the past year, well behind those revisions.

Vera Rubin Raises the Revenue Ceiling per Gigawatt
For Nvidia, Vera Rubin brings in about $40 billion of revenue per gigawatt, compared with $25 billion for Blackwell. Management expects “the fastest product ramp in NVIDIA’s history”, with Rubin making up about 20% of data center revenue next quarter.
AWS is rolling out 2 million GPUs through the second quarter of fiscal 2029. OpenAI’s commitments total approximately 12 gigawatts. Capital spending by the top five hyperscalers is projected at $1.3 trillion in 2027.

Cash Returns Put a Floor Under Per-Share Value
NVIDIA returned a record $26B to shareholders last quarter and has approximately $99B left on its buyback authorization. Debt-to-equity is 0.073 and return on invested capital is 92.2%.
Management plans to return more of its excess free cash flow, and every share retired adds to per-share earnings. For retirement portfolios, that balance sheet supports a high-growth position.

Dates Retirement Investors Should Circle Now
- Q3 FY2027 report (mid-to-late November 2026): revenue at or above the $108B guide and gross margin near 74% keep the thesis on track.
- Gross margin bottom: management has indicated 71% to 72% at the low point before settling at 72% to 73%. A drop below that range is a warning sign.
- Supply commitments: the $279B in commitments, days sales outstanding at 60 days, and zero China data center revenue in guidance are the pressure points to track.
If AI spending stalls and those $279B in supply commitments turn into excess inventory, the stock will miss $335. Even so, a 21x multiple on earnings estimates that keep rising is a modest ask, and I expect NVIDIA to clear it by September 27, 2028.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.