My AMD Price Prediction Comes Down to One Crucial Growth Opportunity
AMD has surged 254% in a year and just posted triple-digit Data Center growth, yet our price target sits below the current stock price. One segment either justifies the valuation or exposes it.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
My AMD price prediction really does come down to one thing: whether the Data Center segment can keep doubling. Everything else is noise around that signal.
AMD (NASDAQ: AMD | AMD Price Prediction) trades at $559.82 after a monster rally, and our 24/7 Wall St. price target for AMD is $510.66 over the next 12 months. That implies roughly -8.78% downside from here, and our recommendation is hold with high confidence (0.9). The stock is fully priced for perfect execution on Helios and Instinct.
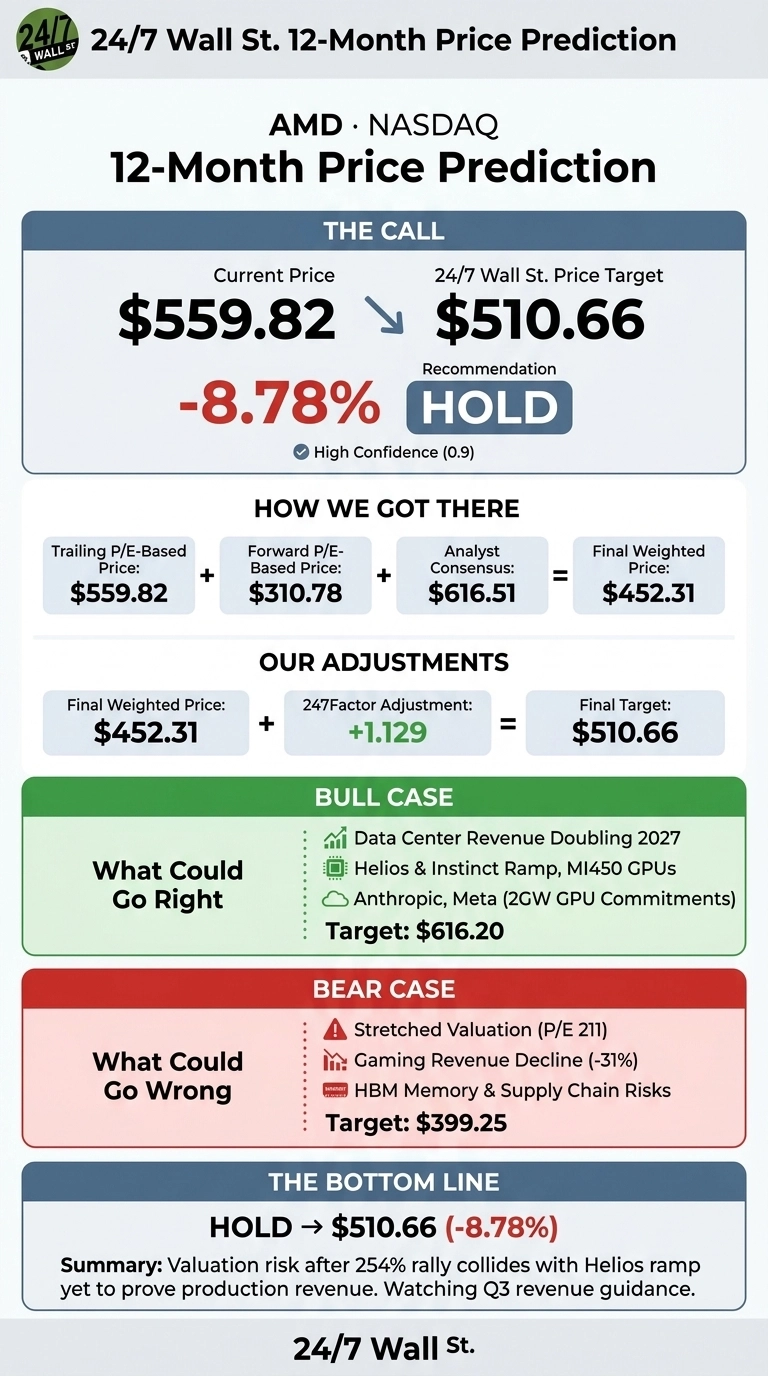
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $559.82 |
| 24/7 Wall St. Price Target | $510.66 |
| Upside/Downside | -8.78% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Why We Could Be Wrong
Our 24/7 Wall St. price target sits below AMD’s current price. Real upside could come from the 2 GW Anthropic MI450 commitment ramping faster than expected, or the Oracle Cloud 50,000-GPU Helios deployment in Q3 2026 pulling forward.

A 254% Run Into a Wall of Expectations
AMD has climbed 254.5% over the past year and 161.4% year to date.
Q2 FY2026 revenue landed at $11.54 billion, up 50.11% year over year, with non-GAAP EPS of $1.66 beating the $1.61 consensus. Data Center revenue of $6.72 billion grew 107% YoY and now represents 58% of total revenue. Management guided Q3 to roughly $13 billion, up about 41% YoY.

Bull Case for $616 and Higher
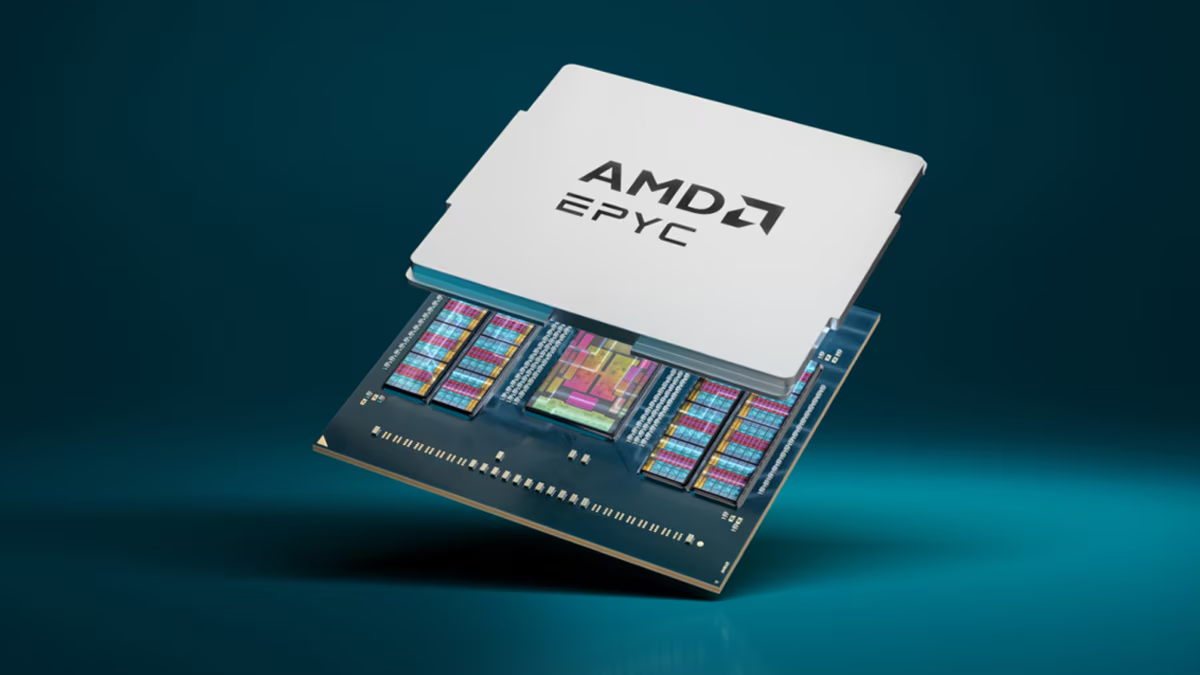
Bulls have a real thesis. Management expects data center segment revenue to more than double year over year in 2027, powered by Helios rack-scale systems, MI450 GPUs, and Venice EPYC CPUs. The AI accelerator TAM is now projected to hit $1.4 trillion by 2030, growing more than 45% annually.
Anchor customers include Anthropic, Meta (up to 6 GW of Instinct GPUs), Microsoft Azure, and OpenAI. The Street’s high FY2027 EPS estimate is $20.25. At a 40x multiple, that supports a bull case above $616.

What Could Go Wrong
Valuation is stretched: trailing P/E sits at 211. Gaming revenue fell 31% YoY, reflecting the console cycle. Free cash flow slipped 9.89% YoY as AMD invested in capacity for the Helios ramp beginning in Q3 2026.
Real risks remain: HBM memory constraints, U.S. export controls, and NVIDIA’s CUDA moat. Our bear scenario points to $399.25.
How AMD Compares to NVIDIA and Intel
NVIDIA (NASDAQ: NVDA) trades at a P/E of 45 with Q2 FY2027 non-GAAP gross margin of 75% and Data Center revenue of $89.02 billion, up 117% YoY. AMD’s trailing P/E of 210 and 56% non-GAAP gross margin make the field’s leader look like the value name, a warning flag for our target.
Intel (NASDAQ: INTC) shows CPU demand is broad. Intel’s DCAI segment grew 59% to $6.26 billion in Q2 2026. Intel’s $574 billion market cap versus AMD’s $913.89 billion reflects how much AI-share optimism is priced into AMD. The peer set makes our 24/7 Wall St. price target reasonable.
| Company | Market Cap | Latest Quarter Revenue Growth |
|---|---|---|
| AMD | $913.89B | 50.11% |
| NVIDIA | $5.37T | 105.85% |
| Intel | $574.07B | 25.42% |
AMD Price Prediction 2026-2030
My verdict: Hold, target $510.66, confidence 90%. Valuation risk after a 254% one-year rally collides with a Helios ramp that has yet to prove itself in production revenue. I’d be a buyer if Q3 revenue lands above the $13.3 billion top end of guidance and management raises the 2027 data-center outlook.
Looking further ahead, here is where our model projects AMD could trade, assuming the current AI trajectory holds.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $548.68 |
| 2027 | $500.68 |
| 2028 | $472.78 |
| 2029 | $517.55 |
| 2030 | $514.38 |
These projections assume AMD continues executing on Helios and Instinct. Significant upside or downside could result from HBM supply, export policy, or a faster-than-expected MI500 cycle.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.