Nvidia vs. Eli Lilly: I’d Choose This Stock for the Next Decade

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
NVIDIA (NASDAQ: NVDA | NVDA Price Prediction) and Eli Lilly (NYSE: LLY) just posted quarters that showcase two of the most powerful growth engines in the market.
NVIDIA is riding a supply-constrained AI infrastructure build. Lilly is scaling GLP-1 medicines faster than it can add factories. Both blew past estimates. Only one, in my view, has a cleaner runway for the next decade.
AI Factories Carry NVIDIA. GLP-1 Carries Lilly.
NVIDIA delivered $96.22B in Q2 FY2027 revenue, up 105.8% year over year, with Data Center alone contributing $89.02B. Blackwell Ultra is ramping, and Vera Rubin is already in full production.
CEO Jensen Huang framed the moment bluntly: “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.” Management now guides Q3 to $108B and expects roughly 70% revenue growth in fiscal 2028, all while calling the outlook supply-constrained.

Lilly reported $22.97B in Q2 2026 revenue, up 47.7%, with Mounjaro and Zepbound combining for $14.9 billion. International momentum is real: rest-of-world grew 136% in constant currency, and China Mounjaro sales jumped 93%.
Lilly’s oral GLP-1 Foundeo expanded its U.S. prescriber base from 8,000 to 36,000 in a single quarter. Full-year revenue guidance moved up to $85B to $87B.

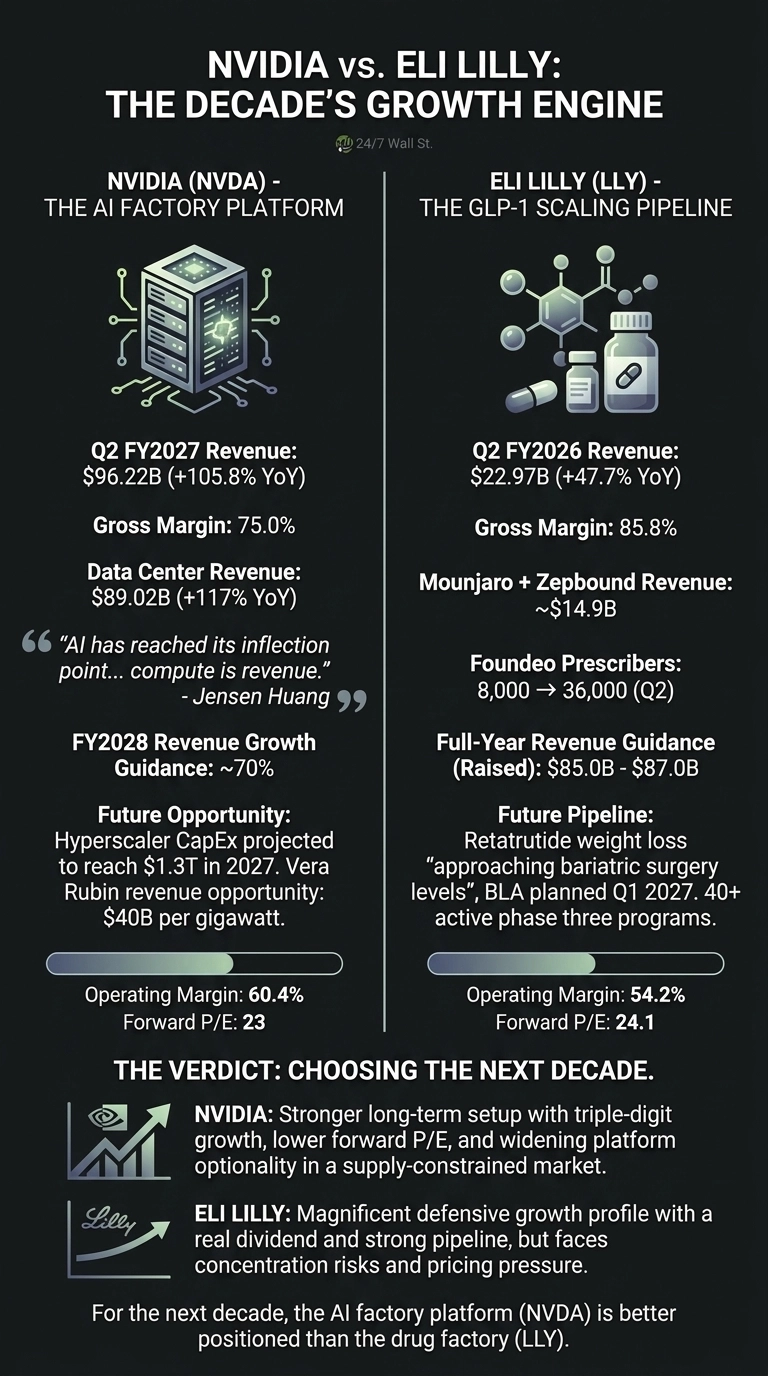
| Business Driver | NVIDIA | Eli Lilly |
| Main Growth Engine | Data Center compute and networking | Mounjaro, Zepbound, Foundeo |
| Revenue Growth (last Q) | +105.8% | +47.7% |
| Gross Margin | 75.0% | 85.8% |
Two Very Different Bets on the Next Decade
NVIDIA is monetizing a platform. Every gigawatt of Vera Rubin represents $40 billion in revenue opportunity, up from Blackwell’s $25 billion. Hyperscaler capex is projected to hit nearly 800 billion in 2026 and 1.3 trillion in 2027.
The risks are equally large: extreme memory pricing, $279B in supply commitments, zero China DC compute in guidance, and growing scrutiny of NVIDIA’s balance-sheet support for AI labs.

Lilly is monetizing a molecule pipeline. Retatrutide, its next-gen triple-acting weight-loss drug, produced weight loss “approaching bariatric surgery levels”, with a BLA filing planned for Q1 2027.
The company has more than 40 active phase three programs. But U.S. price fell 9% ex-rebates, and concentration in two drugs is a real vulnerability.

What Would Change My Mind
Watch NVIDIA’s Vera Rubin ramp, which management expects to reach about 20% of data center revenue in Q3. If supply loosens without demand blinking, the FY28 EPS estimate of $15.5675 could look conservative.
For Lilly, I want retatrutide’s regulatory path confirmed and Foundeo’s international launches to translate into durable share.

Why NVIDIA Stands Out for the Next Decade
For a ten-year lens, NVIDIA screens strongest. The forward P/E of 23 against triple-digit growth and a 60.4% operating margin is hard to argue with, and the platform’s optionality across networking, CPUs, robotics, and sovereign AI keeps widening.
Lilly is a magnificent business, and for lower beta (0.502 versus NVDA’s 2.217) with a real dividend, it fits a defensive growth profile better. Both are compelling on their own terms. On relative setup, the AI factory looks better positioned than the drug factory, at least until the supply-demand gap closes.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.