Here’s When Nividia’s Dominance Fades, Opening Broadcom’s Era of Dominance
NVIDIA just posted triple-digit growth and Broadcom matched it with a custom chip story that has hyperscalers quietly betting billions against the GPU. Something has to give, and the timeline is closer than most investors realize.

NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) and Broadcom (NASDAQ:AVGO) delivered blockbuster AI quarters within a week of each other. NVIDIA’s Q2 FY2027 earnings report reinforced GPU dominance. Broadcom’s Q3 FY2026 report showed custom accelerators scaling faster than expected. AI compute is shifting from training-heavy GPU workloads toward inference-optimized ASICs, and both quarters offered evidence of how that handoff might unfold.
Blackwell Ultra Powers One Quarter, Custom XPUs Power the Other
NVIDIA posted revenue of $96.22B, up 105.8% YoY, with Data Center at $89.02B (+117%) and Networking at $40.31B (+138%). Jensen Huang told investors “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable.” Q3 guidance sits at $108.0B ±2%, excluding China.
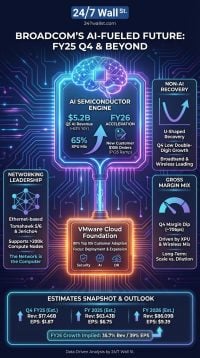
Broadcom’s story was one of concentration. AI semiconductor revenue reached $16.70B, up 221% YoY and 54% sequentially. Google’s Ironwood TPU v7 shipped in volume, TPU v8i began production, and OpenAI’s Jalapeno accelerator started shipping. Hock Tan guided Q4 AI revenue to roughly $21.7B (+236% YoY).
| Business Driver | NVIDIA | Broadcom |
| Main AI Engine | Blackwell Ultra, Vera Rubin | Custom XPUs for Google, Anthropic, OpenAI, Meta |
| Latest AI Growth | Data Center +117% YoY | AI semis +221% YoY |
| Networking Bet | Spectrum-X, NVLink 72 | Tomahawk 6/7, Tomahawk Ultra |
Platform Fortress Versus Workload Tuned Silicon
Huang framed NVIDIA as “a full-stack AI factory platform”, arguing rivals sell “inference-specific chips for one cloud or one service”. Management guided fiscal 2028 revenue growth of approximately 70%.
Broadcom’s counterargument came from customer wins. Tan claimed TPU v8i is “comparable if not surpasses the Vera Rubin GPU”, and that Jalapeno runs OpenAI workloads at “half the cost of a GPU”. Anthropic is expected to deploy five gigawatts of TPU v8i in 2027, and Broadcom has secured supply for roughly $115 billion of AI revenue in fiscal 2027 and $230 billion in fiscal 2028. That suggests investors have a reasonable timeframe to expect Broadcom could begin eroding Nvidia’s dominance in the very near future.
Supply Constraints Decide the Race
Both companies are supply-constrained. NVIDIA warned of “extreme pricing conditions in memory“. Broadcom is opening a Singapore substrate factory in fiscal 2027 and tripling laser capacity. Watch whether Vera Rubin holds its “fastest product ramp in NVIDIA’s history” promise and whether Broadcom converts its 10-gigawatt 2028 Anthropic pipeline into shipped silicon.
Why I Own Both, But Weight Them Differently
NVIDIA’s CUDA, integrated networking, and financing partnerships with Apollo, BlackRock, Blackstone, Brookfield, Goldman and KKR build a moat ASICs can chip at but not crack. Broadcom trades at a forward P/E of 18 versus NVDA at 23, despite a clearer glide path from $58 billion in fiscal 2026 AI revenue toward $230 billion in fiscal 2028. Defensive AI investors get more comfort from NVIDIA. Investors chasing the inference era have the more interesting call in Broadcom’s XPU cohort (we reverse-engineered what the biggest tech winners looked like early and turned it into a free playbook here).
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.