GE Vernova is The AI Energy Bottleneck Player I Won’t Stop Buying
GE Vernova's backlog keeps exploding and its CEO says the company will be mostly sold out through 2030, yet most AI power investors are looking at entirely the wrong part of the supply chain.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
My cost basis on GE Vernova (NYSE:GEV | GEV Price Prediction) keeps climbing because I keep hitting the buy button, and the reason is simple: every hyperscaler on earth needs more electricity, and this company builds the turbines that produce it.
I am buying a backlog. That backlog closed the most recent quarter at $176 billion, with management guiding to $200 billion in 2027. Q2 orders alone came in at $24.2 billion, up 88% organically. Those are the numbers of a company rationing capacity to meet demand.
Why I Keep Adding on Every Dip
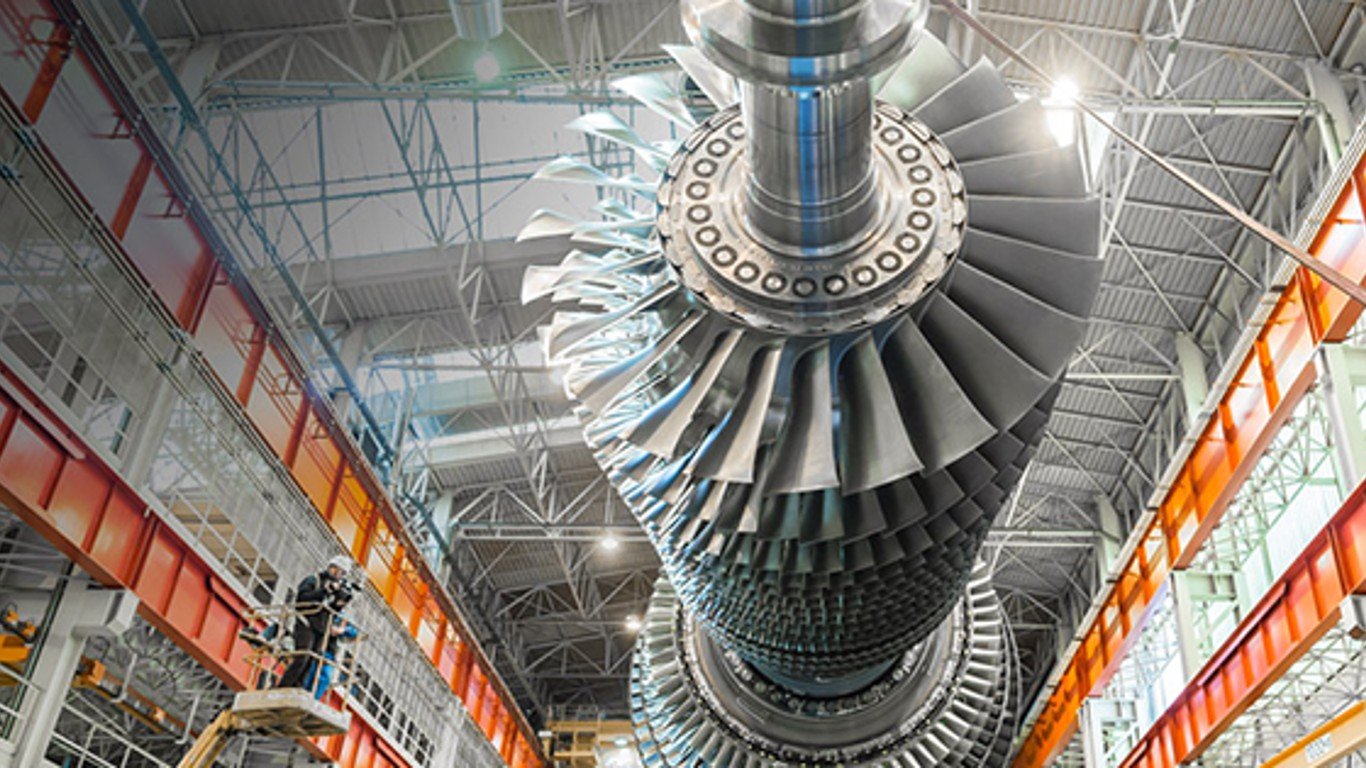
Power keeps me refusing to trim. GE Vernova signed 20 GW of gas contracts in Q2 alone and expects at least 125 GW of gas equipment under contract by year-end 2026. Annual turbine output scales from 20 GW in Q3 2026 to 24 GW in 2028 and 30 GW in 2030. CEO Scott Strazik told analysts the company expects to be “mostly sold out through 2030”, with 2031 slots already filling.
Electrification is the second engine. Q2 orders grew 66% organically at a book-to-bill of 1.7x, and data center orders crossed $5 billion year-to-date, more than double the entire 2025 total. Strazik said current data-center scope of roughly $300 million per gigawatt could grow to two to three times that as solid-state transformers and medium-voltage UPS blocks commercialize.
Cash Coming Out of the Walls
Free cash flow in Q2 hit $5.1 billion, exceeding all of full-year 2025. Management raised 2026 free cash flow guidance to $11.5 billion to $12.5 billion from a prior range of $6.5 billion to $7.5 billion. The revision is a full re-underwrite of the business. The board doubled the quarterly dividend to $0.50 per share and lifted buyback authorization to $10 billion. Roughly $7 billion has already been deployed at an average price of $560 per share. My cost basis is higher, and I am fine with that.
Why Not the Obvious AI Power Names
Most readers reach first for Constellation Energy (NASDAQ:CEG) or Vistra (NYSE:VST). Both sell electrons. GE Vernova sells the machines that produce them. Every gigawatt CEG or VST wants online has to be built by someone, and GEV’s 134% organic orders growth in Power gas equipment tells me who is getting those calls. I would rather own the toll booth than the traffic (we profiled seven more of these non-chipmaker AI infrastructure suppliers, from power to cooling, in a free report you can grab here).
Risk I Am Not Pretending Away
Wind is ugly. Segment revenue fell 10% in Q2 and management still expects roughly $400 million of segment EBITDA losses for the full year. Offshore costs are elevated and U.S. onshore permitting is stuck. The thesis holds because Wind is a small drag against Power at 18.8% EBITDA margin and Electrification at 18.4%. Valuation runs rich at a forward P/E near 38, with shares at $945.70 after a 51.86% one-year run. I accept that because 2028 targets call for $56 billion in revenue, a 20% adjusted EBITDA margin, and at least $24 billion in cumulative free cash flow.
The buy button stays active as long as data centers keep signing power contracts faster than the world can build turbines, and nothing on my screen suggests that changes.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.