Micron Price Target Raised to $1,300 by Citi on Stronger DRAM Pricing, Undersupply
Citi just lifted its Micron price target, but here is the catch: even that higher number sits well below what Wall Street analysts collectively expect, raising the question of how much further this rally has left to run.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Citi analyst Atif Malik raised the firm’s price target on Micron to $1,300 from $1,150 while keeping a buy rating on the memory maker. The revised target reflects better than expected DRAM pricing and continued supply tightness heading into fiscal Q4. For long-term investors, the price target raised by Citi reinforces a thesis that memory pricing power is durable.
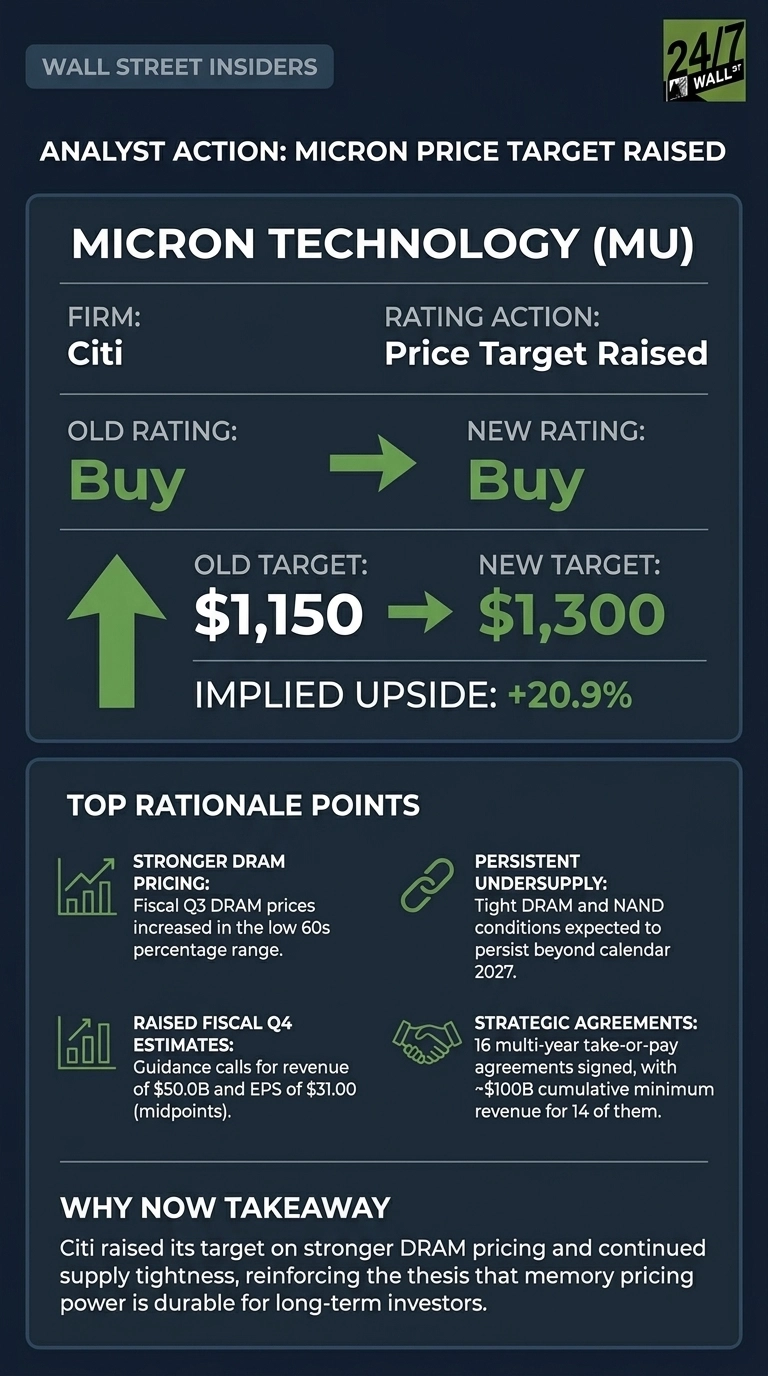
| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| MU | Micron Technology (NASDAQ:MU | MU Price Prediction) | Citi | Price target raised | Buy | Buy | $1,150 | $1,300 |
Analyst’s Case
Malik raised his August and November quarter estimates on the back of stronger DRAM pricing than he had modeled.
He expects the stock to rally into SEMICON West as equipment makers highlight DRAM shortages, and he thinks Micron should report upside to fiscal Q4 estimates as the DRAM and NAND markets remain undersupplied.
Management’s own commentary supports the setup. On the fiscal Q3 call, CEO Sanjay Mehrotra said “DRAM and NAND industry demand continues to significantly exceed industry supply” and that Micron expects tight conditions to persist beyond calendar 2027. Fiscal Q3 DRAM prices increased in the low 60s percentage range, while NAND prices rose in the mid-80s percentage range.
Company Snapshot
Micron is the only U.S.-based memory manufacturer, with a market cap of roughly $1.21 trillion. Fiscal Q3 2026 revenue reached $41.46 billion, up 345.7% year over year, with non-GAAP EPS of $25.11 and a record non-GAAP gross margin of 84.9%. Guidance for fiscal Q4 calls for revenue of $50 billion plus or minus $1 billion and EPS of $31 plus or minus $1.
Micron has also signed 16 Strategic Customer Agreements, typically five-year take-or-pay agreements running through calendar 2030. For 14 of the 16 signed agreements, cumulative revenue at the minimum price is approximately $100 billion, backed by $22 billion in cash deposits and letters of credit.

Why the Move Matters Now
Micron stock is trading around $1,075.72, up 277.14% year to date and 554.52% over the past year. Even after that run, shares trade at a trailing PE of 23 and a forward PE of 7, with a Street average target of $1,515.
Consensus fiscal 2027 EPS has climbed to $156.53, up from $117.86 ninety days ago, and Citi’s $1,300 target sits below the Street mean, suggesting room for further upward revisions if pricing holds.

What It Means for Your Portfolio
For retirement-focused investors, the Micron stock story has shifted from a classic memory cycle trade to something more contract-anchored, with Strategic Customer Agreements pointing toward roughly half or more of company revenue under multi-year commitments once fully executed.
The Citi analyst upgrade to $1,300 highlights that near-term earnings power is still being underestimated. Position sizing matters after a triple-digit rally, but the combination of undersupply, take-or-pay contracts, and rising consensus estimates warrants a closer look, even as near-term volatility remains a real risk.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.