Palantir’s Valuation Is Huge. So Is the Opportunity
Palantir's latest quarter left analysts scrambling to justify a valuation that looks either wildly overpriced or strangely reasonable depending on one number that keeps accelerating beyond every model built to contain it.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Few stocks split investors like Palantir (NASDAQ:PLTR | PLTR Price Prediction). The multiple looks extreme, the growth looks unreal, and both camps are right.
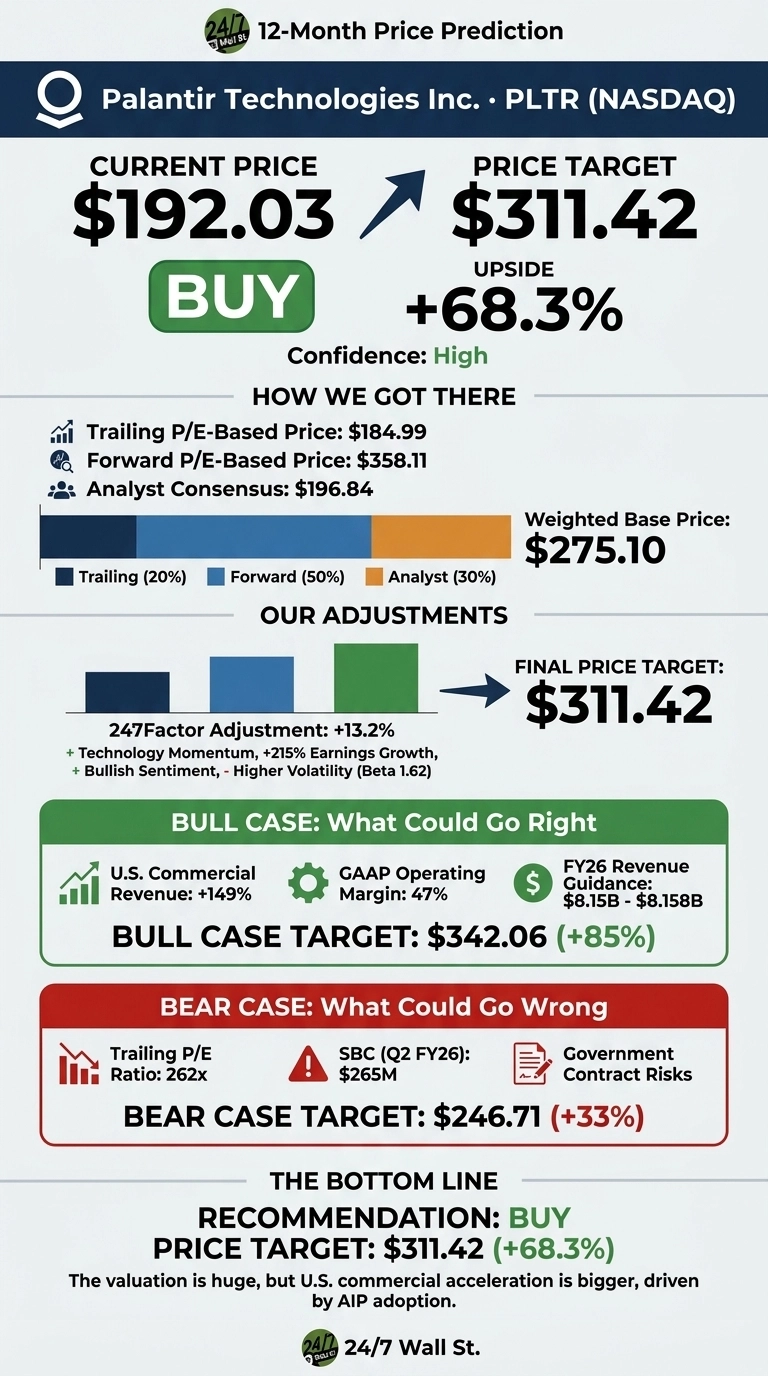
Our 24/7 Wall St. price target is $311.42, implying 68.3% upside. Our recommendation is buy with 90% confidence. The valuation is huge, but U.S. commercial acceleration is bigger.
| Metric | Value |
|---|---|
| Current Price | $192.03 |
| 24/7 Wall St. Price Target | $311.42 |
| Upside | 68.3% |
| Recommendation | BUY |
| Confidence Level | 90% |

A Sovereign AI Quarter That Reset the Story
Palantir shares are up 11.28% over the past week and 8.03% year to date.
The catalyst was Q2 FY26, reported August 3, 2026. Revenue hit $1.935 billion, up 92.83% year over year, EPS came in at 0.41 versus a 0.28 estimate (ninth straight beat), and U.S. commercial revenue jumped 149% year over year to $764 million. Management raised FY26 revenue guidance to $8.150 to $8.158 billion, or roughly 82% growth. CEO Alex Karp called it “otherworldly.”

Why Bulls See a Breakout Ahead
The bull case rests on U.S. commercial. Remaining deal value ballooned to $6.238 billion, up 124% year over year, with FY26 U.S. commercial revenue guided to grow at least 134%.
AIP adoption turned a Rule of 40 score into 155%, virtually unheard of at scale. GAAP operating margin hit 47% and free cash flow ran $1.22 billion in Q2. If sovereign AI demand sustains, the bull scenario targets $342.06, an 85% return.

What Could Go Wrong
The bear case hinges on valuation. Palantir trades at 262x trailing P/E and 82x forward P/E. Any deceleration below 80% growth could compress that multiple sharply. Stock-based compensation ran $265 million in Q2, and government contracts carry termination-for-convenience clauses.
Bulls counter that SBC is falling as a revenue percentage given 93% top-line growth, and $2.03 billion net cash plus $4.5 to $4.7 billion guided FY26 free cash flow absorbs dilution. The bear scenario still lands at $246.71, up 33%.

How Palantir Compares to ServiceNow and Snowflake
ServiceNow (NYSE:NOW) is the profitability benchmark: $14.73 billion revenue TTM, 27x forward P/E, and 24% quarterly revenue growth. ServiceNow trades at roughly a third of Palantir’s forward multiple but grows a quarter as fast, justifying Palantir’s premium if growth sustains.
Snowflake (NYSE:SNOW) is the direct data-platform comp at 167x forward P/E on 35.1% quarterly revenue growth. Palantir grows nearly three times faster and prints a 36.3% net margin versus Snowflake’s negative profitability. On a growth-adjusted basis, our price target looks reasonable.
Palantir Price Prediction 2026-2030
Our price target of $311.42 and buy rating carry 90% confidence. The tipping factor is U.S. commercial growth of 149% combined with 47% GAAP margins. Watch for U.S. commercial TCV compounding above 100% into Q4; a break below 60% would leave the multiple no room for stumble.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $216 |
| 2027 | $349 |
| 2028 | $447 |
| 2029 | $589 |
| 2030 | $707 |
These projections assume Palantir continues converting AIP pilots into eight-figure commercial deals. Significant downside could result from a defense budget contraction or a broad enterprise software multiple reset.
Palantir is the software face of the AI buildout, but the power, cooling, and networking suppliers behind the data centers deserve a look too, and we rounded up seven of them in a free report on the AI infrastructure trade.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.