The IREN Story Is Changing Fast. We See 82% Upside Potential
IREN just wrote off nearly half a billion dollars in Bitcoin mining hardware, and Wall Street is still trying to figure out what company emerged on the other side of that transformation.

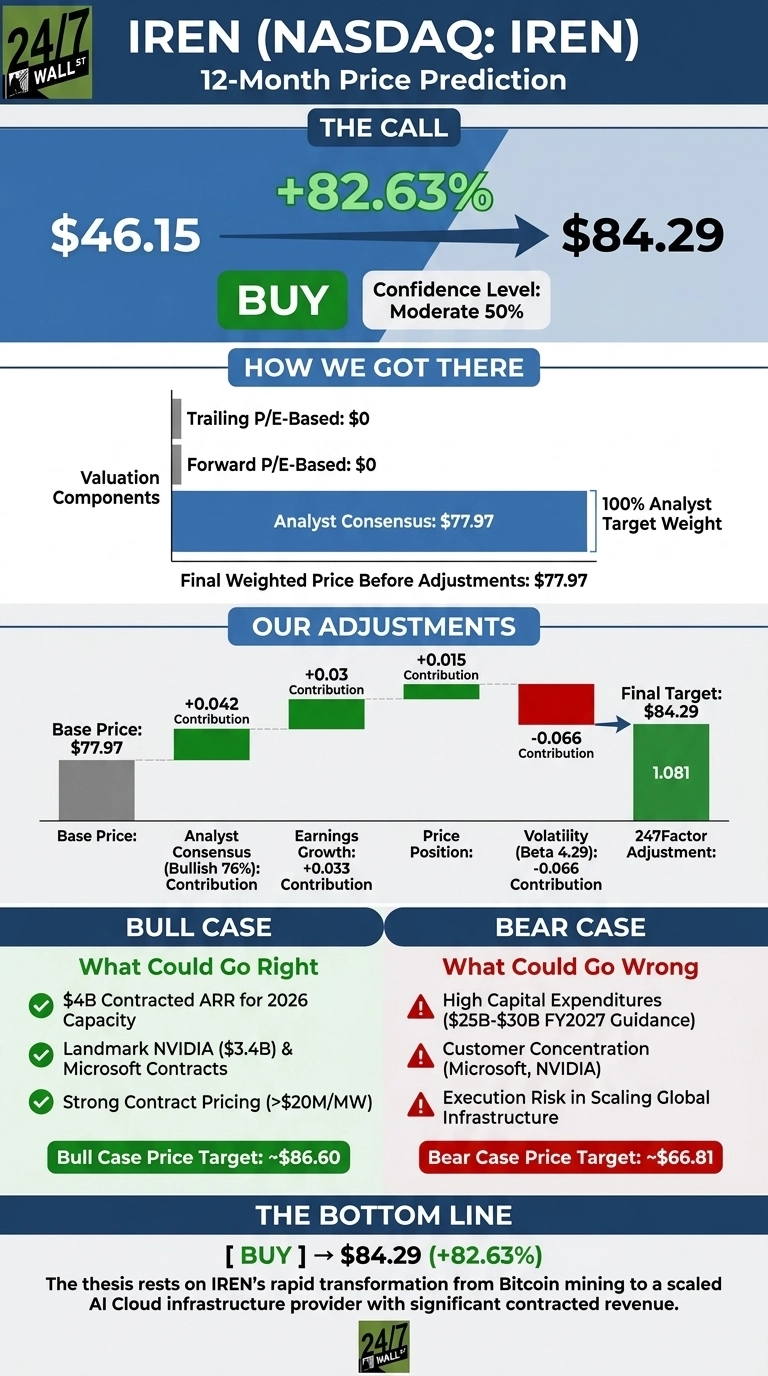
My 24/7 Wall St. price target for IREN (NASDAQ:IREN) is $84.29, implying 82.63% upside from the current price of $46.15. My recommendation is buy with a moderate 50% confidence level, reflecting both the scale of the AI Cloud opportunity and the very real execution risk of scaling GPU capacity across four continents.
IREN has stopped being a Bitcoin miner in any meaningful sense, and the market is still catching up to what that means.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $46.15 |
| 24/7 Wall St. Price Target | $84.29 |
| Upside | 82.63% |
| Recommendation | BUY |
| Confidence Level | 50% |
Why the Story Changed in a Single Quarter
IREN has climbed 8.28% over the past week and 22.19% year to date.
The catalyst was FY2026 results on August 27, 2026: revenue of $137.2 million missed estimates by 2.52%, with a GAAP net loss of $684 million driven almost entirely by a $450.4 million impairment on decommissioned Bitcoin mining hardware.
AI Cloud revenue more than doubled sequentially to $70.5 million. Days later, Blue Owl-managed funds led a $2.4 billion AI factory financing for IREN.
Why Bulls See a Path to $100 and Beyond
The bull case rests on contracted revenue already signed. IREN has $4 billion of ARR contracted for 2026 capacity, of which $1 billion was operating as of late August. The $9.7 billion Microsoft deal and $3.4 billion, five-year NVIDIA AI Cloud contract plus up to $2.1 billion NVIDIA investment validate the platform.
Three-year contracts run above $20 million per megawatt of IT load, with discussions near $25 million per MW. Compass Point lifted its target to $105 after the Microsoft announcement.
If IREN delivers Horizons 2 through 4 on schedule and lands 2027 capacity at rising prices, my bull case points to roughly $86.60 within twelve months.
What Could Go Wrong
The bear case is execution. IREN carries a debt-to-equity ratio of 1.87, an operating margin of -148%, and FY2027 capex guidance of $25 billion to $30 billion. Customer concentration in Microsoft and NVIDIA is real, and Reddit sentiment has swung, with a very bearish reading around a thread titled “Why IREN is a hard pass for me” in early September.
The counterfactual matters: those losses are largely non-cash, operating cash flow was $1.81 billion in Q4, and adjusted EBITDA margin ran at 41% in Q2 FY26. My bear case scenario still lands at roughly $66.81, above today’s price.
How IREN Stacks Up Against CoreWeave, Applied Digital, and Cipher
CoreWeave (NASDAQ:CRWV) is the direct pure-play AI cloud comparison. CRWV carries a market cap near $40 billion on a $104 billion backlog and 1.5 GW of active power. CRWV’s debt-to-equity of 8.94 dwarfs IREN’s 1.87, making IREN the cleaner balance sheet at half the market cap.
Applied Digital (NASDAQ:APLD) is the closest data-center pivot comparison, with a $7.66 billion market cap and its first 100 MW direct-to-chip liquid-cooled facility operational. APLD posted Q3 revenue of $126.6 million, similar to IREN’s Q4. IREN’s larger contracted ARR and NVIDIA relationship justify a valuation premium.
Cipher Mining (NASDAQ:CIFR) is the fellow ex-Bitcoin miner with 700 MW of contracted HPC capacity and $11.4 billion in contracted revenue. CIFR trades at a $7.5 billion market cap. IREN’s larger 2026 ARR ramp and NVIDIA-backed contract make my $84.29 target reasonable.
IREN Price Prediction 2026 to 2030
My 24/7 Wall St. price target of $84.29 and buy rating rest on contracted, funded ARR ramping into revenue over the next four quarters.
The setup rewards investors who believe IREN can bring Horizons 2 through 4 online in the December quarter without slippage. IREN sits alongside the power, cooling, and networking names we profiled in a free report on seven AI infrastructure stocks that aren’t chipmakers. Caution is warranted if GPU financing markets tighten or hyperscaler capex plans slow. On balance, the setup favors owners.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $51 |
| 2027 | $99 |
| 2028 | $134 |
| 2029 | $189 |
| 2030 | $205 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.