IREN’s Yearlong Downward Trend Continues: A Prominent Wall Street Firm Says It Will Double and Then Some
IREN has shed 42% from its peak while rivals like TeraWulf and Cipher Mining kept their yearly gains, yet a prominent Wall Street analyst just slapped a $100 price target on the stock. Whether that gap signals a rare opportunity…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
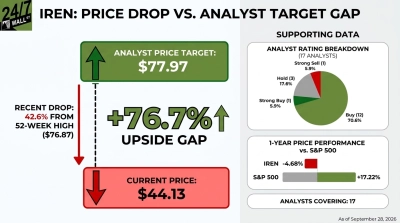
IREN (NASDAQ:IREN) trades at $44.13. Wall Street’s average price target is $77.97, which means about 76.7% upside.
IREN is leaving digital asset mining behind to become an AI cloud provider. It leases GPU capacity to customers that include Microsoft (NASDAQ:MSFT | MSFT Price Prediction) and NVIDIA (NASDAQ:NVDA). Management reports $4 billion of signed annual recurring revenue (ARR) for 2026 capacity, and $1 billion of that is already operating.
Bernstein’s $100 target means 126.6% upside. With a gap that wide, investors must decide whether this is a mispricing or a warning sign.
Revenue Misses Drove a 42% Slide From the Peak
IREN shut down mining rigs faster than it could bring GPUs online. Fiscal Q3 revenue came in at $144.8 million against a $219.29 million estimate, a 33.97% shortfall. Fiscal Q4 revenue of $137.20 million also missed and fell 26.75% year-over-year. The net loss reached $684 million, including a $450.4 million non-cash impairment on retired mining hardware.
The stock is 42.6% below its 52-week high of $76.87, well past the 30% threshold for a severe selloff. A beta of 4.285 amplified each swing. Management expects fiscal 2027 capex of $25 billion to $30 billion and sequential cash SG&A increases of $40 million to $50 million.
Bernstein’s $100 Case Depends on Scarce Power and Rising Contract Prices
Bernstein analyst Gautam Chhugani rates IREN Outperform. His thesis rests on three pillars: the shift to neocloud hosting, a multi-gigawatt power capacity when hyperscalers lack grid access, and fast ARR growth as GPU clusters go live under multi-year contracts. IREN’s pipeline tops five gigawatts, all currently available.
Management expects more than $4 billion ARR by the December quarter close, with most revenue showing in March. Pricing is rising: recent three-year deals exceed $20 million per megawatt, current talks sit near $25 million per megawatt, and paybacks run about two years. Customer prepayments now cover 45% to 55% of GPU capex.
Of 17 covering analysts, 13 rate Buy or Strong Buy, three rate Hold, and one rates Strong Sell. Cantor Fitzgerald cut its target to $82 to $99 from $131.
The weak spot is execution, and co-CEO Daniel Roberts has said so himself: “Signing deals is not the bottleneck in this market. Bringing GPUs online is.”
Rival AI Miners Fell as Hard but Kept Their Yearly Gains
The group dropped more than 40% from highs. IREN is the only one down over the past year.
Cipher Mining (NASDAQ:CIFR) trades at $17.73, 41.2% below its high, but up 52.06% over one year. All 17 analysts rate Buy or Strong Buy, with a $30.93 target means 74.5% upside.
TeraWulf (NASDAQ:WULF) trades at $15.74, 47.3% off its peak, and up 43.48% over one year. All 19 analysts rate Buy or Strong Buy, with a $33.69 target means 114.0% upside.
TeraWulf has the most implied upside. IREN sits in the middle and is the only name with Hold or Sell ratings.
IREN Lags the S&P 500 by More Than 20 Points Over 12 Months
At $44.13, IREN trades below the $77.97 consensus of 17 analysts, means 76.7% upside:
- Strong Buy: 1
- Buy: 12
- Hold: 3
- Strong Sell: 1
Over the past year, IREN is down 4.68%, while the S&P 500 is up 17.22%. Year to date, IREN is up 16.83% against the index’s 13.11%. The stock fell 5.47% last week and trades at a forward P/E of about 137x.
I Lean Bullish, but Only if the December Quarter Delivers
IREN looks compelling here if Horizons 2 through 4 come online on schedule and ARR goes past $4 billion, because pricing near $25 million per megawatt would make Bernstein’s $100 target look reachable. The setup weakens if GPU delays push revenue out again. Missed deadlines on top of $25 billion or more in capex could force dilutive financing and turn this gap into a value trap.
My outlook is bullish, but conservative. The contracts, financing and pricing are real. The March quarter will show whether IREN can execute on them. For readers interested in the picks-and-shovels side of this expansion, we featured seven suppliers driving the AI data center wave in a free report here.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.