The AI Opportunity Qualcomm Investors May Be Underestimating
Wall Street treats Qualcomm like a handset company in slow decline, but a closer look at its data center roadmap and two confirmed hyperscaler wins suggests investors are pricing in the wrong business entirely.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Wall Street prices Qualcomm (NASDAQ: QCOM | QCOM Price Prediction) like a handset company facing a slow Apple exit. Our model sees a diversified semiconductor platform with a credible path into the data center, priced at a discount to its earnings power.
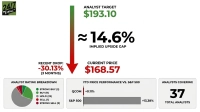
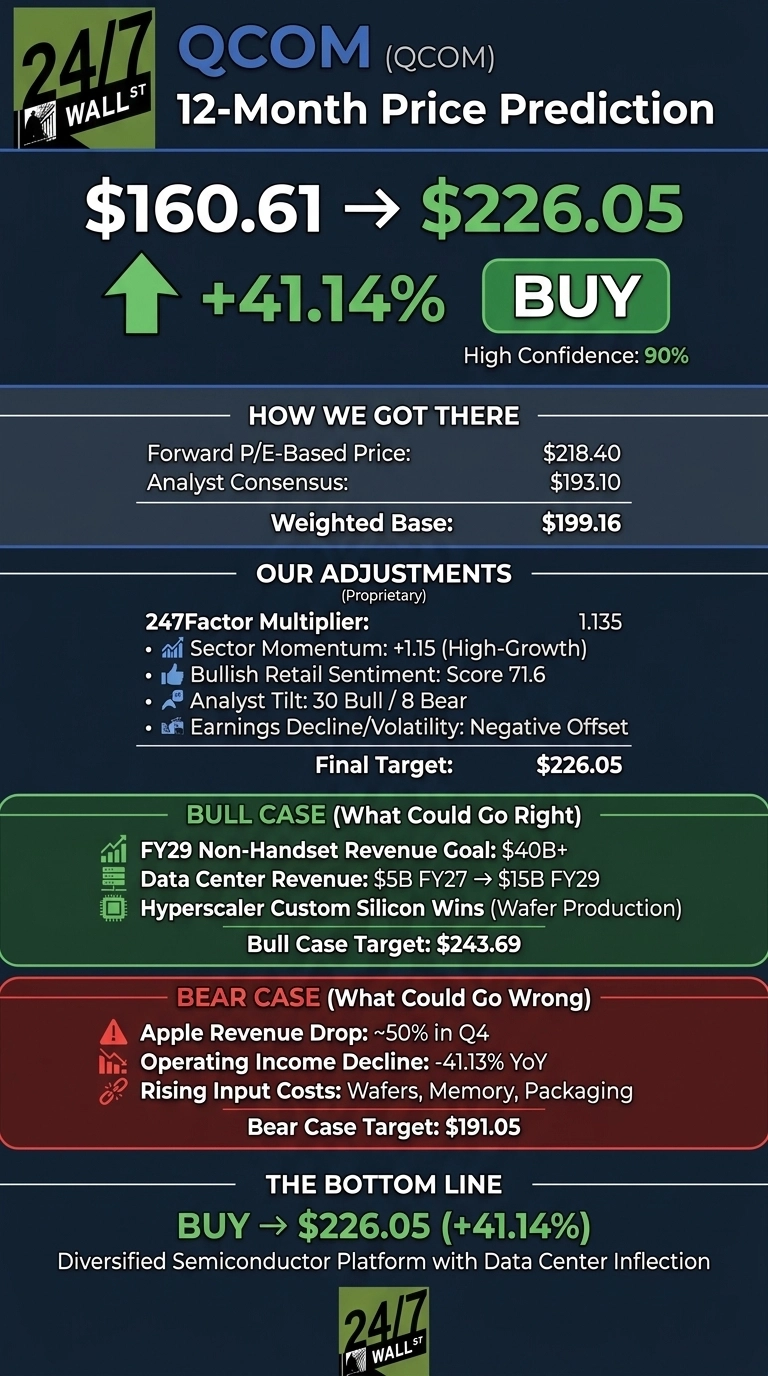
The 24/7 Wall St. price target for Qualcomm is $226.05 over the next 12 months, implying 41.14% upside from the current $160.61 quote. Our recommendation is buy, with a high confidence level of 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $160.61 |
| 24/7 Wall St. Price Target | $226.05 |
| Upside | 41.14% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Rough Stretch With a Sharper Story Underneath
QCOM shares are down 2.46% over the past week, 7.35% over the past month, and 5.06% year to date, well off the $258.96 52-week high.
Fiscal Q3 revenue of $9.947 billion beat consensus by roughly 2.84%, but non-GAAP EPS of $2.21 narrowly missed expectations, ending a six-quarter beat streak. Handset revenue fell 20% year over year, while automotive rose 61% to $1.588 billion. That mix shift is the story the market is under-pricing.

Why Bulls See a Breakout Ahead
The bull thesis centers on non-handset revenue. CEO Cristiano Amon said Qualcomm is targeting “total non-handset revenues growing to $40 billion by fiscal 2029, nearly double the target we shared in November 2024”, with growth accelerating from 24% in fiscal 2026 to greater than 60% in fiscal 2027.
Data center alone is projected to scale from $5 billion in fiscal 2027 to $15 billion in fiscal 2029, backed by two hyperscaler custom silicon wins already in wafer production with revenue starting the December quarter (the same data-center buildout we mapped across seven non-chipmaker suppliers in a free AI infrastructure report).
HBC Gen 1 has taped out, with a first solution launch targeted for mid-2027. Our bull case forecast points to $243.69, a 52.16% total return.

What Could Go Wrong
Apple product revenue is expected to fall roughly 50% from September to December quarter, with fiscal 2027 share landing materially below the prior 20% assumption. Operating income fell 41.13% year over year in Q3 amid broad-based increases in wafer, packaging, and memory costs.
Management expects planned double-digit price increases to restore gross margin to the historical 48% to 50% range. The margin decline reflects heavy investment in the data center roadmap that our model rewards. Our bear case still lands at $191.05, a 19.29% gain from here.
How Qualcomm Compares to Broadcom and Marvell
Broadcom (NASDAQ: AVGO) is the incumbent in hyperscaler custom silicon and sets the valuation ceiling. AVGO trades at a rich multiple relative to QCOM’s forward P/E of 16, framing how much re-rating room Qualcomm has if its two hyperscaler wins scale as guided.
Marvell Technology (NASDAQ: MRVL) competes head-on for custom ASIC and networking sockets at the same hyperscalers Qualcomm just landed. Marvell already carries an AI premium; Qualcomm trades near 18x trailing earnings with an EV/EBITDA of 13. On the same data center opportunity, Qualcomm looks meaningfully cheaper, making our 24/7 Wall St. price target of $226.05 reasonable rather than aggressive.

Qualcomm Price Prediction 2026-2030
Buy, with high confidence. The 24/7 Wall St. price target of $226.05 rests on a forward multiple that is not demanding, a genuine data center inflection in fiscal 2027, and record automotive momentum.
The setup strengthens if fiscal Q4 confirms pricing-driven margin recovery and the December-quarter custom silicon ramp lands on schedule. The thesis weakens if handset weakness deepens beyond the guided low-teens fiscal-year decline or if HBC customer engagements slip past mid-2027.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $180.11 |
| 2027 | $226.05 |
| 2028 | $282.29 |
| 2029 | $345.81 |
| 2030 | $382.57 |
These projections assume Qualcomm executes on the $40 billion non-handset revenue target. Significant upside or downside could come from the pace of hyperscaler custom silicon ramps and the trajectory of memory and wafer input costs.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.