Deutsche Bank Turns Bullish on Netflix, Says Global Engagement Is Underappreciated
Wall Street is split on Netflix after a brutal year for the stock, but Deutsche Bank just broke from the crowd with an upgrade built on a part of the business most investors are ignoring.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Deutsche Bank upgraded Netflix (NASDAQ:NFLX | NFLX Price Prediction) to Buy from Hold. In the same note, it cut its price target to $95, down from $100. The firm says that the market’s “obsession” over U.S. time spent on Netflix overlooks the company’s larger total addressable market and “healthier” international engagement trends.
The upgrade suggests Wall Street is paying closer attention to Netflix’s global reach after a sharp sell-off.

| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| NFLX | Netflix | Deutsche Bank | Upgrade | Hold | Buy | $100 | $95 |
Deutsche Bank’s Case Rests on Overseas Viewing
According to the research note, Netflix’s international time spent has increased year-over-year in each of the past four six-month periods. Deutsche believes this year’s weakness in U.S. time spent “could simply be driven by less creative success,” a problem the next round of hits could fix.
The firm also says Netflix has an “established competitive advantage and substantial lead” over competitors in international production. It adds that the stock’s valuation now offers an attractive entry point.
Company data backs up that view. Non-English content drives more than a third of all viewing. View hours grew 2% in H1 2026 vs. 1.5% in 2025, even with competition from the Winter Olympics and World Cup.
Company Snapshot: Double-Digit Growth in Every Region
Second-quarter revenue rose 13.4% YoY to $12.56B, just short of the $12.58B estimate. EPS of $0.80 beat expectations of $0.79, and operating margin reached 33.4%. Latin America grew 21%, Asia Pacific 16%, EMEA 14% and North America 10%.
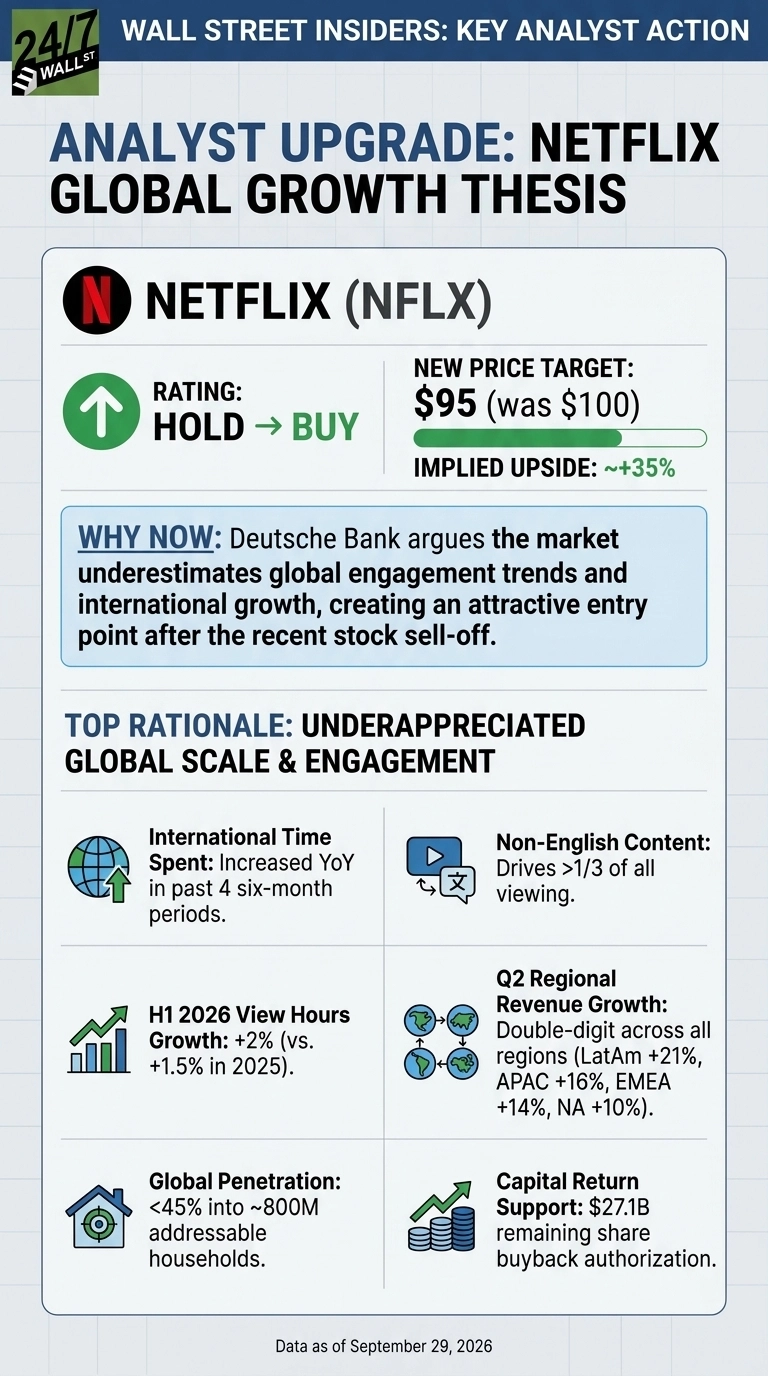
Management said Netflix is “under 45% penetrated into addressable households around the world,” out of roughly 800 million such households. Full-year revenue guidance stands at $51B to $51.4B, and advertising revenue is expected to roughly double to about $3B.

Why the Move Matters Now With Shares Down Sharply in 2026
Netflix stock trades at $70.49. It is down 24.82% year to date and 41.77% over the past year. Its 52-week range runs from $65.08 to $124.86, and it trades at about 19x forward earnings.

The timing is notable. On the same day, Bloomberg reported that analysts are souring on the stock as growth fears mount, which puts Deutsche on the opposite side of that trend.
The overall consensus still tends positive, with 7 Strong Buy, 28 Buy and 16 Hold ratings, no Sell ratings and an average target of $92.93. Buybacks add support: Netflix bought back $4.7B of stock in Q2 and has $27.1B remaining under its authorizations.

What It Means for Your Portfolio
Retirement-focused investors should consider the international growth story against some real risks. Free cash flow fell to $1.53B from $2.27B a year earlier, largely because of higher cash taxes. In addition, $1 billion of debt matures later in 2026. Over the past 30 days, analysts made 3 up and 4 down revisions to 2027 EPS estimates.
The next test is the third-quarter earnings report. Management guided for revenue of $12.86B and EPS of $0.82. Watch whether international engagement keeps growing and whether U.S. viewing steadies. The revised outlook deserves a closer look from long-term investors, even though near-term volatility remains a real risk.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.