Salesforce Is Down Double Digits This Year. Our Model Sees 48% Upside
Salesforce shares have shed double digits this year while Wall Street quietly revised its earnings estimates sharply higher, creating a gap between price and fundamentals that few investors are watching closely enough.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
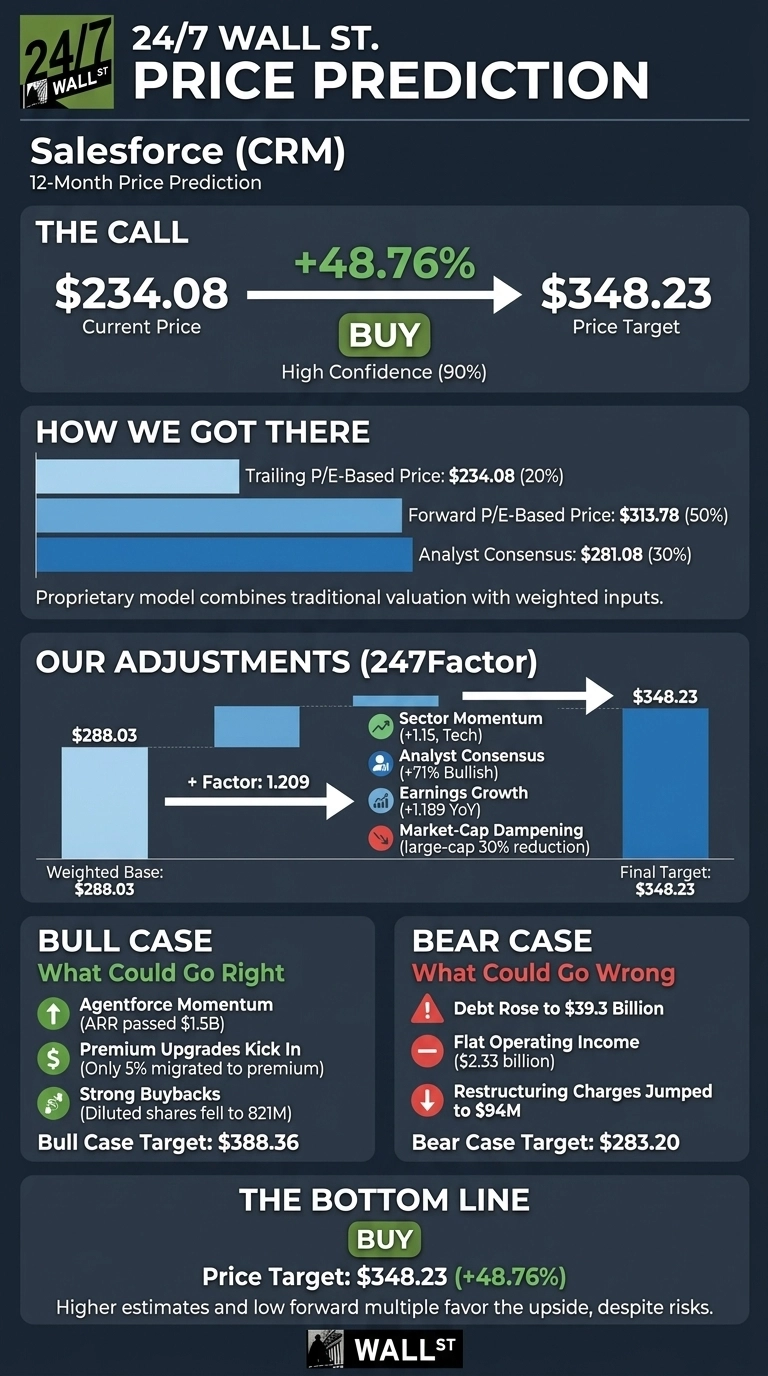
Our 24/7 Wall St. price target for Salesforce (NYSE:CRM | CRM Price Prediction) is $348.23. That means 48.76% upside from the current $234.08.
| Metric | Value |
|---|---|
| Current Price | $234.08 |
| Price Target from 24/7 Wall St. | $348.23 |
| Upside/Downside | 48.76% |
| Recommendation | BUY |
| Confidence Level | 90% |

Shares earn a buy rating from the model with high confidence. My case comes down to one gap. Shares are down 11.04% year to date.
Over the same period, the consensus fiscal 2027 EPS estimate rose to 16.7553 from 14.1285 just 90 days earlier. At about 16x forward earnings, Salesforce is priced like a slow grower, even though its AI products are expanding at triple digits.
Agentforce Momentum Fuels a 14% One-Month Rebound
CRM rose 14.02% over the past month, then slid 1.64% last week. It trades 12.59% below its 52-week high of $267.80 and 60.26% above its low of $146.06.
The fiscal Q2 report on August 26 delivered revenue of $11.35 billion (up 10.83%), beating the $11.32 billion estimate. Non-GAAP EPS came in at $5.90 against a $3.27 forecast. About $2.53 per share of that came from gains on strategic investments.
Agentforce ARR passed $1.5 billion (up 240%), and management raised its fiscal 2027 revenue guidance to $46.1 billion to $46.4 billion. Dreamforce and an investor session on September 16 put the new Anthropic Claude partnership in front of customers.

Bulls See a Path to $388 as Premium Upgrades Kick In
Bullish cases point to $388.36. On the earnings call, management said only 5% of Sales and Service knowledge workers have moved to premium editions, which cost 60% to 80% more.
AI customers already spend about double the AOV of other customers. Buybacks also help: diluted shares fell to 821M from 962M. Analyst ratings stand at 40 buy or strong buy, 14 hold and 2 strong sell.

Debt and Flat Operating Income Could Cap Gains
Even the downside scenario lands at $283.20, but the risks are real. Debt rose to $39.3 billion from $10.4 billion. Operating income was flat at $2.33 billion, and restructuring charges jumped to $94M from $4M.
The fiscal 2028 EPS consensus of 16.0067 is below fiscal 2027’s estimate. That dip mostly reflects one-time investment gains ballooning the current year. The added debt paid for shares bought back at an average of $176, below today’s price, and guidance calls for a non-GAAP operating margin of 34.3%.
Salesforce Screens Cheaper Than Microsoft and ServiceNow
Microsoft (NASDAQ:MSFT) competes head-on with Dynamics 365 and Copilot. The stock trades at 29x earnings with a 1.75% free cash flow yield. Salesforce trades at 26x with a 7.48% yield.
ServiceNow (NYSE:NOW) competes for the same enterprise agentic AI budgets. It increased revenue 24.01%, but operating income fell 54.75%. Neither peer’s numbers suggest our target is too aggressive.
| Company | Latest Quarter Revenue Growth | Latest Quarter FCF |
|---|---|---|
| Salesforce | 10.83% | $1.10B |
| Microsoft | 17.75% | $19.64B |
| ServiceNow | 24.01% | $634M |
Salesforce Price Prediction 2026-2030
The 24/7 Wall St. price target of $348.23 comes with a buy rating and 90% confidence. The biggest reason is higher estimates coupled with a low forward multiple.
A more positive view would follow if Agentforce continues adding production customers and cRPO growth holds near 14%. I’d turn conservative if operating income stays flat once the Informatica, Contentful and Fin consolidations are done. The data, for now, favors the upside.

| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $263.75 |
| 2027 | $348.23 |
| 2028 | $414.52 |
| 2029 | $493.42 |
| 2030 | $587.35 |
These projections assume Salesforce continues executing its AI strategy. Faster premium-edition adoption could push results higher, and trouble integrating acquisitions could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.